


CoreWeave (CRWV) Stock May Stay Near Fair Value As AI Revenue Fears Ease
CoreWeave has been hit hard over the past year, and the slide has put a sharp focus on a simple question for investors who care about fundamentals. Do the cash flows that CoreWeave can generate over time support where the stock now trades?
- Over the past 12 months, CoreWeave shares have fallen 43.3%, which puts recent enthusiasm for AI infrastructure to the test against what the business can realistically earn in cash.
- Recent moves to expand AI cloud capacity, including large data center projects and a sizeable AI infrastructure loan tied to uptime performance, may support higher future revenue but also concentrate execution risk and funding needs into CoreWeave's cash flow profile.
- What if you looked at CoreWeave through its sales instead? See why CoreWeave's 5.8x P/S tells a different valuation story.
The stock's next move may depend on whether CoreWeave's current price is adequately supported by the intrinsic value implied by its cash flows.
If you want to test the same cash flow question that CoreWeave now faces across a wider set of AI infrastructure plays, scan through 92 AI infrastructure stocks.
Does CoreWeave Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash CoreWeave can return to shareholders over time and compares that with today's share price. On this view, the latest twelve month free cash flow shows an outflow of about $14.7 million, with projections still pointing to sizeable cash burn in the near term before a move into positive territory closer to 2030.
Analysts feeding into this DCF are effectively assuming that CoreWeave shifts from loss making cash flows to growing positive free cash flow later in the next decade, which needs heavy upfront investment and reliable access to capital. That path helps explain why the DCF outcome sits broadly in line with the current share price of $80.26 rather than clearly cheap or expensive. The $2.6 billion AI infrastructure loan and its uptime linked repayment risk underline why the market may be cautious even though the cash flow model does not flag a large mismatch between intrinsic value and price. Find out what CoreWeave could be worth using our Discounted Cash Flow (DCF) estimate.
The CoreWeave Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take CoreWeave's valuation puzzle and spell out what would need to happen to growth, margins and earnings for the share price to move meaningfully higher or lower from here. They then anchor those scenarios on the Community page. Instead of a single headline multiple or model output, each narrative lays out the key assumptions behind its fair value view so you can compare them with CoreWeave's actual results as they arrive.
Community views on CoreWeave are split between a financing-heavy risk story and a capacity-led upside story tied to AI demand.
Bull case: 64% undervalued
"Explosive global adoption of AI across enterprises, AI-native startups and the public sector is driving sustained, demand-led expansion of CoreWeave revenue…"
Discover why this Narrative puts CoreWeave at 64% undervalued.
Bear case: 15% overvalued
"There is a concerning "Capex Treadmill" here, where every dollar of operational cash flow must be recycled immediately into the next generation of NVDA GPUs…"
Explore why this Narrative puts CoreWeave at 15% overvalued.
One more CoreWeave signal worth checking before you move on
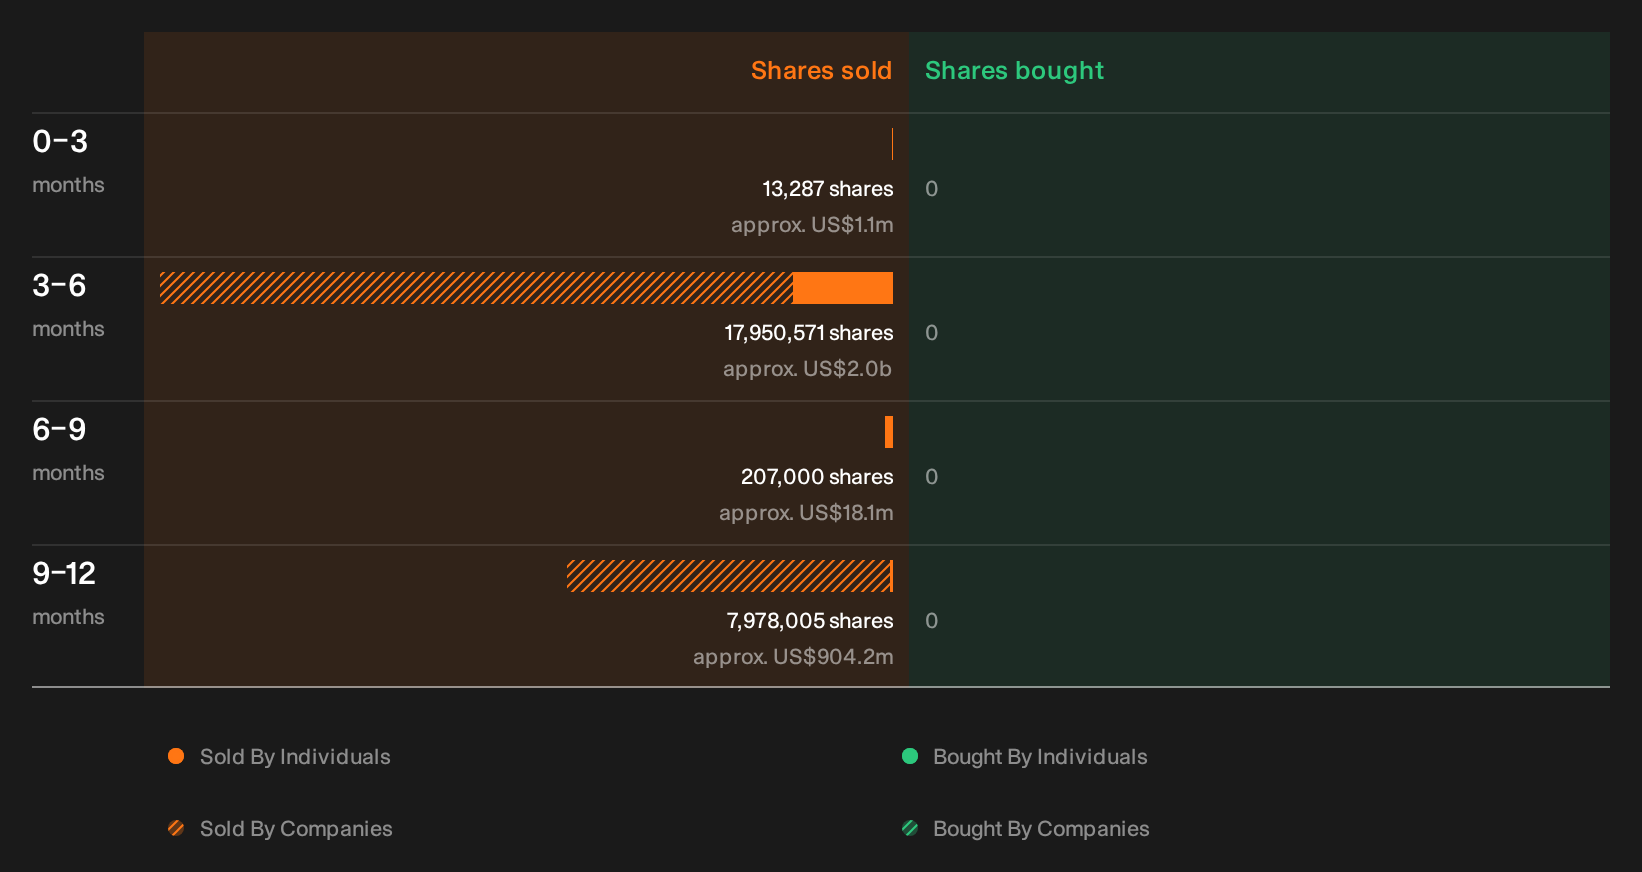
Before acting on any view of CoreWeave, it helps to know which insiders have recently been trimming their exposure, how much they sold, and what that pattern might suggest for alignment with outside shareholders. See the recent insider selling flagged for CoreWeave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com