


Quanta Services (PWR) Could Be 2% Below Fair Value As AI Revenue Story Grows
Quanta Services (PWR) is back in focus after management highlighted rising AI infrastructure work, with data center and technology clients projected to reach about 18% of revenue by 2026. This supports a premium valuation narrative.
The AI story is landing on a stock that already has strong momentum, with the share price up 6.8% over the past month and 58.0% year to date. The 1 year total shareholder return of 61.3% and very large 5 year gain suggest long term enthusiasm has been building rather than fading.
Scan other AI infrastructure plays focused on similar themes to Quanta Services by reviewing our hand picked list of 92 AI infrastructure stocks.
Quanta Services now trades with a rich AI story and a premium tag after a powerful run. The key question is whether that recent surge still leaves enough upside to justify paying this kind of multiple today, or whether most of the payoff has already been claimed.
Most Popular Narrative: 2% Undervalued
Quanta Services is framed as slightly undervalued in the most followed narrative, with a fair value of $710 against a last close of $694.79. That small gap keeps the focus on whether the business quality and AI power buildout justify paying a premium.
The long case is simple: Quanta sits at the intersection of several unusually durable spending waves: aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand. The company’s scale, labor base, customer relationships, and expanding “total solutions” model make it one of the few contractors able to execute very large, complex programs.
See why 68 investors see Quanta Services as 2% undervalued.
Result: Fair Value of $710 (UNDERVALUED)
Still, the Quanta Services story can crack if large projects are delayed or if any stumble in execution dents confidence in those premium multiples.
Find out about the key risks to this Quanta Services narrative.
Another View: Quanta Services Looks Expensive On Earnings
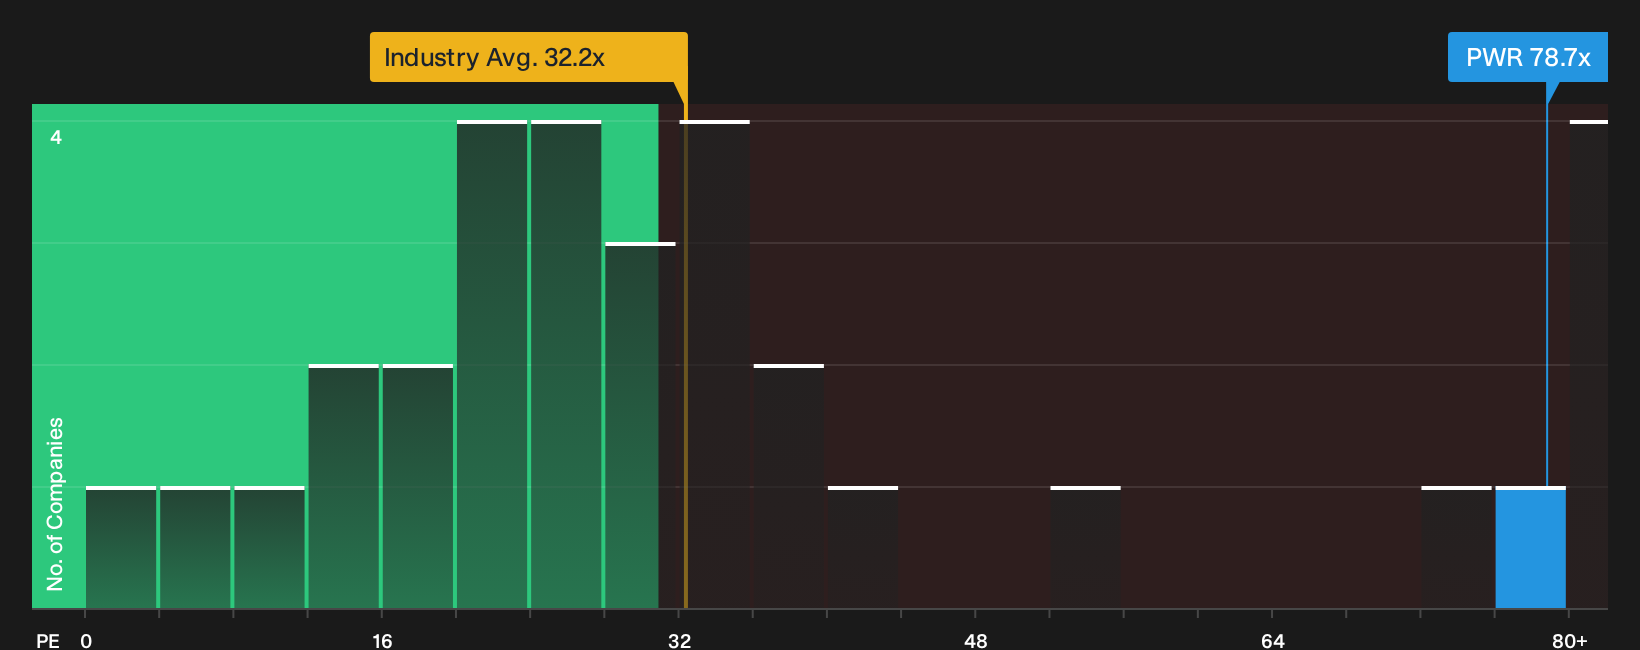
The fair value narrative around Quanta Services leans on a $710 target, yet the simple earnings multiple tells a tougher story. The stock trades on a P/E of 78.7x while US Construction peers average 32.2x and the fair ratio sits at 38.2x. That gap points to meaningful valuation risk if sentiment cools.
For investors who want to see how that rich P/E stacks up in detail, take a closer look at the valuation breakdown in our earnings multiple view, including how it compares with both peers and the fair ratio, through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Quanta Services so far. If you want to move quickly and anchor your own view in the numbers, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quanta Services?
If Quanta Services intrigues you, do not stop here. Use the Simply Wall St screener to uncover fresh opportunities that fit your own risk and return preferences.
- Target stronger balance sheets by scanning companies on our list of solid balance sheet and fundamentals (25 results) and compare how financial resilience lines up with your comfort level.
- Hunt for potential mispricing by reviewing the 29 high quality undervalued stocks and see which businesses trade below their assessed worth.
- Prioritise stability and income by checking out a curated 8 dividend fortresses that focuses on higher yielding payouts with substance behind them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com