


Is Bandwidth (BAND) Overvalued After Its 385% Three Year Run?
Bandwidth has seen its share price reshape investor expectations in a short space of time, and today the core issue is whether that move lines up with what the business is generating in sales. After a run like this, the central question is how much current revenue and the potential for future top-line expansion can reasonably support the stock.
- Over the past 3 years, Bandwidth has delivered a share price return of 384.7%, which puts a lot of weight on whether its sales now justify this kind of re-rating.
- Recent revenue growth and new customer wins around its Maestro platform and AI services, including work tied to Salesforce's global contact center expansion, can influence how investors think about the durability of sales and the timing of stronger cash generation.
- Your read on Bandwidth is one view; the desks covering it have another. See what analysts think Bandwidth's shares could be worth.
The issue now is whether Bandwidth's current share price is justified by its sales when set against the Fair Ratio benchmark.
If you want to explore the same question about sales and price across a broader range of stocks, review 29 high quality undervalued stocks.
Has Bandwidth Run Too Far on Sales?
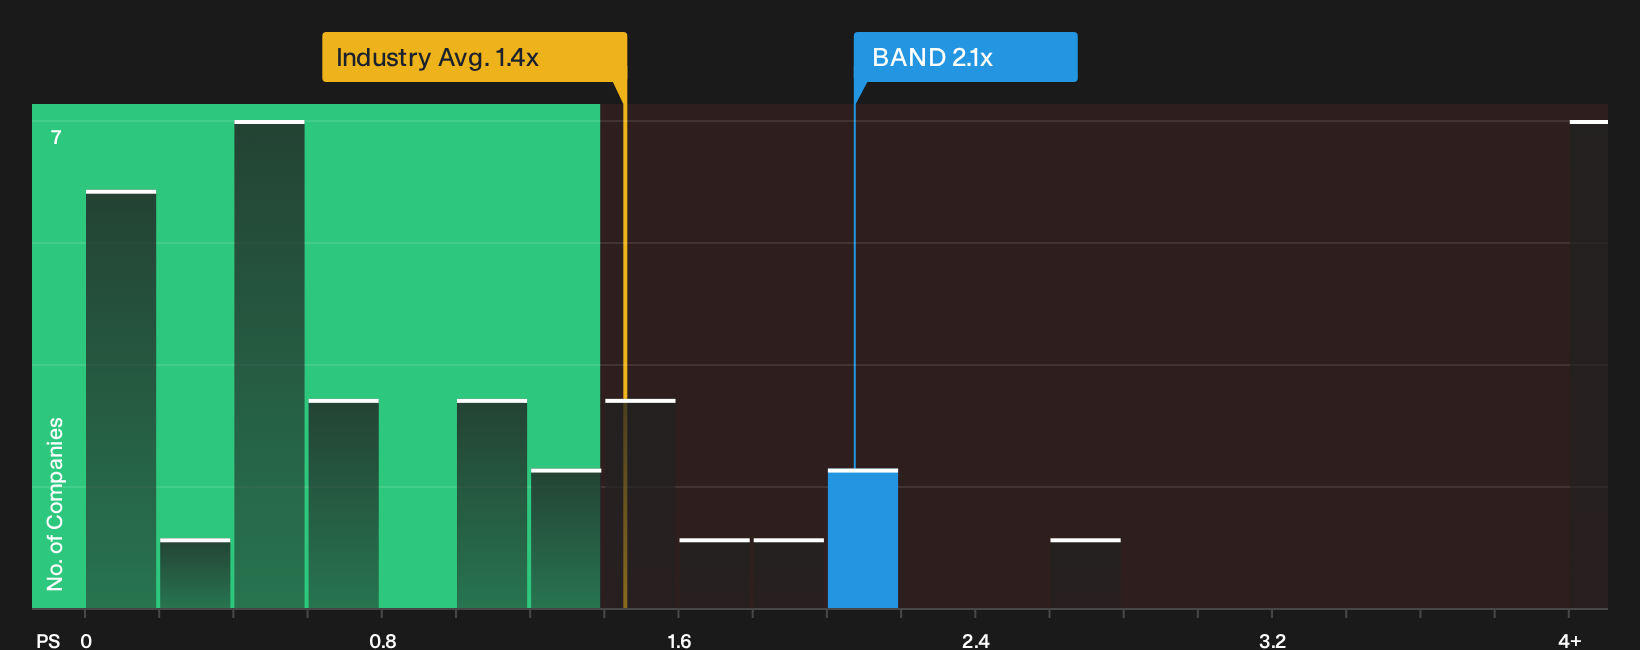
P/S fits Bandwidth because investors are weighing it primarily on revenue rather than current earnings. The stock trades on a P/S of 2.1x, close to both the telecom sector average of 1.4x and the peer group at about 2.1x. That cluster suggests the market is not treating this as a clear outlier on headline sales, even after the sharp share price move.
The Fair Ratio, which blends Bandwidth’s growth profile, margins, size and risk into a single benchmark, sits below the current P/S. That gap indicates the shares are screening as overvalued on this sales lens, despite the Q2 revenue upgrade and high profile Maestro and AI wins tied to Salesforce. For anyone considering the stock, the key question is whether those contracts and the 22% revenue step change truly justify paying a richer multiple than the fundamentals based Fair Ratio implies. Explore the numbers behind Bandwidth's P/S valuation.
The Bandwidth Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Bandwidth pick up where the valuation puzzle leaves off. Narratives describe the specific growth, margin and earnings paths that would need to occur for Bandwidth's share price to appear materially higher or lower than it does today. They are available on the stock's Community page so you can see in plain terms the future that any single P/S ratio or fair value estimate is based on, and then watch how reality compares over time.
Community views on Bandwidth split between those who see more upside in the AI and cloud story and those who focus on concentration and margin risk.
Bull case: 21% undervalued
"Accelerating enterprise adoption of AI-powered voice applications, driven by Bandwidth's Maestro platform and integrations, is already delivering a 3x-4x uplift in revenue per call..."
Discover why this Narrative puts Bandwidth at 21% undervalued.
Bear case: roughly fairly valued
"Dependence on legacy communication APIs and large clients exposes Bandwidth to shrinking revenue and unpredictable recurring income as market shifts accelerate..."
Explore why this Narrative puts Bandwidth at roughly fairly valued.
Bandwidth: why the share price is only half the story
Price and sales ratios frame one side of Bandwidth, but the research checks also flag specific risk signals that deserve a closer look before any decision. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com