


Can Chevron (CVX) Keep Looking Cheap As Cash Flow Builds?
Chevron has ridden a powerful multi year upswing, with the stock closing at US$211.98, and the question now is whether that price can be squared with the cash the business is producing and expected to produce. With fresh headlines on regulation, operations and leadership reshaping the story, the issue for you is how much of Chevron's cash flow future is already embedded in that valuation.
- Over the past 5 years, Chevron has delivered a total shareholder return of 136.4%, which puts real weight on getting its cash flow valuation right at today’s level.
- Recent moves to cut Bakken midstream costs, ramp US production and adjust its asset mix can reshape Chevron’s future cash margins and the timing of the cash it returns to investors.
- What if you looked at Chevron through its earnings instead? See why Chevron's 20.2x P/E tells a different valuation story.
For investors, the debate is whether Chevron's current share price is adequately supported by the cash flows implied in its intrinsic value estimate from a Discounted Cash Flow (DCF) model.
For a broader starting list as you compare Chevron's cash flows with its US$211.98 share price, apply the same approach to 29 high quality undervalued stocks.
Does Chevron Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Chevron can generate for shareholders over time. Latest twelve month free cash flow sits at about $27.2b, and the projections used in the 2 Stage Free Cash Flow to Equity framework assume that free cash flow grows from that base rather than shrinking away.
Within that setup, the DCF outputs an intrinsic worth that is substantially above the current share price of US$211.98. This means the market is attaching a lower value to those projected cash streams than the model implies. Because the Trump EPA move to roll back methane rules points to lower potential compliance costs for oil and gas producers, that regulatory backdrop helps explain why investors may see room for stronger future cash generation than today’s price fully reflects. Find out what Chevron could be worth using our Discounted Cash Flow (DCF) estimate.
The Chevron Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Chevron pick up exactly where the cash flow puzzle leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each narrative links a fair value estimate to a clear storyline about Chevron's possible catalysts and risks, so you can track over time which version of events is actually unfolding on the Community page.
One of the top community narratives on Chevron: roughly fairly valued
"The main thing that has to go right is for Chevron to continue executing on capital efficient growth in assets like Venezuela, the Permian and Tengiz…"
Discover why this Narrative puts Chevron at roughly fairly valued.
One more Chevron signal to check before you make a move
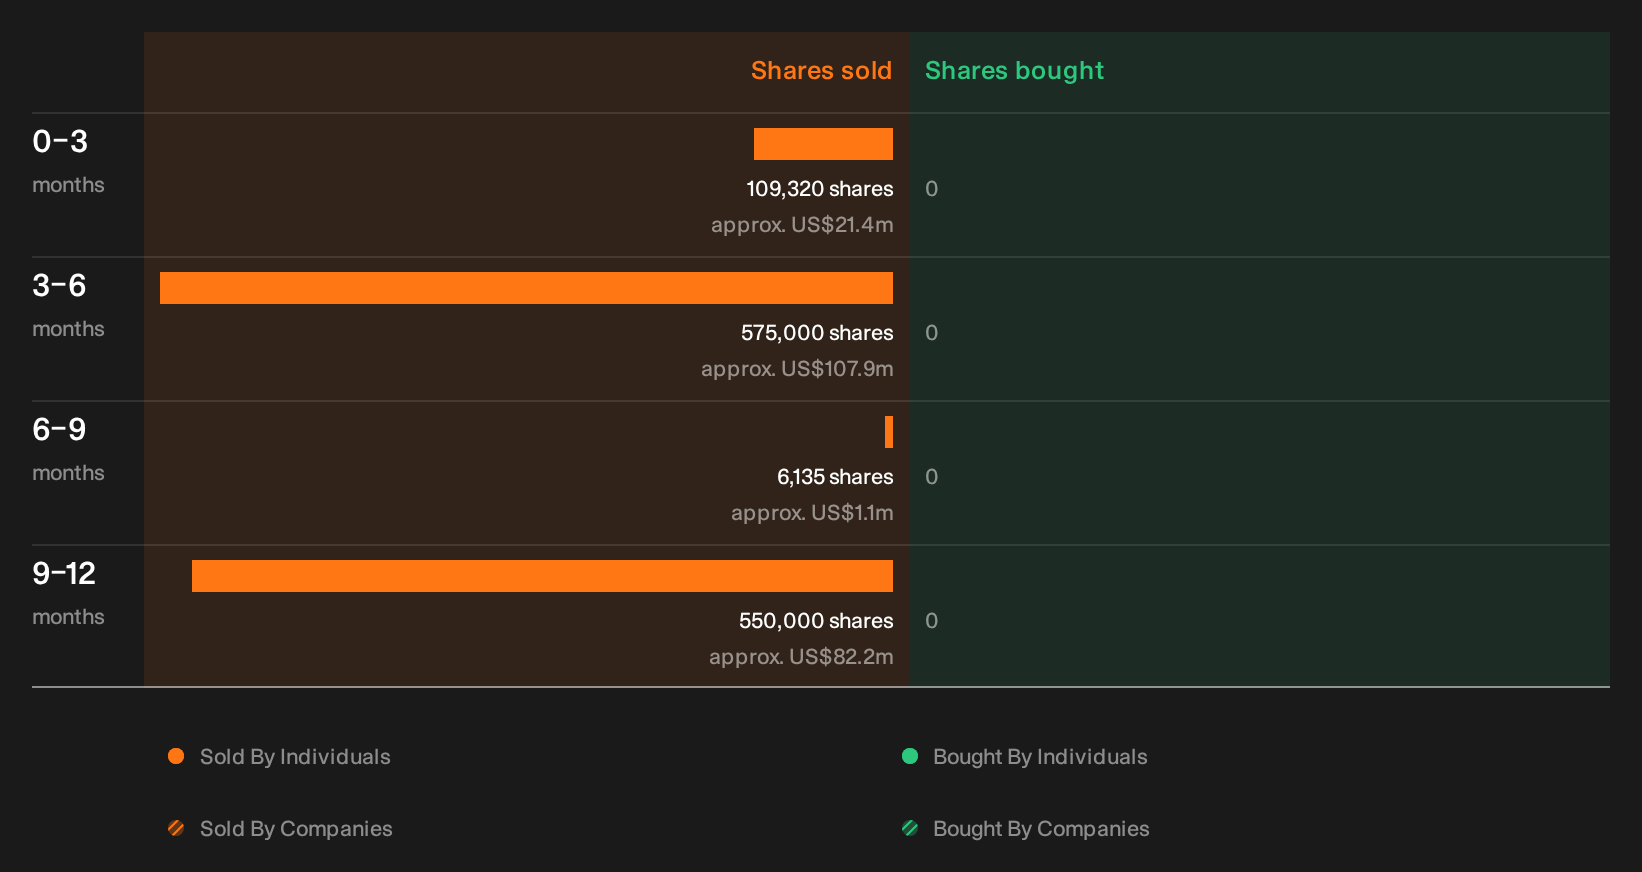
Before you lean too hard on Chevron's valuation story, it is worth knowing that recent insider share sales have been flagged by our checks and the who, how much and possible meaning are still for you to explore. See the recent insider selling flagged for Chevron.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com