


Why Super Micro Stock Is Heading to $60
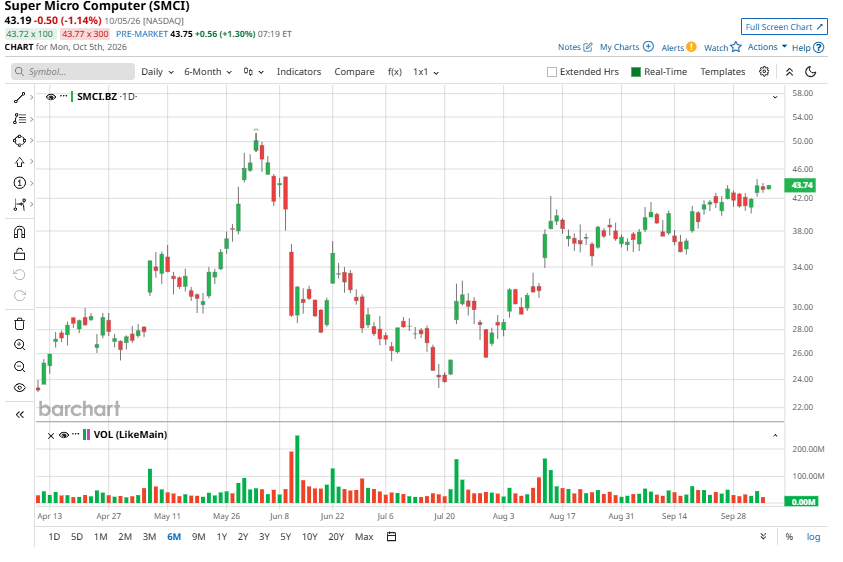
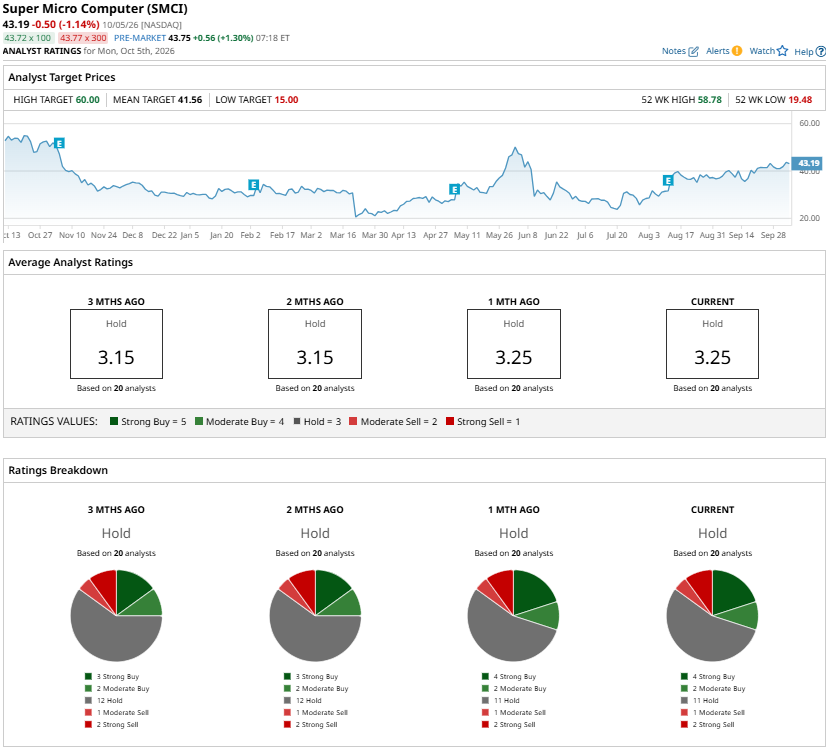
Super Micro Computer (SMCI) has made a remarkable comeback, with its stock more than doubling from the recent lows. After this impressive rebound, SMCI stock is now trading higher than analysts’ average price target of $41.56. Even so, the stock still has room to move higher, with the highest Wall Street target currently at $60, implying about 39% upside from current levels.
One of the biggest drivers of the optimism is accelerating demand for its AI solutions. As companies invest more heavily in AI, Super Micro is benefiting from the need for high-performance servers and data center solutions. The company is also working to improve its profitability by expanding its enterprise customer base. Moreover, growing adoption of its optimized Data Center Building Block Solutions (DCBBS) architecture further strengthens its bottom-line growth outlook.
Super Micro also has a significant order pipeline, giving the company a solid foundation for future growth.
Super Micro Stock Has Further Upside
Super Micro Computer has several catalysts supporting further upside in its share price. Strong AI infrastructure spending, a large order pipeline, broader customer diversification, and potential margin expansion collectively strengthen its growth outlook.
The company delivered solid growth in FY26, with revenue rising 78% year over year to $39.1 billion and adjusted earnings per share climbing 76% to $3.63. This momentum is unlikely to slow as AI demand accelerates.
Management expects AI-related products to account for more than 80% of revenue in the coming quarters. With over $60 billion in new orders booked during Q4, SMCI has significant revenue visibility heading into FY27.
Growth is also becoming less dependent on hyperscale customers. Enterprise and channel revenue reached $5.6 billion in Q4, representing half of total revenue. The segment expanded 172% year over year, reflecting accelerating demand for upgraded computing, storage, and networking infrastructure. This trend is likely to persist and give SMCI a broader, more balanced revenue base.
Customer concentration is improving as well. The number of customers contributing more than $1 billion annually increased to nine in FY26 from four a year earlier. Further diversification across hyperscalers, enterprises, and channel partners could make revenue growth more resilient as AI capital spending evolves.
While competitive headwinds could pressure its short-term margins, SMCI is emphasizing higher-value inference and agentic AI systems, greater adoption of DCBBS, automation, design efficiencies, and improved manufacturing yields. These initiatives could gradually lift margins.
Super Micro is also expanding through enterprise CPU servers, storage, and IoT products. Its growing portfolio of inference and agentic AI offerings could further broaden its addressable market while improving revenue quality.
Despite the stock's strong recovery, valuation remains relatively modest, supporting further upside. SMCI trades at a forward P/E of 10.6, which appears reasonable as analysts expect earnings to grow by more than 20% annually through fiscal 2028.
With strong earnings growth and a reasonable valuation, SMCI stock could rise further.
The Final Takeaway
Overall, the recovery in Super Micro Computer stock is supported by structural growth in AI infrastructure spending, a substantial order pipeline, stronger enterprise and channel demand, and a broader customer base. With AI-related products likely to represent more than 80% of revenue in the coming quarters, SMCI is positioned to deliver solid growth ahead. At the same time, growing adoption of its DCBBS, manufacturing efficiencies, and a greater focus on higher-value inference and agentic AI systems could help address margin pressure and improve profitability over time.
While analysts maintain a “Hold” consensus rating on SMCI stock, its valuation strengthens the bullish case. Competition, execution risks, and margin volatility remain important considerations, but accelerating AI demand and Super Micro’s increasingly diversified enterprise customer base provide a strong foundation for further upside. These factors could give the stock sufficient momentum to reach the $60 price target.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.