


What Lloyds Banking Group Doubters Got Wrong
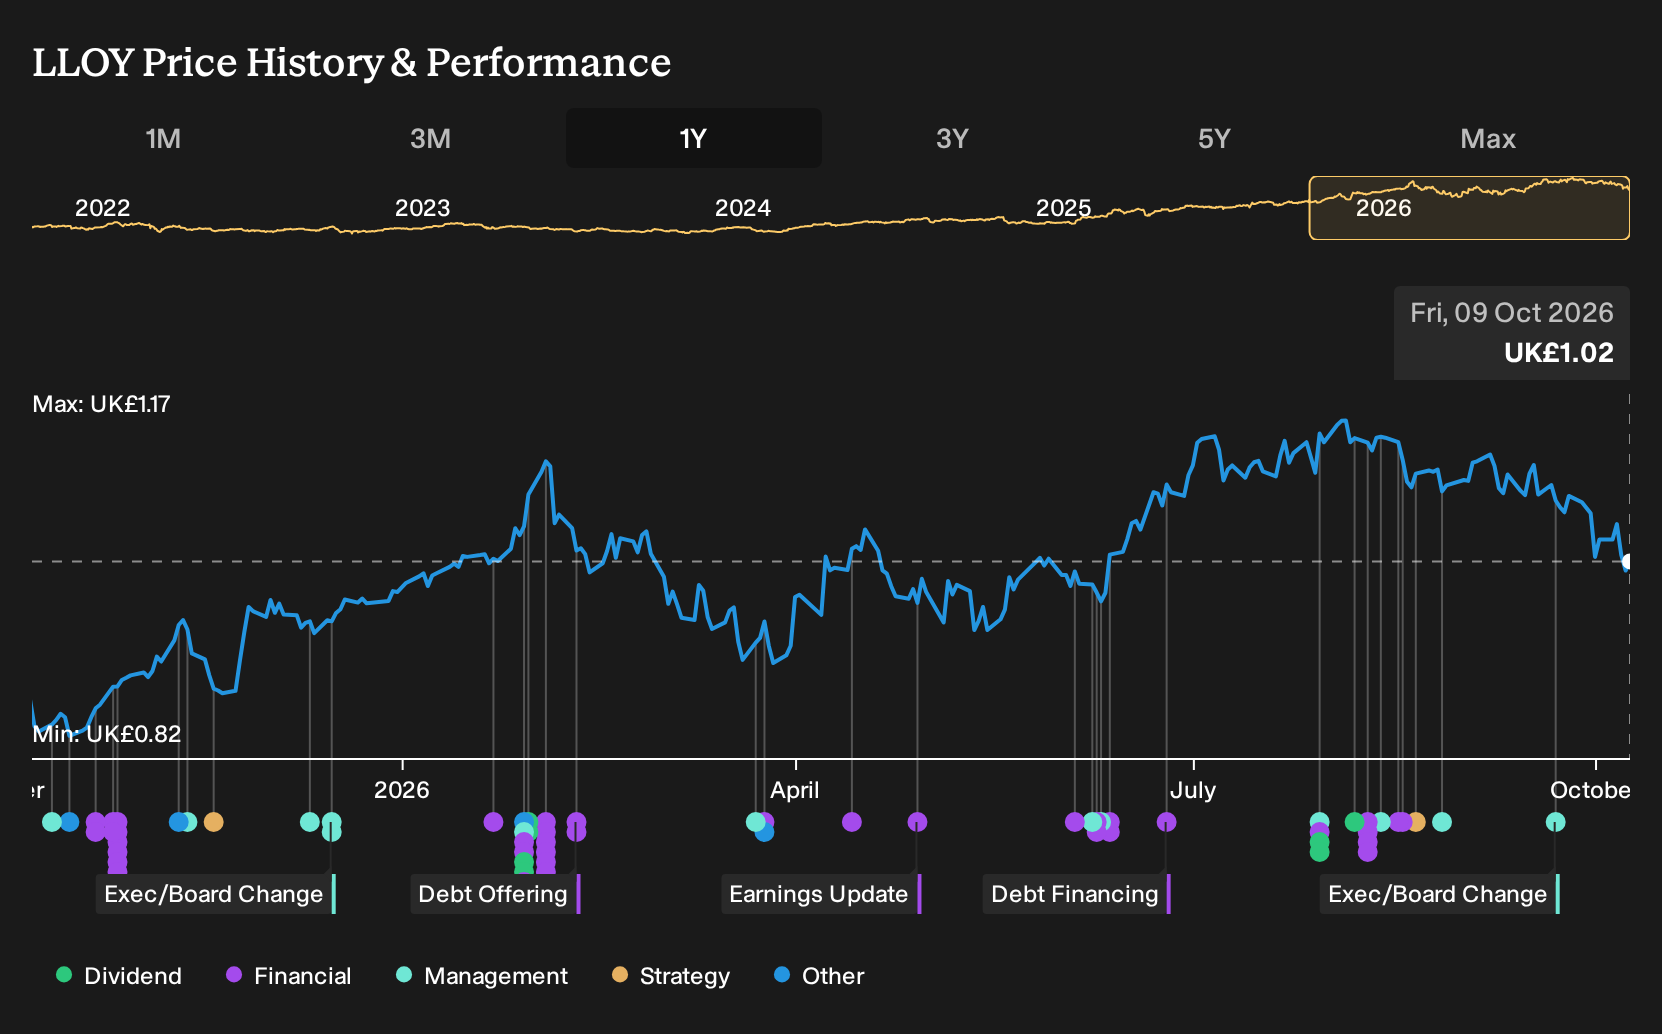
If you only glanced at Lloyds Banking Group headlines in 2025, the split views were hard to miss. Bulls pointed to digital progress and ageing UK demographics, while bears focused on mortgage concentration, rising IT spend and regulatory costs. For Lloyds Banking Group shareholders, the return over the past year was 26.1%, including dividends. Faced with those competing narratives back in October 2025, what in the record would have deserved your trust?
If the move has made Lloyds Banking Group harder to judge, start where the gap is still open and scan 7 high quality undervalued stocks.
The Two Stories Investors Were Weighing On Lloyds Banking Group
The shares cost £0.83 at the start of the period, and anyone looking at Lloyds Banking Group then had to decide which story about the future felt more convincing.
On the optimistic side, the bull narrative argued that heavy digital transformation and AI spending would cut costs and improve earnings quality. This view suggested a fair value of £0.89, the price implied if higher margins and a future P/E of 11.1x occurred under the stated assumptions.
The bear narrative focused on UK mortgage concentration and rising technology and compliance costs as the main threat. This perspective supported a fair value of £0.53 and was based on the idea that profit margins might soften to about 22.2% even if revenue growth stayed at 8.0%.
What The Results Changed For The Lloyds Banking Group Argument
Lloyds Banking Group rolled out its Accelerate 2030 plan, pairing about £2b of targeted cost cuts with heavy AI and digital spend. That direction leaned toward the optimistic story of tech driven efficiency. At the same time, the Q2 2026 numbers, with revenue and profit both higher but net margin flat at 27.8%, kept the profitability claim unproven. Taken together, the evidence cut both ways.
The hinge assumption was that digital investment would widen margins, not just lift earnings. When you assess another bank, track whether cost savings and tech budgets show up in a higher net margin, not only in bigger profit.
What Lloyds Banking Group's Price Already Assumes
Lloyds Banking Group now trades at £1.02, with the selected Narrative’s Fair Value sitting below that level. Over the past year, the total return was 26.1%, so current buyers are paying up for what looks like successful execution on the existing plan.
The Narrative’s concern is not fintech disruption but the grind of IT, regulatory and hedge management costs. Anyone paying today’s price is effectively assuming those heavy AI projects, operational fixes and structural hedging choices work as intended. The key question is how that assumption aligns with the risks the selected Narrative highlights.
"Although Lloyds Banking Group is investing heavily in AI capabilities and data infrastructure, the recent two hour outage across Lloyds, Halifax and Bank of Scotland mobile apps in August 2026, which followed an earlier disruption in the same quarter, points to rising operational fragility that could force higher ongoing IT spend and remediation costs, putting pressure on net margins."
The price and this Narrative do not agree. → Uncover what this Narrative says Lloyds Banking Group is actually worth
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 27% below our estimate - processes pension contributions through a single integrated, low cost technology platform.
- Company 2 - 24% below our estimate - attracts senior lawyers into flexible fee arrangements supported by proprietary artificial intelligence tools.
- Company 3 - 35% below our estimate - expands managed infrastructure capital by launching higher margin energy transition investment vehicles.
Three companies from the same screener. Open every one of the 9 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com