


Danieli & C. Officine Meccaniche (BIT:DAN) Wins New Contract And Declares Dividend, Is It A Bargain?
Danieli & C. Officine Meccaniche (BIT:DAN) has drawn fresh attention after announcing an annual dividend and winning a contract to supply advanced rolling mill equipment to Stomana Industry, reinforcing interest in its exposure to higher technology metals equipment.
Recent news has arrived during a tougher period for Danieli & C. Officine Meccaniche, with the 30 day share price return down 13.73% and the 90 day share price return down 27.73%. At the same time, the 3 year total shareholder return stands at 86.85% and the 5 year total shareholder return at 90.79%, which indicates weaker short term momentum following a strong multi year run.
Scan beyond Danieli & C. Officine Meccaniche and compare it with other equipment makers and industrial plays screened for resilient fundamentals using our curated list of solid balance sheet and fundamentals (202 results).
Danieli & C. Officine Meccaniche now combines a weaker recent share price and fresh contract wins with a discounted valuation screen. Do those mixed signals leave more upside for new buyers, or is the easy part already behind it?
Price-to-Earnings of 15.2x: Is it justified?
Danieli & C. Officine Meccaniche closed at €49.00, and on a P/E of 15.2x it screens as cheap compared with both peers and the wider European machinery group. This points to the market pricing in more caution than the headline valuation suggests.
The P/E ratio compares the current share price with the earnings per share. For an engineering group like Danieli & C. Officine Meccaniche, this highlights what investors are willing to pay for each euro of profit given its contract pipeline, cyclicality and capital needs.
Here the multiple sits well below peer benchmarks. Management's P/E of 15.2x is described as good value against the European machinery peer average of 22.1x and also below the estimated fair P/E of 20.7x. This points to a level the market could move towards if sentiment or earnings confidence shifts.
Given both the peer comparison and the fair ratio gap, the stock looks priced more pessimistically than those reference points imply.
Explore the SWS fair ratio for Danieli & C. Officine Meccaniche.
Result: Price-to-Earnings of 15.2x (UNDERVALUED)
Still, Danieli & C. Officine Meccaniche depends heavily on large steel capex cycles and project timing, so any delay or cancellation could quickly challenge that value story.
Find out about the key risks to this Danieli & C. Officine Meccaniche narrative.
Another view on Danieli & C. Officine Meccaniche's value
A second lens on Danieli & C. Officine Meccaniche comes from our DCF model. In this framework, the shares at €49 are compared with an estimated future cash flow value of €69.26, which again suggests a potentially undervalued setup. Does that second indication strengthen the case, or does it simply highlight a higher bar for execution risks?
Look into how the SWS DCF model arrives at its fair value.
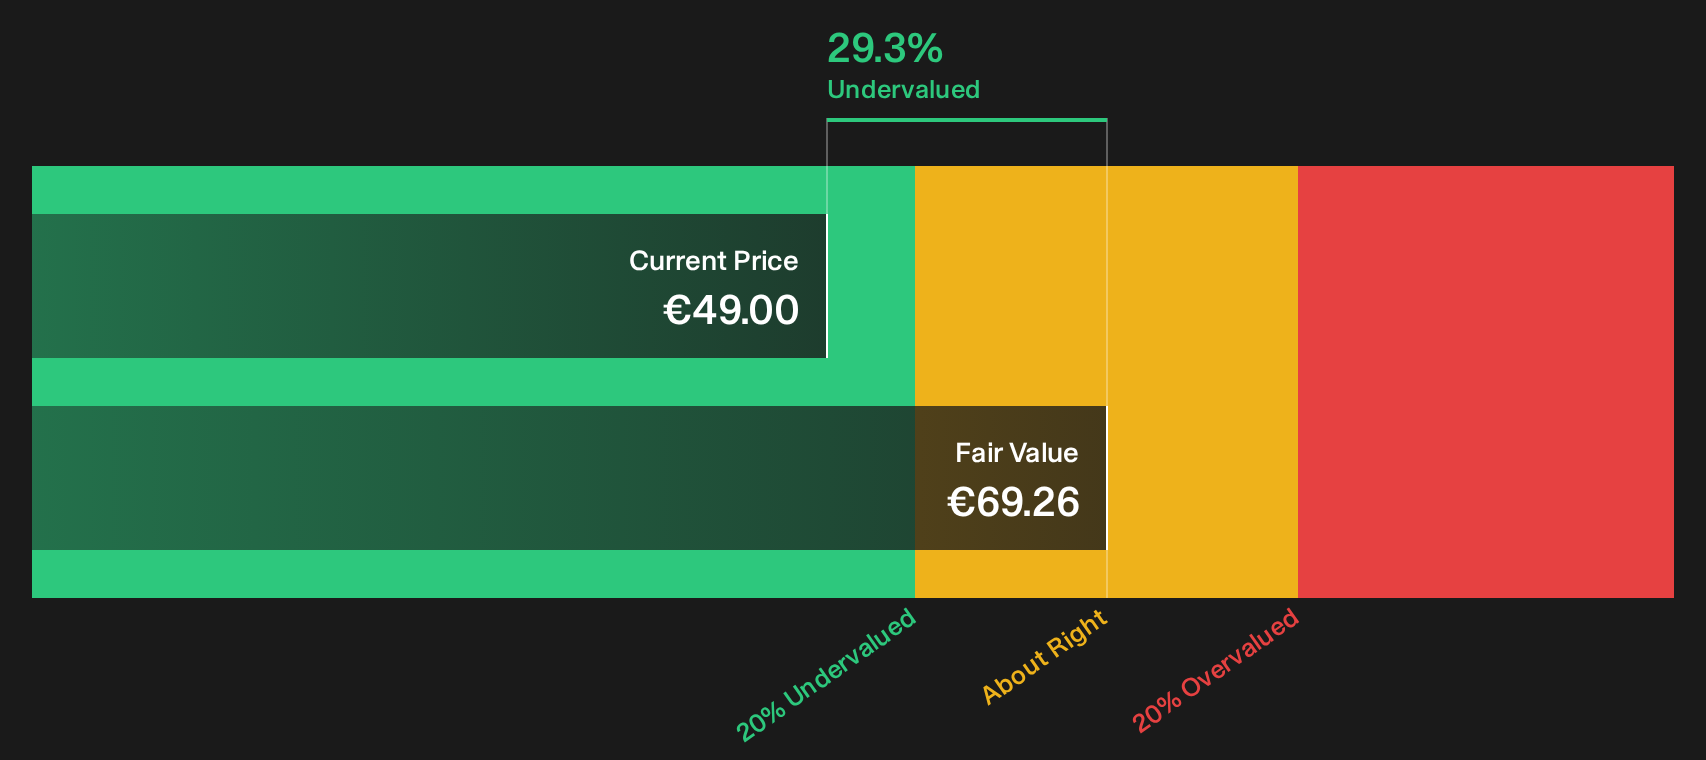
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Danieli & C. Officine Meccaniche for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Danieli & C. Officine Meccaniche's value story, or a second chance setting up in plain sight. If you want to move fast and base your own judgment on more than one headline, start by weighing both the concerns and the potential upside mapped out in the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Danieli & C. Officine Meccaniche?
If Danieli & C. Officine Meccaniche has your attention, do not stop there. A broader shortlist can help you spot opportunities before the crowd.
- Target steady compounding by reviewing companies that combine quality and attractive pricing through the 179 high quality undervalued stocks.
- Strengthen your income toolkit by scanning for payout plays with staying power using the 221 dividend fortresses.
- Prioritise resilience first by filtering for businesses with robust finances in the 224 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com