


Discover Power Solutions International And 2 More Leading Growth Stocks With Insider Ownership
In the last week, the United States market has stayed flat, but it has seen a 15% increase over the past year with earnings projected to grow by 18% per annum in the coming years. In this environment, growth companies with high insider ownership can be particularly appealing as they often indicate strong confidence from those closest to the company and potential alignment of interests with shareholders.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.4% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 13.6% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.4% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
We'll examine a selection from our screener results.
Power Solutions International (PSIX)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Power Solutions International, Inc. designs, engineers, manufactures, markets, and sells engines and power systems globally with a market cap of $1.15 billion.
Operations: The company's revenue primarily comes from its Engineered Integrated Electrical Power Generation Systems segment, which generated $676.19 million.
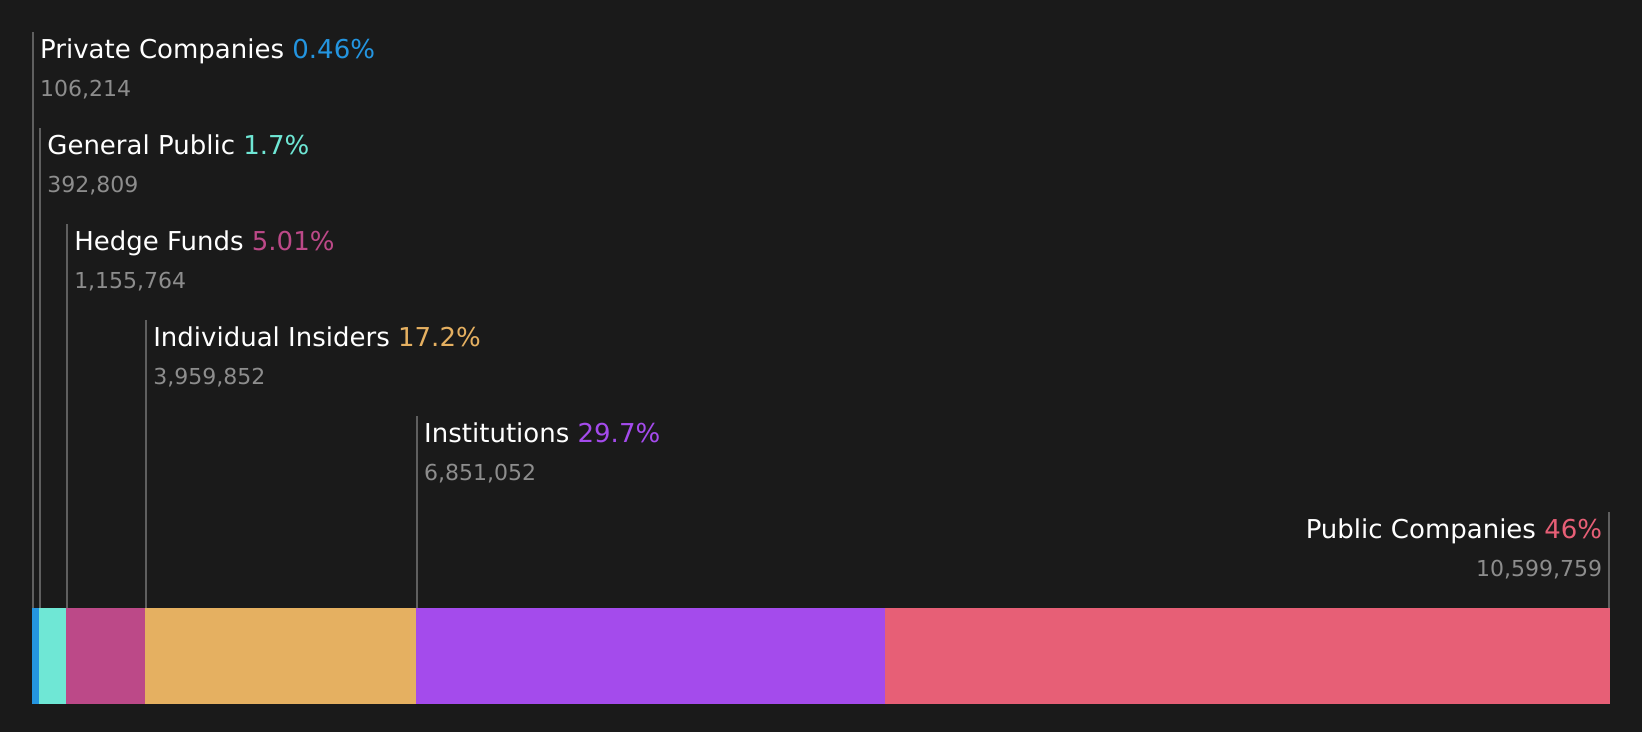
Insider Ownership: 17.2%
Return On Equity Forecast: 34% (2029 estimate)
Power Solutions International exhibits characteristics of a growth company with high insider ownership, driven by forecasted earnings growth of 26.8% annually, outpacing the US market. Despite recent declines in net income and profit margins, the company's strategic initiatives include a new $220 million credit agreement to support expansion. With a Price-To-Earnings ratio below the market average and expected revenue growth faster than the US market at 17.6%, it presents potential value amidst volatility.
- Click here and access our complete growth analysis report to understand the dynamics of Power Solutions International.
- According our valuation report, there's an indication that Power Solutions International's share price might be on the cheaper side.
Oddity Tech (ODD)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Oddity Tech Ltd. is a consumer tech company focused on creating digital-first brands in the beauty and wellness sectors across the United States, Israel, and internationally, with a market cap of approximately $973.69 million.
Operations: The company's revenue is primarily generated from its Personal Products segment, totaling $679.09 million.
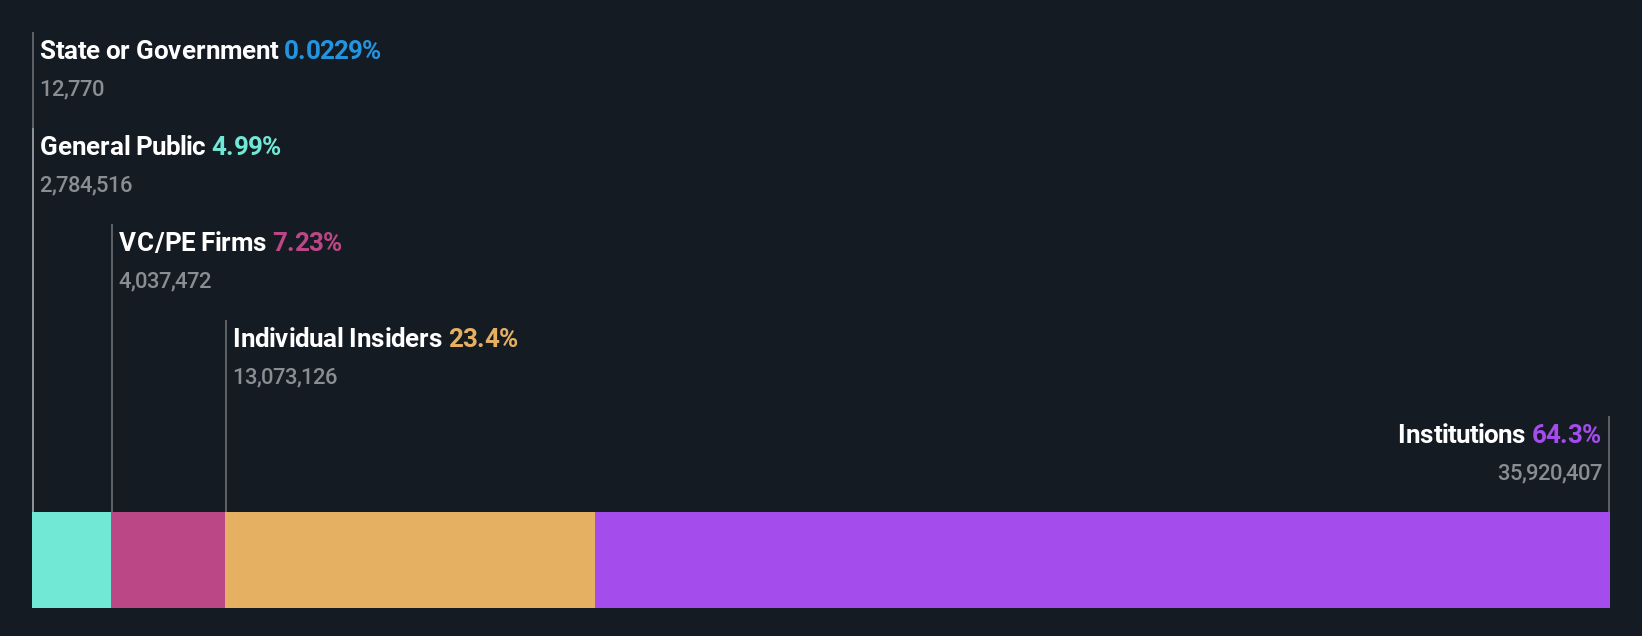
Insider Ownership: 26.7%
Return On Equity Forecast: 29% (2029 estimate)
Oddity Tech shows potential for growth with forecasted earnings expected to rise significantly at 39.3% annually, surpassing the US market. However, recent financial performance reveals challenges, with a notable decline in net income and profit margins. The company has completed a substantial share buyback program worth US$112.3 million but faces volatility and insider selling concerns. Despite trading below fair value estimates, its revenue growth is projected to lag behind the broader market trends.
- Take a closer look at Oddity Tech's potential here in our earnings growth report.
- Our valuation report here indicates Oddity Tech may be overvalued.
Clover Health Investments (CLOV)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Clover Health Investments, Corp. offers Medicare Advantage plans in the United States and has a market cap of $2.54 billion.
Operations: Clover Health Investments generates revenue primarily through its insurance segment, which accounted for $2.48 billion.
Insider Ownership: 21.6%
Return On Equity Forecast: 22% (2029 estimate)
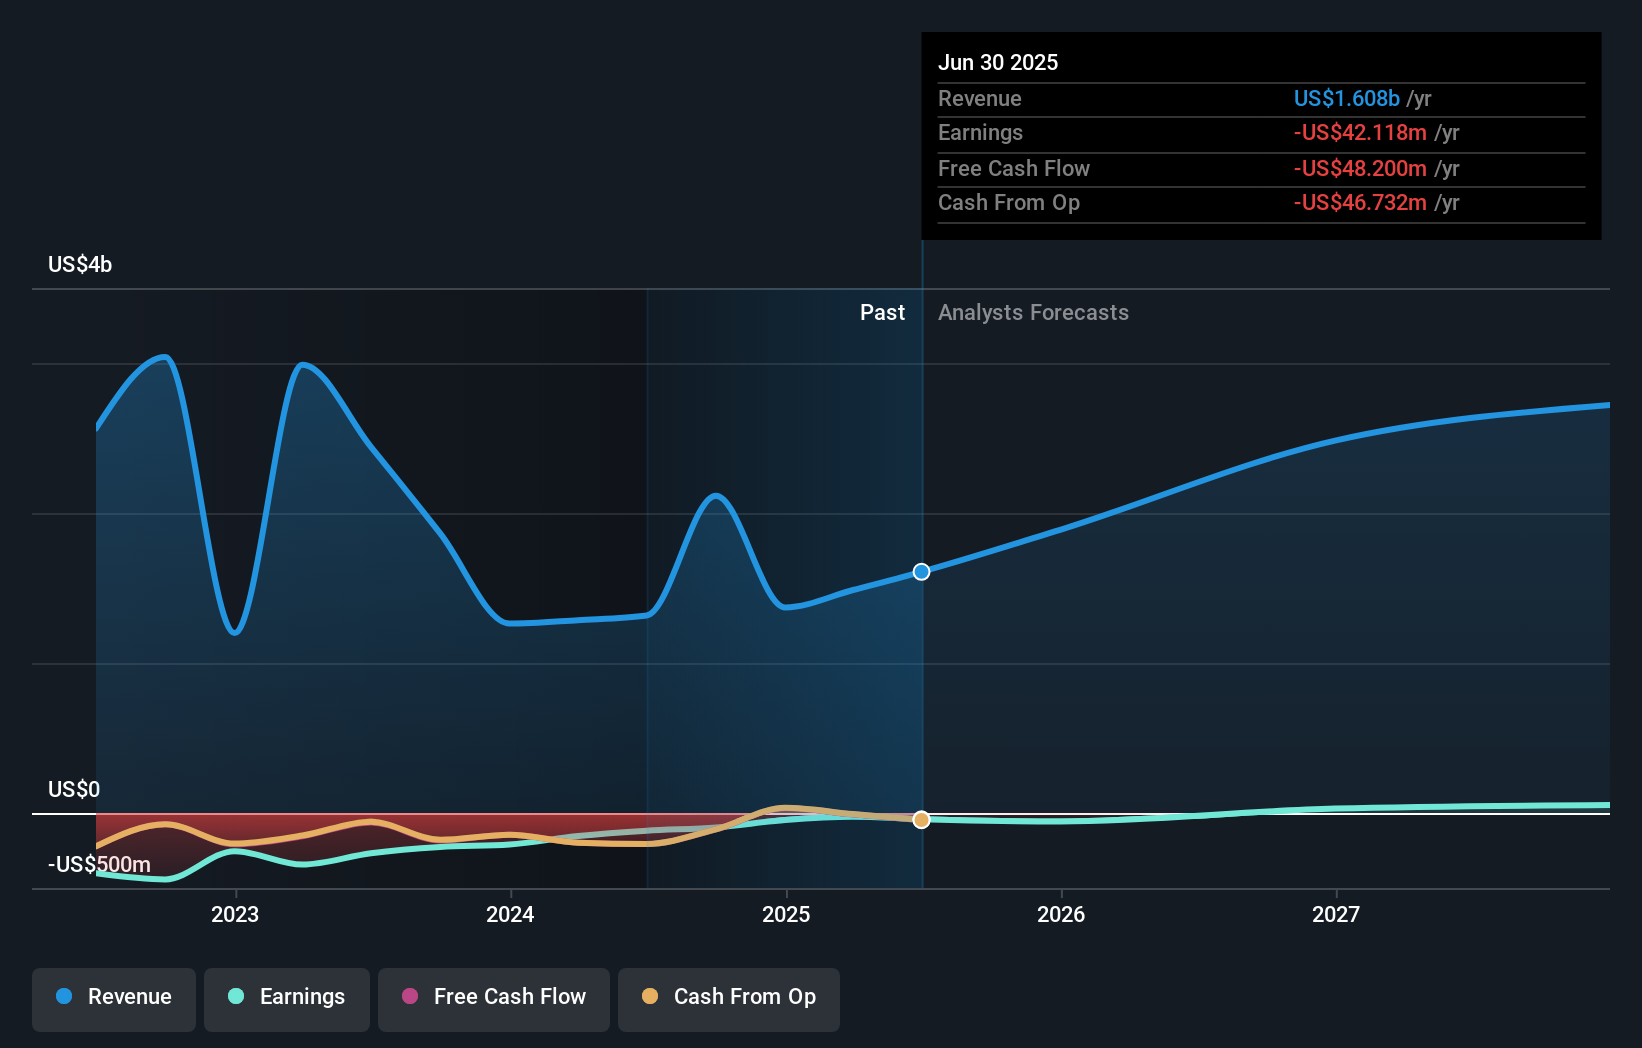
Clover Health Investments is poised for growth with forecasted annual earnings growth of 45.67% and expected profitability within three years. Despite significant insider selling recently, the company trades at a substantial discount to its estimated fair value. Recent strategic board appointments enhance its Medicare Advantage focus, while new product offerings for 2027 emphasize flexibility and affordability in healthcare plans. Revenue rose to US$743.17 million in Q2 2026, reflecting strong financial performance improvements over the previous year.
- Click here to discover the nuances of Clover Health Investments with our detailed analytical future growth report.
- Our comprehensive valuation report raises the possibility that Clover Health Investments is priced lower than what may be justified by its financials.
Summing It All Up
- Explore the 187 names from our Fast Growing US Companies With High Insider Ownership screener here.
- Seeking Other Investments? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com