


Is Semtech (SMTC) A Bargain Following Its Run To $187.30?
Semtech (SMTC) drew fresh attention after a recent price move left the shares around US$187.30. Returns over the past month and past 3 months outpaced the broader semiconductor space.
Semtech’s recent pullback of 2.9% on a 7 day share price return sits against a sharp 12% 1 month share price return and a 32.5% gain over 3 months, while the 1 year total shareholder return of 174% and 3 year total shareholder return of roughly 7x indicate that momentum has been strong and may now be consolidating as investors reassess growth potential and risk after such a rapid move.
Scan how Semtech’s surge compares to other potential breakouts by running the same lens over a hand picked set of 92 AI infrastructure stocks.
After a run that turned a 1 year holding into roughly 2.7 times the original stake, Semtech now forces a harder question. Is the stronger move already in the rearview mirror, or do the current fundamentals still leave clear valuation upside?
Most Popular Narrative: 11% Undervalued
Against Semtech’s last close of $187.30, the most followed narrative pins fair value at about $210.33. This frames the recent surge as only part of the story rather than the end of it.
Accelerating demand from hyperscale data centers and AI infrastructure is driving robust, multi-year growth across Semtech's high-margin data center business, supported by design wins in advanced optical (FiberEdge), low-power (LPO), and active copper interconnects (CopperEdge/ACC). As data rates move from 400G to 800G and 1.6T, Semtech stands to capture significant revenue and margin expansion from new content per deployment.
See why 38 investors see Semtech as 11% undervalued.
Result: Fair Value of $210.33 (UNDERVALUED)
Still, Semtech’s story can change quickly if integration issues persist after the recent goodwill impairment, or if mix shifts toward lower margin IoT offerings drag on profitability.
Find out about the key risks to this Semtech narrative.
Another View: What Multiples Say About Semtech
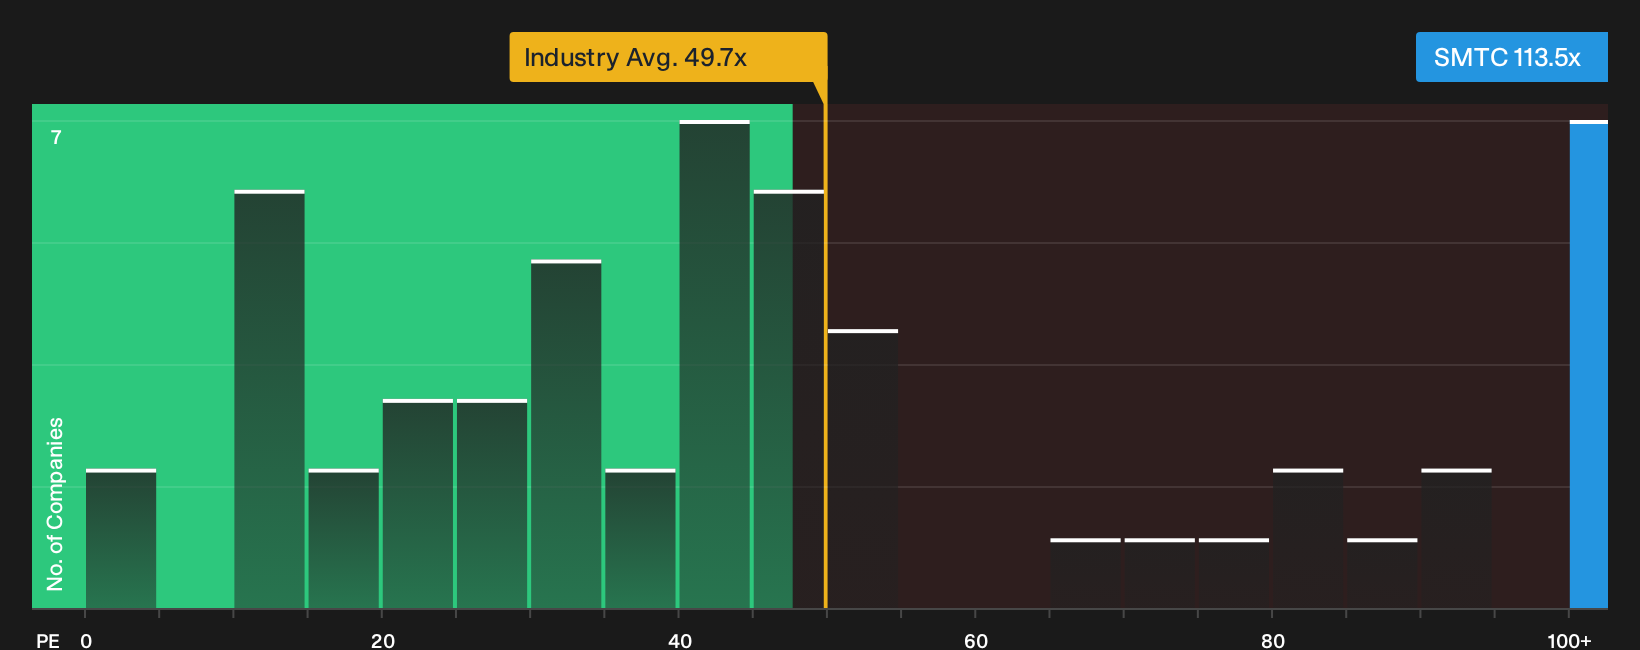
Semtech might screen as undervalued against the $210.33 fair value narrative, but the current P/E of 113.5x tells a different story. That is far above the US Semiconductor industry at 49.7x and the peer average at 63.4x, while the fair ratio sits at 47.8x.
If the P/E moved closer to that fair ratio, a lot of optimism embedded in today’s price would need to compress rather than expand. For an investor weighing fresh capital, the question becomes whether earnings can grow fast enough for this gap to close without the share price doing the heavy lifting.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Semtech attracting both enthusiasm and caution, it makes sense to move fast and consider the full picture for yourself. Start by looking at the balance of 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Semtech?
If Semtech raised your conviction level, do not stop there. Use the screener to pressure test fresh ideas and build a deeper, more resilient watchlist.
- Target dependable compounding by reviewing a curated set of income opportunities through 8 dividend fortresses built for investors who want yield with substance.
- Spot potential mispricing early by scanning a focused pool of quality candidates using 20 high quality undiscovered gems before the crowd pays attention.
- Strengthen portfolio resilience by checking a pre filtered 31 resilient stocks with low risk scores that emphasizes sturdier balance sheets and lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com