


Keurig Dr Pepper Earnings Preview: What to Expect
Keurig Dr Pepper Inc. (KDP) is a leading beverage company headquartered in Frisco, Texas. With a market capitalization of approximately $43.2 billion, the company produces, markets, and distributes a broad portfolio of hot and cold beverages through three main segments: U.S. Refreshment Beverages, U.S. Coffee, and International.
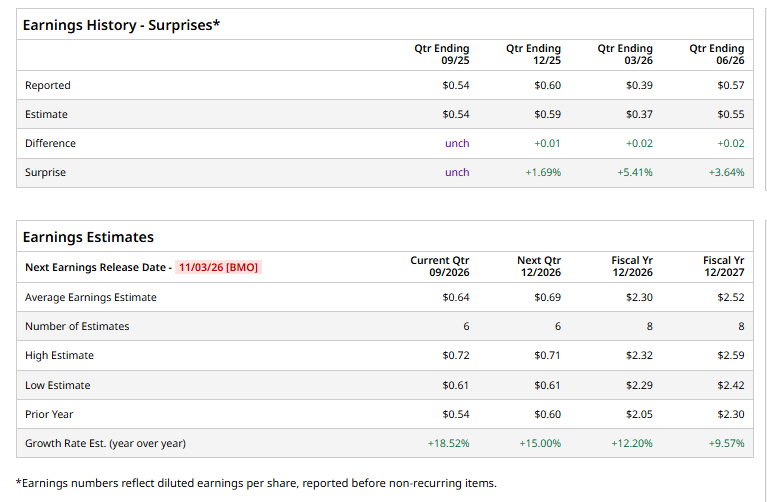
KDP is set to report its Q3 2026 earnings before the market opens on Tuesday, November 3, 2026. Ahead of the release, analysts expect diluted EPS of 64 cents, up 18.5% from 54 cents in the year-ago quarter. Notably, the company has met or exceeded Wall Street’s EPS estimates in each of the past four quarters.
For fiscal 2026, analysts project EPS of $2.30, up 12.2% from $2.05 in fiscal 2025. EPS is expected to increase another 9.6% year over year to $2.52 in fiscal 2027.
KDP stock has risen 22.9% over the past 52 weeks, outpacing both the S&P 500 Index ($SPX), which gained 16%, and the State Street Consumer Staples Select Sector SPDR Fund (XLP), which returned 6.9% over the same period.
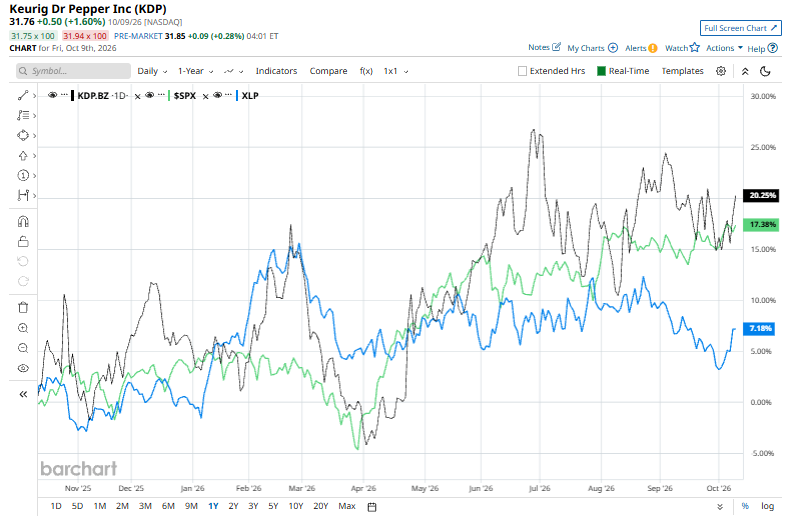
Keurig Dr Pepper has outperformed the broader market, supported by strong U.S. refreshment-beverage growth, better-than-expected adjusted Q2 earnings, and optimism about debt reduction and its planned business separation.
On Sept. 1, KDP announced plans to sell its entire equity stake in Chobani for $800 million and its Allentown, Pennsylvania, manufacturing facility and warehouse for approximately $125 million. The company intends to use the combined $925 million in pre-tax proceeds to reduce debt while expanding its long-term distribution partnership with Chobani, including distribution of La Colombe ready-to-drink lattes and other Chobani-owned beverages. KDP shares rose 2.2% in the next trading session following the announcement.
Analysts are somewhat optimistic about KDP, with the stock carrying a consensus “Moderate Buy” rating. Of the 17 analysts covering the stock, 10 recommend a “Strong Buy,” one recommends a “Moderate Buy,” and six recommend a “Hold.” Meanwhile, the average analyst price target of $36.17 implies potential upside of 13.9% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.