


Swedbank (OM:SWED A), What Is Behind The Fresh Attention?
Executive reshuffle puts Swedbank stock in focus
Swedbank (OM:SWED A) has drawn fresh attention after announcing three senior leadership changes, including shifts in compliance, corporate banking and a permanent appointment to Head of Group Business Support.
Recent trading has been strong, with Swedbank’s share price up 4.1% over the past month and 10% across 90 days, contributing to a 23.9% year to date share price return and a 1 year total shareholder return of 53.8%. Management changes have drawn investor attention.
Compare this executive shake-up at Swedbank with other banks going through leadership or business transitions by reviewing our hand-picked 223 resilient stocks with low risk scores that pair resilient balance sheets with more measured risk profiles.
Swedbank now combines long established banking muscle with a share price that has already run hard this year. After this leadership shake up and strong recent gains, is the current valuation still attractive for new buyers?
Most Popular Narrative: 4% Overvalued
Swedbank closed at SEK403.10, while the most followed narrative suggests a fair value of about SEK385.81. This puts the current price a few percentage points above that anchor and raises questions about how much good news is already reflected in the shares.
Investors appear to be overestimating Swedbank's ability to sustain revenue growth from digital transformation, as recent NII (net interest income) declines and muted mortgage demand in Sweden suggest that accelerated adoption of digital banking and product launches (e.g., Stabelo acquisition) may not immediately translate into higher top-line growth or improved customer retention.
See why 22 investors see Swedbank as 4% overvalued.
Result: Fair Value of SEK385.81 (OVERVALUED)
Still, if Swedbank executes well on digital mortgages and keeps cost discipline tight, stronger efficiencies and loan growth could become a more compelling counterpoint to the current overvaluation narrative.
Find out about the key risks to this Swedbank narrative.
Another view on Swedbank’s value
While analyst models cluster around a fair value of about SEK385.81 and label Swedbank as modestly overvalued, the SWS DCF model points the other way. On that cash flow view, the shares trade well below an estimated value of SEK640.77. This raises a simple question: which set of assumptions do you trust more for the long haul?
Look into how the SWS DCF model arrives at its fair value.
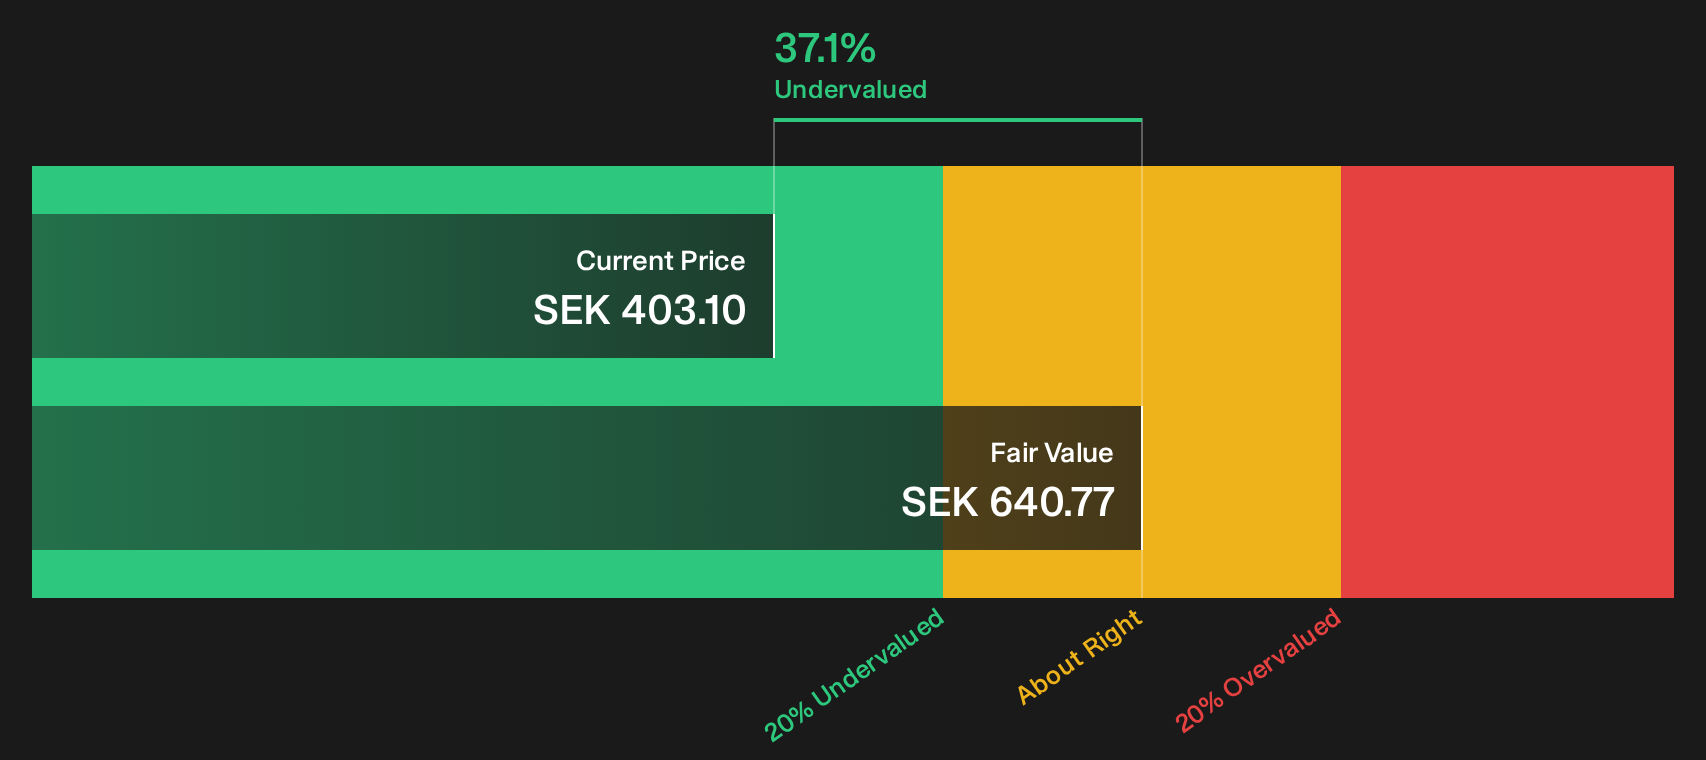
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Swedbank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Swedbank is split, so move quickly from reading to testing the numbers yourself and weigh both the upside and the red flags highlighted in our 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Swedbank?
If Swedbank has sharpened your appetite for better opportunities, do not stop here. Put fresh ideas on your radar before the market moves first.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing prices through the 179 high quality undervalued stocks.
- Seek steadier income streams by focusing on companies built around robust payouts with the 220 dividend fortresses.
- Emphasise resilience by filtering for businesses with cleaner finances and sturdier funding using the list of solid balance sheet and fundamentals (202 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com