


Humana Stock In Focus As Medicare Plans Add Revi Coverage
- BlueWind Medical reported that Humana now covers implantable tibial neuromodulation therapy, including the Revi System, for urgency urinary incontinence across its Medicare Advantage membership. Humana is also rolling out 2027 plans with $0 in-network primary care, labs, and broad dental, vision, and hearing benefits in more than 80% of US counties.
- Humana is using richer Medicare Advantage benefits and access to clinically supported therapies like Revi to compete on value, which may influence membership mix, medical cost profiles, and the effectiveness of its multiyear Medicare Advantage margin restoration program.
- We will look at how Humana's investment narrative is influenced by Medicare Advantage coverage of Revi implant therapy within richer 2027 benefits.
Humana Investment Narrative Recap
To stay invested in Humana, you need to believe the Medicare Advantage margin restoration plan actually translates into cleaner underwriting, tighter cost control, and a healthier mix of higher value plans as those 600,000 lower return products are exited. The short term hinge is execution on bids and benefits without letting medical costs or quality scores undercut that margin target.
The biggest near term risk remains regulatory and coding scrutiny in Medicare Advantage, including Stars related litigation and diagnosis code oversight, which could hit reimbursement and quality bonuses. This latest benefits and coverage news looks directionally supportive of the operating story but not individually transformative for the risk profile.
The Revi coverage decision is the most relevant announcement here because it shows Humana leaning into clinically supported specialty therapies while still talking about predictable costs and benefit standardization. Coverage that cites three year data from BlueWind’s OASIS study ties directly into Humana’s push on clinical quality and medication adherence campaigns as levers for medical margins.
For investors tracking catalysts, this kind of benefit design matters less as a volume story and more as an execution proof point alongside AI enabled service, CenterWell expansion, and disciplined 2027 bidding. It sits next to the plan exits as a reminder that Humana is trying to upgrade its member mix and care model while staying inside tighter regulatory guardrails.
Humana's current analyst story assumes revenues reach US$185.9b and earnings hit US$3.4b by 2029, based on 8.5% yearly revenue growth and an earnings increase of about US$2.1b from earnings today of roughly US$1.3b.
Uncover why Humana's fair value is essentially in line with its current price.
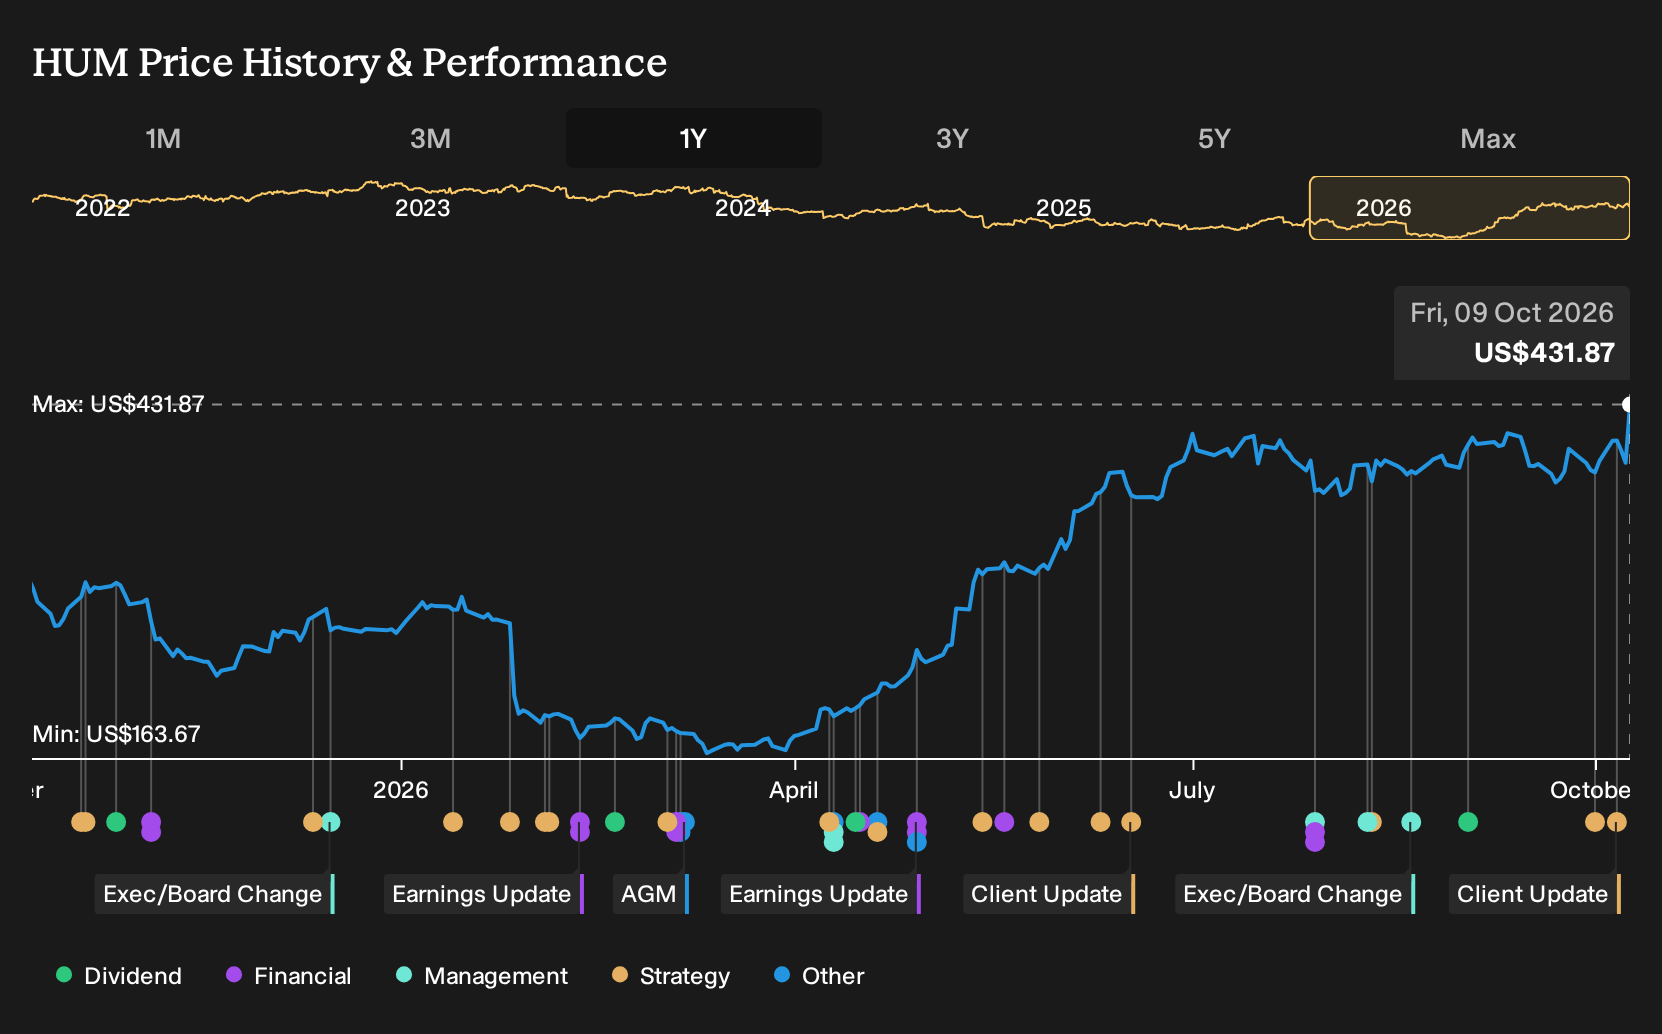
Exploring Other Perspectives
One alternate angle focuses on drug cost pressure rather than richer benefits. The most cautious analysts were modeling only 5.8% yearly revenue growth and about US$2.6b of earnings by 2029, compared with consensus at US$3.4b. Those views came before this Humana news, so you may see forecasts shift as people reassess the trade off between advanced therapies and tighter bids.
Explore 5 other Humana fair value estimates, including one that suggests as much as 51% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Humana research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Humana. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Humana's overall financial health at a glance.
Looking for more investment ideas beyond Humana?
If the Humana story has you thinking about where else disciplined benefits design and balance sheet strength could matter, it can help to widen your watchlist with a few focused filters from the Simply Wall St Screener.
- For investors who care most about resilience and capital protection, start with a 31 resilient stocks with low risk scores that may better fit a steadier risk profile.
- If quality at a reasonable entry price is your priority, use the 29 high quality undervalued stocks to see which businesses combine fundamentals with potentially appealing valuations.
- Income seekers who want yield without ignoring balance sheet discipline can turn to a 8 dividend fortresses that screens for payout strength and durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com