


China Mobile (SEHK:941) Stock Looks Fairly Valued Against Its Earnings Power
China Mobile has delivered a powerful long term share price run, which naturally puts the spotlight on whether the current valuation still lines up with the earnings that support it. With the stock now trading around HK$80.10, the key issue is how much of its profit profile is already reflected in that figure.
- Over the past 5 years, China Mobile has returned about 134.6%, which raises the question of how much further its earnings power can justify investor expectations.
- The business leans on a large, recurring telecom customer base and heavy network investment, which can shape both the durability of its profit stream and the cash it has available for payouts or reinvestment.
- The analysts covering China Mobile have run their own numbers. See what analysts think China Mobile's shares could be worth.
For investors, the debate is whether China Mobile's current share price is adequately supported by the earnings the company is generating today.
If you are weighing whether China Mobile's HK$80.10 share price lines up with its earnings, it can help to compare it with a wider set of companies screened for 179 high quality undervalued stocks.
Where Does China Mobile Sit on Earnings?
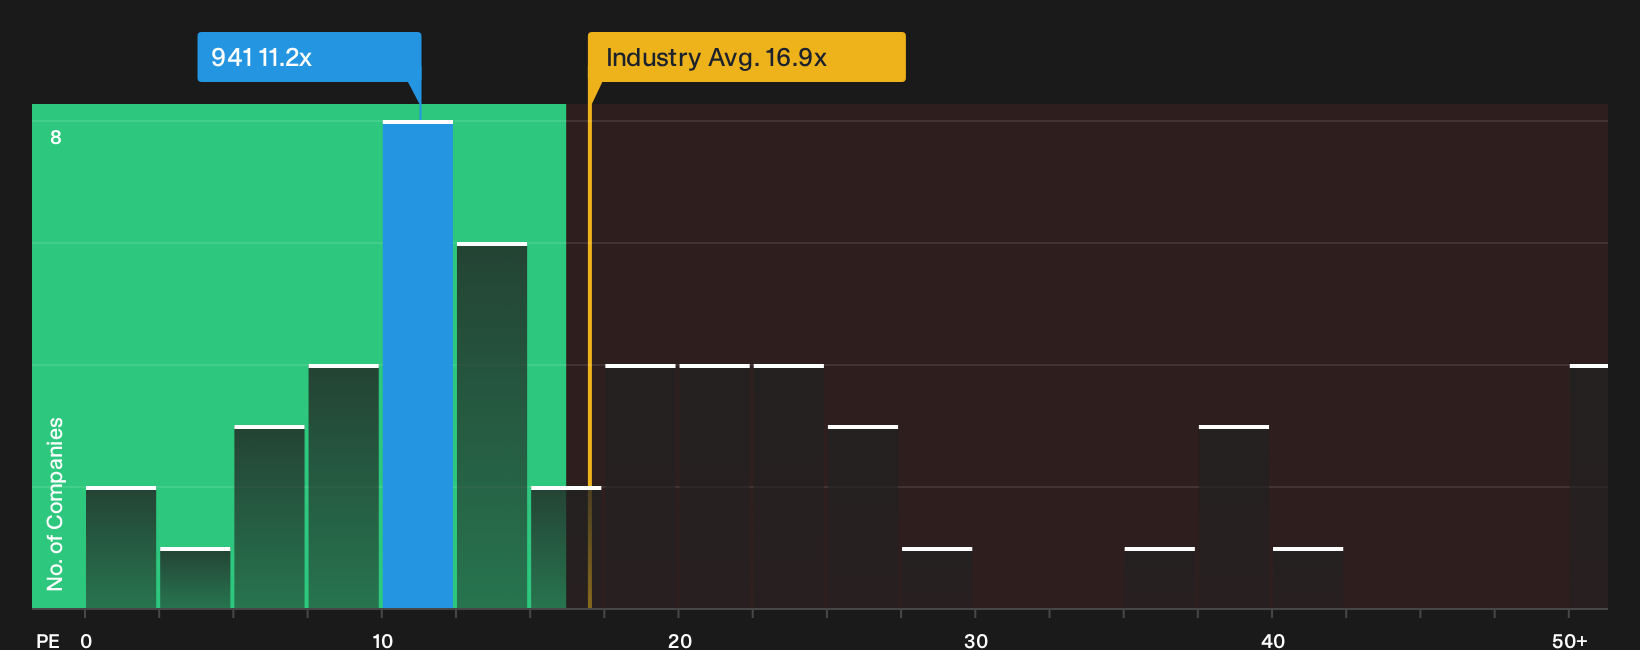
The P/E ratio suits China Mobile because earnings remain a key anchor for how investors value a mature telecom operator. At around 11.2x earnings, the stock trades below the Wireless Telecom industry average of about 14.9x and also below the broader peer group at roughly 22.8x. That kind of gap indicates the market is putting a lower price on each unit of China Mobile's profit than on many comparable operators.
The valuation model that blends the company’s growth profile, margins, scale and risk suggests a P/E that is close to where the shares trade today, so the current 11.2x sits near that tailored reference point rather than at a clear discount or premium. For you as a shareholder or potential buyer, the key question is whether China Mobile's earnings quality and cash generation justify the market assigning this level of multiple or something different over time. Explore the numbers behind China Mobile's P/E valuation.
The China Mobile Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion for China Mobile leaves off by spelling out which growth, margin and earnings paths would need to play out for the share price to sit meaningfully above or below where it trades today on the Community page. Rather than leaving you with a single ratio or model output, they unpack the future that number assumes so you can watch how closely reality matches it over time.
One of the top community narratives on China Mobile: 33% undervalued
"Emerging segments (cloud, AI, computing) are becoming the primary drivers of long-term value creation for China Mobile…"
Discover why this Narrative puts China Mobile at 33% undervalued.
China Mobile's valuation still leaves one crucial piece of the puzzle unresolved
Price and earnings only tell part of the story, because the people steering China Mobile and the way their pay is structured can heavily influence how that story unfolds for shareholders. See who runs China Mobile and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com