


Data#3 (ASX:DTL) AI And Cloud Push Keeps Valuation Debate Alive
Recent attention on Data#3 (ASX:DTL) centres on its push into Microsoft 365 Copilot deployments, AI analytics, and managed cloud services, as customers lock into multi-year subscription and as-a-service contracts that reshape its revenue profile.
That momentum in AI projects is lining up with sharp share price strength, with Data#3’s stock delivering a 30 day share price return of 32.47% and a year to date share price return of 53.43%, while the 5 year total shareholder return of 207.11% points to long running confidence in the story.
Scan beyond Data#3 and line up other AI and cloud beneficiaries by running your filters against our hand picked 92 AI infrastructure stocks.
Bulls point to Data#3’s AI push and recurring contracts, while bears highlight a share price that has sprinted ahead. Which side does the current valuation evidence support next?
Most Popular Narrative: 27% Overvalued
Against the most followed fair value narrative of A$10.95, Data#3’s last close at A$13.87 prices the business well above that estimate and puts the spotlight on whether the current AI enthusiasm justifies the gap.
The accelerating shift by customers to multiyear subscription and as-a-service models (evidenced by recurring revenue increasing to 69% and rapid expansion in Device-as-a-Service), positions Data#3 for higher, more stable, and predictable revenue and margin growth over time as the mix continues to improve. Enterprise and government digital transformation is driving robust demand for IT infrastructure upgrades, devices, cloud integration, and AI deployment in areas where Data#3 consistently grows ahead of the market, supported by record device refresh cycles and increasing public and education sector spend, boosting topline revenue and gross profit.
See why 45 investors see Data#3 as 27% overvalued.
Result: Fair Value of A$10.95 (OVERVALUED)
Still, the whole Data#3 narrative leans on a few pressure points, including reliance on Microsoft incentives and rising IT wage costs that could squeeze profitability.
Find out about the key risks to this Data#3 narrative.
Another View: Data#3 Through the Cash Flow Lens
The analyst narrative leans on a fair value of A$10.95 and calls Data#3 overvalued at A$13.87. Our DCF model tells a different story, with a future cash flow value of A$14.23 per share, which implies the stock trades about 2.5% below that estimate. Which signal do you trust more: the earnings multiple or the cash flow math?
For investors who want to see how that cash flow estimate is built line by line, the SWS DCF model is laid out in full detail in the valuation workup, including key assumptions and sensitivities, so you can judge how robust it feels for your own process Look into how the SWS DCF model arrives at its fair value..
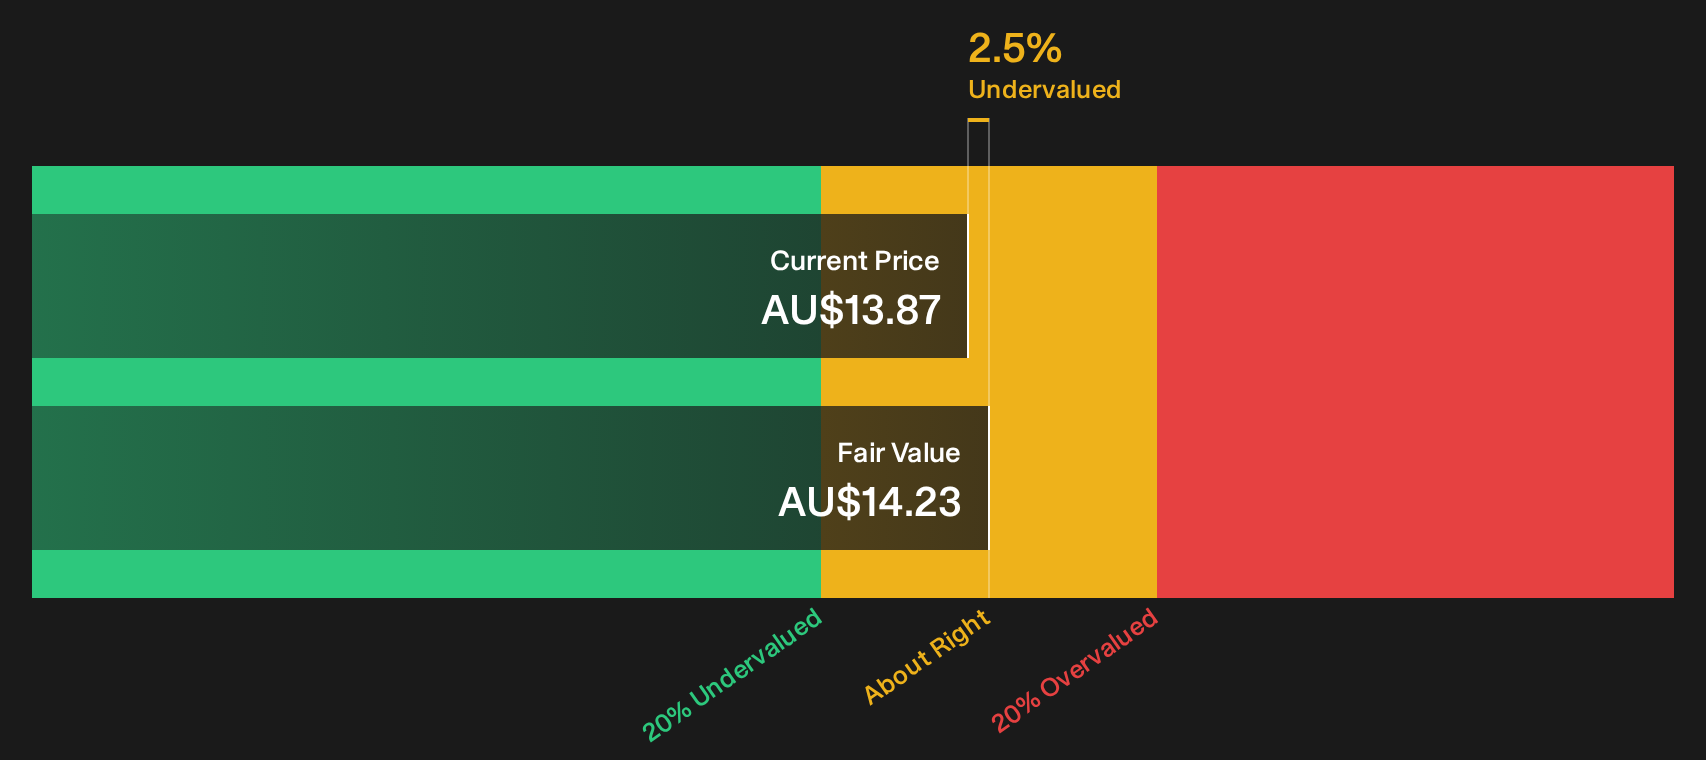
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Data#3 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings about Data#3 after all that? Act fast on your curiosity, consider both the potential benefits and the pressure points, and explore the full breakdown of 3 key rewards and 1 important warning sign
Looking for more ideas beyond Data#3?
If Data#3 has you thinking differently about your portfolio, do not stop here. Broaden your opportunity set and let fresh ideas challenge your current holdings.
- Target potential mispricings by running our 4 high quality undervalued stocks and see which quality companies the market might be overlooking today.
- Strengthen your income stream with the 6 dividend fortresses and focus on businesses offering higher yields with staying power.
- Dial down portfolio risk by screening through the 7 resilient stocks with low risk scores and concentrating on companies with more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com