


Fermi (FRMI) Stock Looks Fully Priced Following Its Texas Power Deal
Fermi has seen its share price fall hard over the past year, and that slump is pushing investors to ask whether the current US$3.43 price still makes sense when set against the company’s book value. With the business still in development mode, book-based valuation is front and center for anyone trying to work out what this stock really represents today.
- The share price has fallen 88.2% over the past year, which puts the spotlight on whether the balance sheet can still anchor a sensible valuation.
- The agreement with NAES to operate Fermi’s Texas natural gas turbines and the first data center lease with TensorWave may support future asset utilization, funding needs, and how much weight you place on the company’s current equity base.
- Your read on Fermi is one view; the desks covering it have another. See what analysts think Fermi's shares could be worth.
The issue now is whether the current market price for Fermi can be squared with its book value when compared with the industry average.
If you want to test the same book value question across a broader set of real asset plays, take a look at 43 power grid technology and infrastructure stocks.
Has Fermi Run Too Far on Book Value?
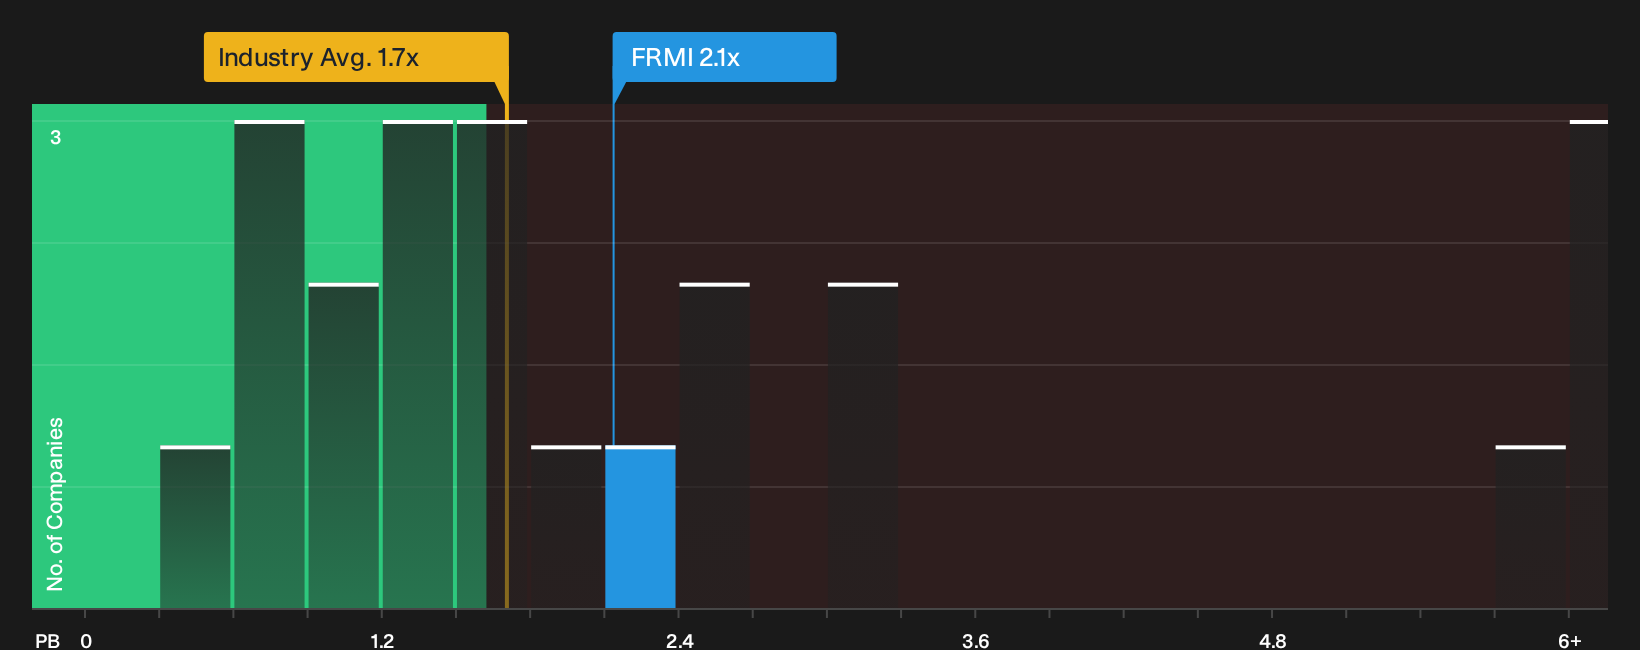
P/B is a useful starting point for Fermi because investors are mainly weighing the value of its physical assets against the current share price. At roughly 2.1x book value, the stock trades above the Specialized REITs industry average of about 1.7x, so you are paying a higher price for each dollar of net assets than the sector as a whole.
Compared with a peer average P/B of roughly 3.1x, Fermi screens as cheaper than many listed comparables on this metric, yet still overvalued relative to the broader industry benchmark. Because the NAES operating agreement and the TensorWave data center lease outline a path to using those assets more fully, the market appears willing to assign a premium over the sector, even while other REITs offer lower P/B entry points. That leaves the current multiple suggesting an overvalued share price on book terms, with the gap reflecting investors’ willingness to pay more for Fermi’s specific asset profile. Explore the numbers behind Fermi's P/B valuation.
The Fermi Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St give you a way to connect Fermi's current P/B premium with clear assumptions about future growth, profitability and earnings power that would need to hold for the stock to trade meaningfully higher or lower than today. Each scenario ties a single fair-value anchor to a specific mix of potential catalysts and risks, which lets you track over time whether the real world is moving closer to or further from that particular storyline.
One of the top community narratives on Fermi: 80% undervalued
"Rising power needs from artificial intelligence workloads are pushing large tenants to seek long duration, dedicated power solutions…"
Discover why this Narrative puts Fermi at 80% undervalued.
One more Fermi check that belongs next to the book value math
Price versus assets only tells part of the story for Fermi, because the research also flags specific pressure points inside the business that investors may want to weigh before relying on today’s valuation anchor. Take a closer look at 3 warning signs (3 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com