


B.F (BIT:BFG) Is Back In The Spotlight, But What Is Driving Attention?
B.F (BIT:BFG) drew investor attention after reporting half year 2026 earnings, with higher sales, revenue and net income, which coincided with strong recent share price momentum.
The fresh half year figures arrived after a powerful run in B.F’s share price, with a 30 day share price return of 23.76% and a 90 day gain of 53.06%. Meanwhile, the 1 year total shareholder return of 79.51% signals momentum that stretches well beyond this latest earnings release.
Scan how B.F’s surge compares with other agro and consumer staples plays by reviewing the curated 617 high quality undiscovered gems that pair strong fundamentals with under-the-radar momentum.
B.F’s surge puts you at a crossroads. You can step in after a 53.06% 90 day jump, or wait and see what the current valuation really builds in.
Preferred Multiple of 1x Price-to-Sales: Is it justified?
Valuation on B.F has two conflicting signals right now. The stock screens as good value against listed peers on its P/S ratio, yet screens as expensive when lined up against an estimated fair level and a wider European benchmark.
The preferred metric here is the price-to-sales ratio, which compares the €7.5 share price to the revenue B.F generates per share. For an agro industrial group that markets everything from pasta and rice to frozen vegetables and fertilizers, investors often look at P/S because earnings can swing more sharply than sales while still reflecting the scale of the underlying franchise.
Against direct peers, B.F trades on a P/S of 1x compared with a peer average of 1.9x. That is described as good value, which suggests the market is applying a lower price tag to each euro of sales than similar Italian food businesses. At the same time, the estimated fair P/S ratio is flagged at 0.6x and the wider European Food industry average sits at 0.8x, which both imply a lower level that prices could gravitate toward if sentiment cools or growth expectations ease.
Explore the SWS fair ratio for B.F.
Result: Price-to-Sales of 1x (OVERVALUED).
Still, the B.F story could change quickly if recent share price gains reverse or if revenue growth of 0.20% indicates slower momentum ahead.
Find out about the key risks to this B.F narrative.
Another View on B.F’s Valuation
The SWS DCF model paints a very different picture for B.F. At a share price of €7.5, the stock is described as trading above an estimated future cash flow value of €0.76, which signals a very large premium. That kind of gap raises a simple question for you: Is the market paying too much for growth that may already be in the price?
Look into how the SWS DCF model arrives at its fair value.
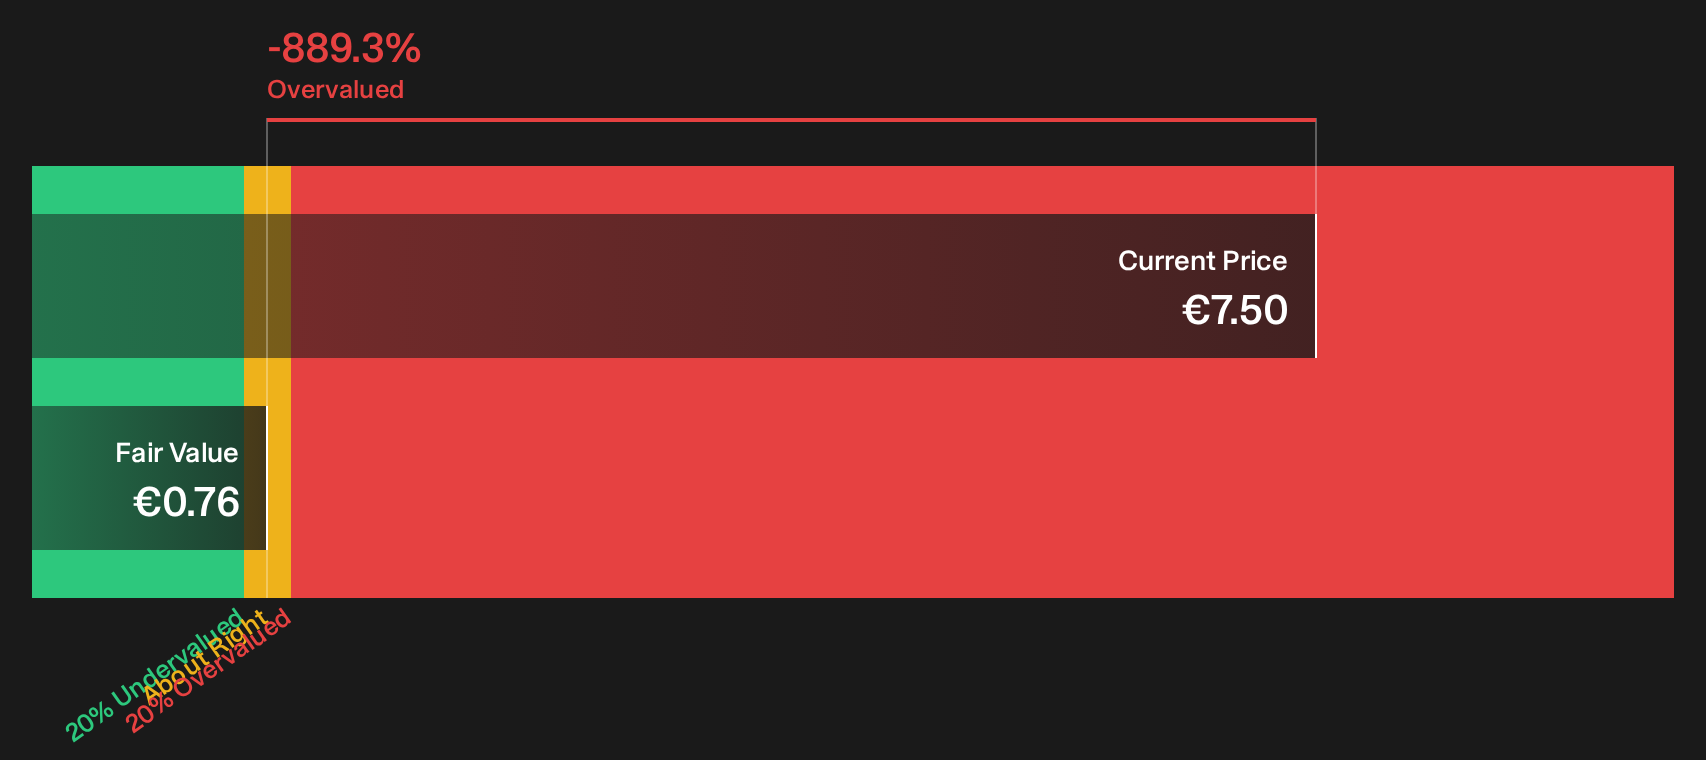
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out B.F for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around B.F leave you undecided, treat that hesitation as your cue to move fast and test the numbers yourself. Balance the upside story against the caution flags by unpacking the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond B.F?
You do not need to stop with B.F. Use this earnings reaction as a springboard to scan other opportunities that better fit your risk, income, and value targets.
- Target potential mispricing by reviewing companies trading on compelling valuations through the 179 high quality undervalued stocks.
- Strengthen income potential by focusing on businesses with steady yields using the 221 dividend fortresses.
- Reduce portfolio shocks by concentrating on resilient balance sheets via the 222 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com