


FactSet Research Systems (FDS) Expands With Scotia And SUBSCRIBE As Fair Value Debate Deepens
FactSet Research Systems (FDS) just widened its reach in wealth management, expanding its partnership with Scotia Wealth Management and adding a new SUBSCRIBE alliance that brings private markets workflows directly into its existing platform.
These Scotia and SUBSCRIBE deals arrive as FactSet Research Systems enjoys a short burst of momentum, with a 30-day share price return of 10.58% and a 90-day gain of 9.15%. However, a 3-year total shareholder return that declined 33.29% signals a longer reset still weighing on the story.
Scan how FactSet Research Systems compares with other workflow driven platforms by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) before you go any further in your research.
FactSet Research Systems now sits in an awkward middle ground, with a sharp short term rebound set against a tougher multi year return record. Has the recent rally already harvested most of the upside, or does valuation still leave meaningful room?
Most Popular Narrative: 11% Overvalued
On Simply Wall St, the most followed narrative currently pegs FactSet Research Systems at a fair value of $258.69 versus a last close of $287.18. This frames the recent bounce as slightly ahead of that anchor according to LunaRodas.
The Google Cloud partnership was announced on the July call, described across three specific workstreams: workstation enhancement through Gemini capabilities, FactSet intelligence into Gemini Enterprise, and new agents built on the Google enterprise agent platform. Preferential token pricing was named as a commercial benefit.
This morning contains no reference to it.
See why 1 investors see FactSet Research Systems as 11% overvalued.
Result: Fair Value of $258.69 (OVERVALUED)
Still, the FactSet Research Systems story depends on management rebuilding credibility around AI partnerships and on consumption pricing not eroding the link between ASV and actual revenue.
Find out about the key risks to this FactSet Research Systems narrative.
Another View: DCF Points In The Opposite Direction
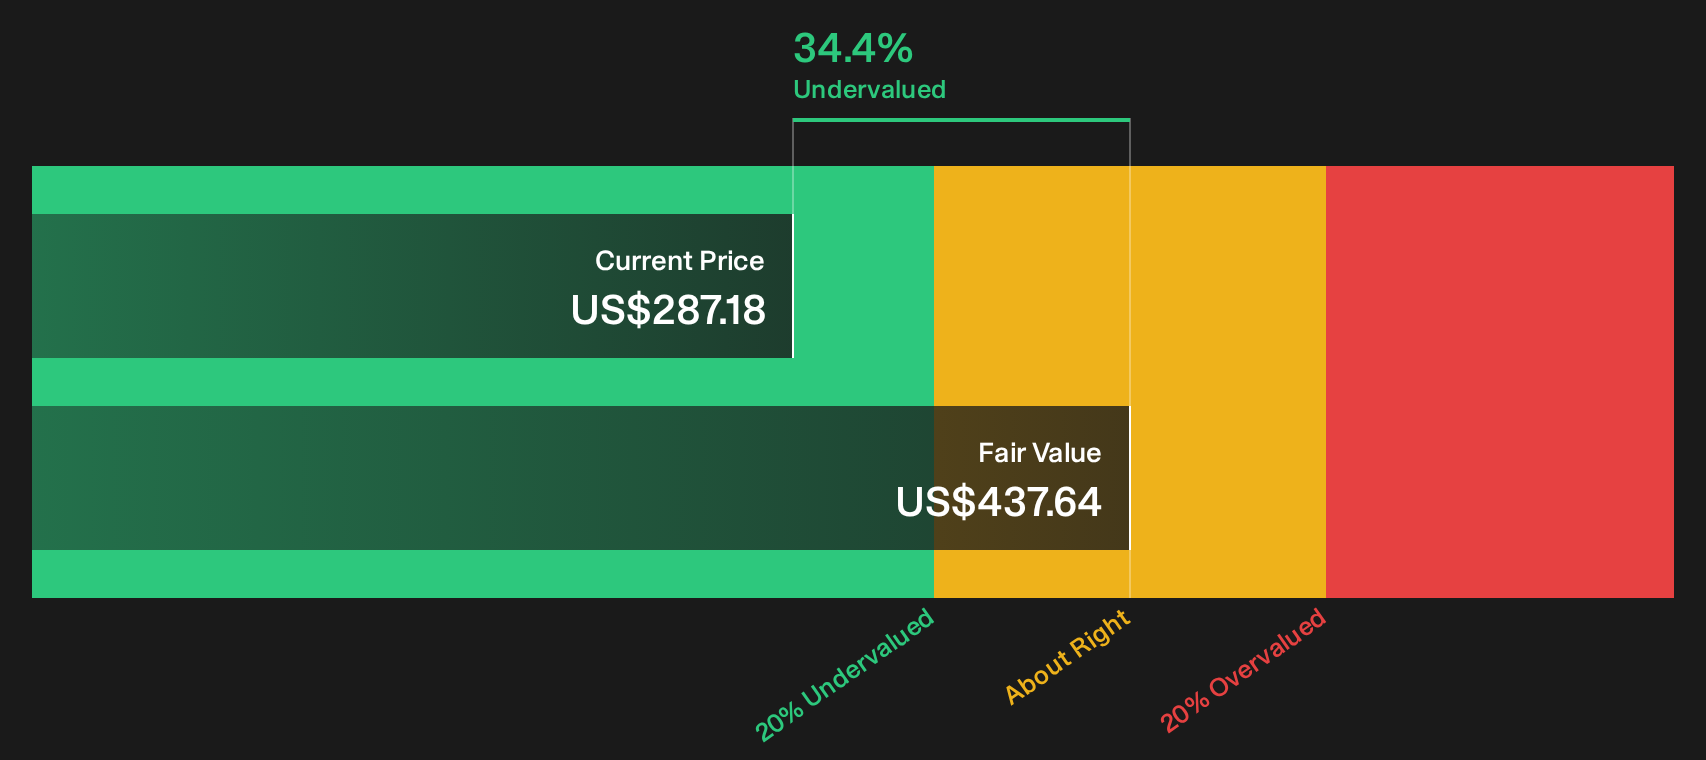
While the Simply Wall St narrative tags FactSet Research Systems as 11% overvalued at $287.18 versus a $258.69 fair value, the SWS DCF model lands in a very different place. It estimates future cash flow value at $437.64, which frames the same share price as materially undervalued. Which lens do you trust more when both are using the same underlying business but different assumptions?
Look into how the SWS DCF model arrives at its fair value, then decide which framework better matches your own expectations for cash generation and risk, before you act on either signal. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on FactSet Research Systems so far, right, with both risks and rewards in play. You probably want to move fast and test the numbers yourself, then pressure test your own thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FactSet Research Systems?
If FactSet Research Systems has sharpened your focus, do not stop here. Broaden your watchlist now so fresh opportunities do not slip past you.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that filters for financial strength in a single view.
- Hunt for quality at a potentially attractive entry point by reviewing the 29 high quality undervalued stocks that filters for strong fundamentals at prices that may lag underlying metrics.
- Prioritise stability and downside control by running through the 31 resilient stocks with low risk scores focused on companies with lower overall risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com