


Asian Stocks Possibly Trading Below Their Intrinsic Value Estimates In October 2026
In October 2026, Asian markets are navigating a complex landscape marked by fluctuating oil prices due to Middle East tensions and shifting interest rate expectations as central banks respond to persistent inflation pressures. Amidst this volatility, identifying stocks that may be trading below their intrinsic value can offer investors opportunities for potential long-term gains. In such an environment, a good stock is often characterized by robust fundamentals and resilience against macroeconomic uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Woori Financial Group (KOSE:A316140) | ₩32350.00 | ₩64511.90 | 49.9% |
| Shinhan Financial Group (KOSE:A055550) | ₩99500.00 | ₩195773.64 | 49.2% |
| Nissui (TSE:1332) | ¥1085.00 | ¥2155.77 | 49.7% |
| Monde Nissin (PSE:MONDE) | ₱6.40 | ₱12.68 | 49.5% |
| Kumagai GumiLtd (TSE:1861) | ¥1196.00 | ¥2370.12 | 49.5% |
| Innocean Worldwide (KOSE:A214320) | ₩17980.00 | ₩35756.38 | 49.7% |
| Double Medical Technology (SZSE:002901) | CN¥40.08 | CN¥79.00 | 49.3% |
| Chow Sang Sang Holdings International (SEHK:116) | HK$13.84 | HK$27.60 | 49.9% |
| Astellas Pharma (TSE:4503) | ¥2247.50 | ¥4494.42 | 50% |
| APAC Realty (SGX:CLN) | SGD0.52 | SGD1.04 | 49.8% |
Let's take a closer look at a couple of our picks from the screened companies.
Chow Sang Sang Holdings International (SEHK:116)
Overview: Chow Sang Sang Holdings International Limited is an investment holding company that manufactures and retails jewellery across Mainland China, Hong Kong, Macau, and Taiwan with a market cap of HK$9.30 billion.
Operations: The company's revenue primarily comes from the retail of jewellery and watches, generating HK$23.61 billion, followed by the wholesale of precious metals at HK$658 million and trading of LGD products at HK$6.12 million.
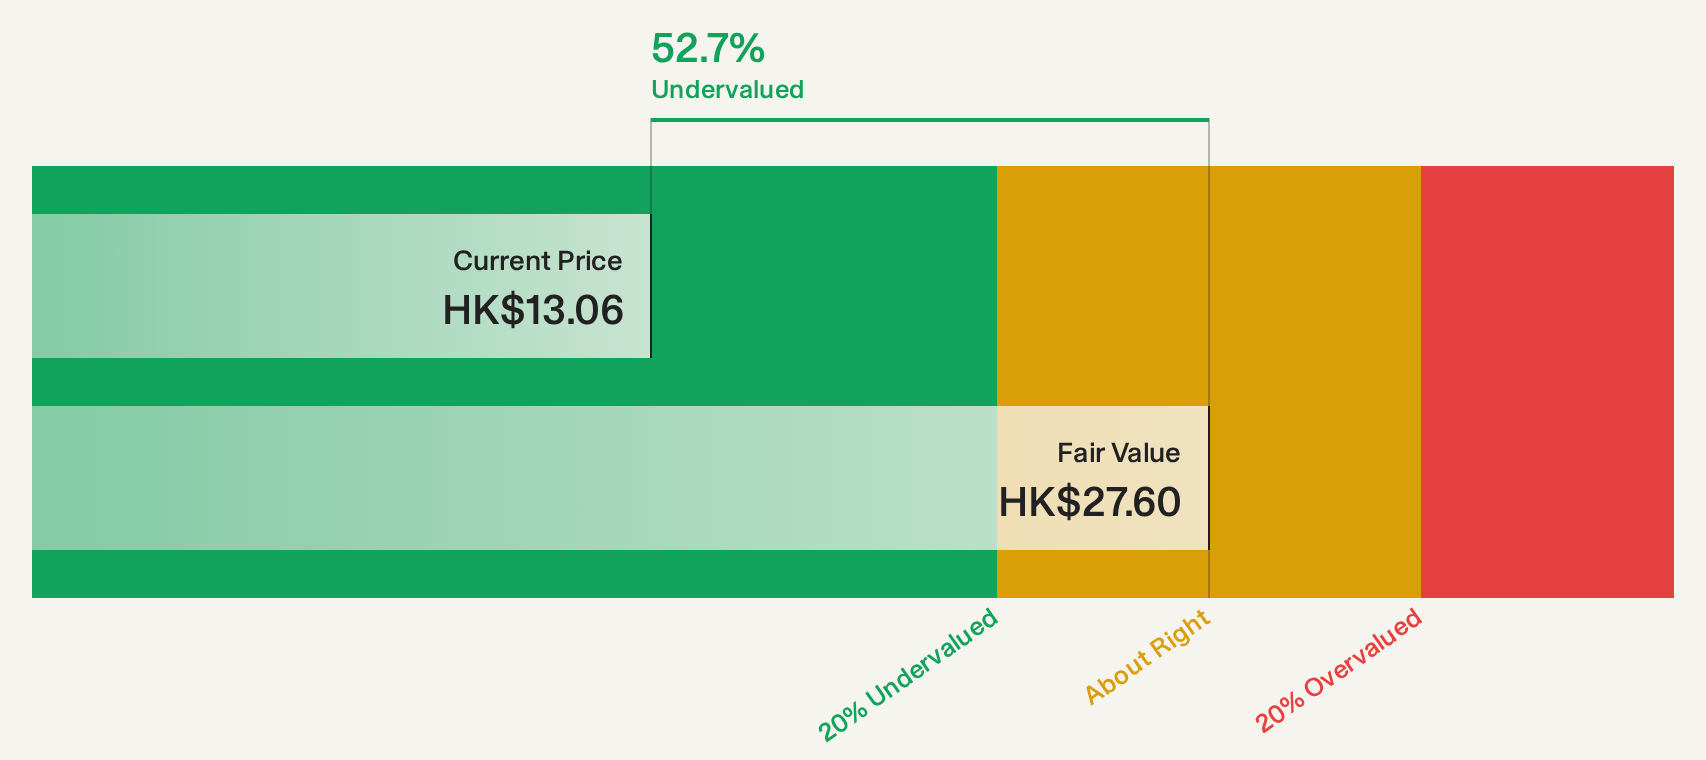
Estimated Discount To Fair Value: 49.9%
Chow Sang Sang Holdings International appears undervalued based on discounted cash flow analysis, trading at HK$13.84, significantly below the estimated future cash flow value of HK$27.6. Despite a substantial 149.3% earnings growth in the past year and improved sales performance, forecasts indicate a 9% annual decline in earnings over the next three years and slower revenue growth compared to the Hong Kong market. The company's dividend track record is unstable despite recent increases.
- In light of our recent growth report, it seems possible that Chow Sang Sang Holdings International's financial performance will exceed current levels.
- Dive into the specifics of Chow Sang Sang Holdings International here with our thorough financial health report.
Yadea Group Holdings (SEHK:1585)
Overview: Yadea Group Holdings Ltd. is an investment holding company that develops, manufactures, and sells electric two-wheeled vehicles and related accessories under the Yadea brand in China, with a market cap of approximately HK$27.40 billion.
Operations: The company generates revenue primarily from electric two-wheeled vehicles and related accessories, totaling CN¥34.07 billion, and batteries and electric drives, amounting to CN¥7.66 billion.
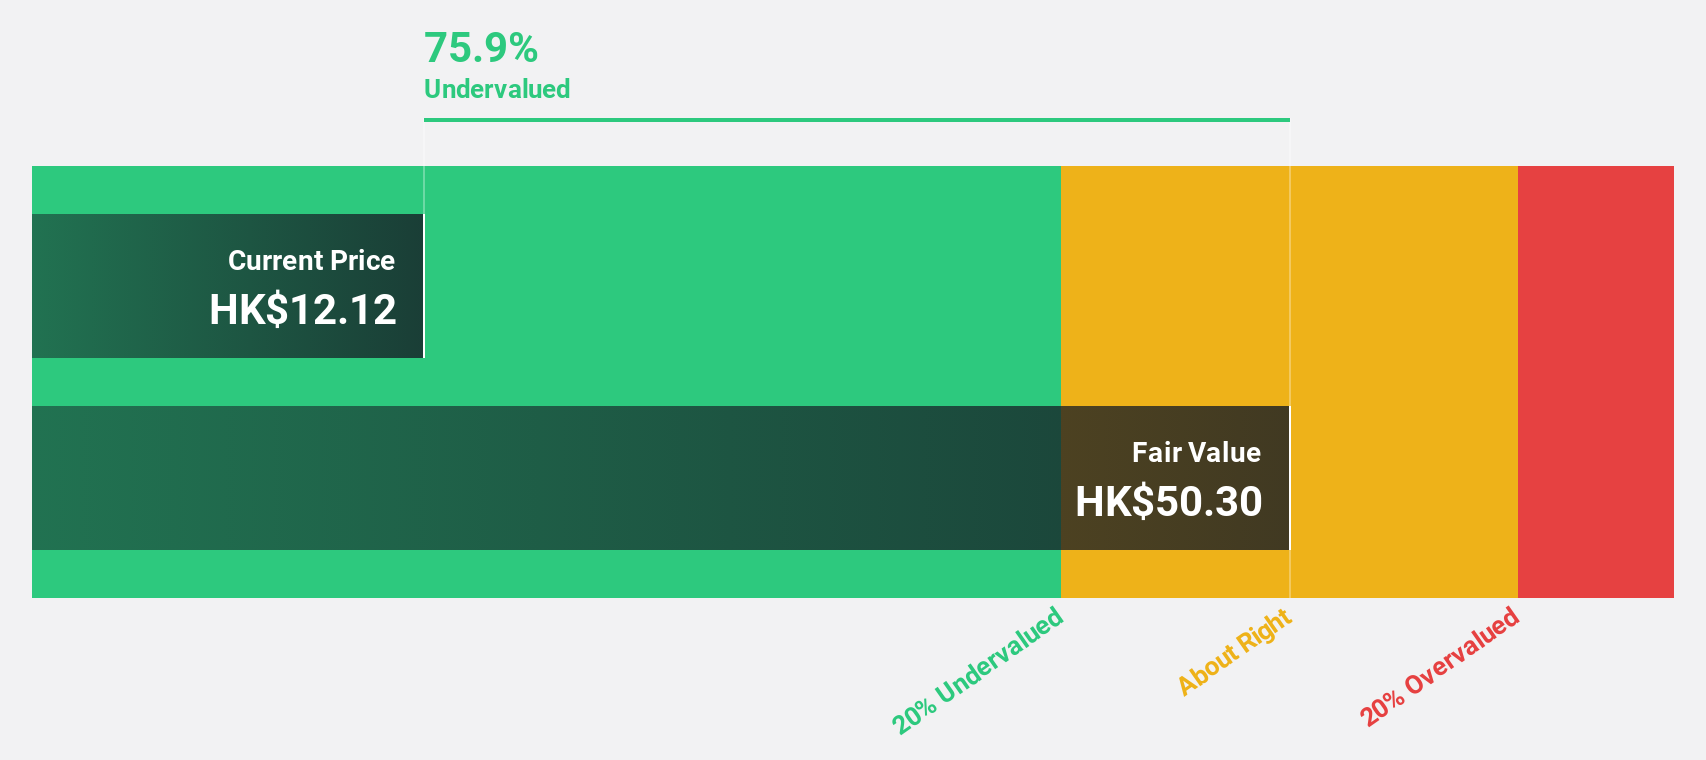
Estimated Discount To Fair Value: 48%
Yadea Group Holdings is trading at HK$8.97, significantly below its estimated future cash flow value of HK$17.26, suggesting undervaluation. Despite a decline in sales and net income for the first half of 2026, forecasts indicate revenue growth of 11% annually, outpacing the Hong Kong market's 9%. Earnings are projected to grow at 16.4% per year. However, an unstable dividend track record remains a concern for investors seeking consistent returns.
- Insights from our recent growth report point to a promising forecast for Yadea Group Holdings' business outlook.
- Click here to discover the nuances of Yadea Group Holdings with our detailed financial health report.
Guangdong Baolihua New Energy Stock (SZSE:000690)
Overview: Guangdong Baolihua New Energy Stock Co., Ltd. operates in the energy sector, focusing on new energy solutions, with a market capitalization of approximately CN¥12.16 billion.
Operations: I'm unable to summarize the company's revenue segments as there are no specific details provided in the text. If you have additional information on their revenue breakdown, feel free to share it for further assistance.
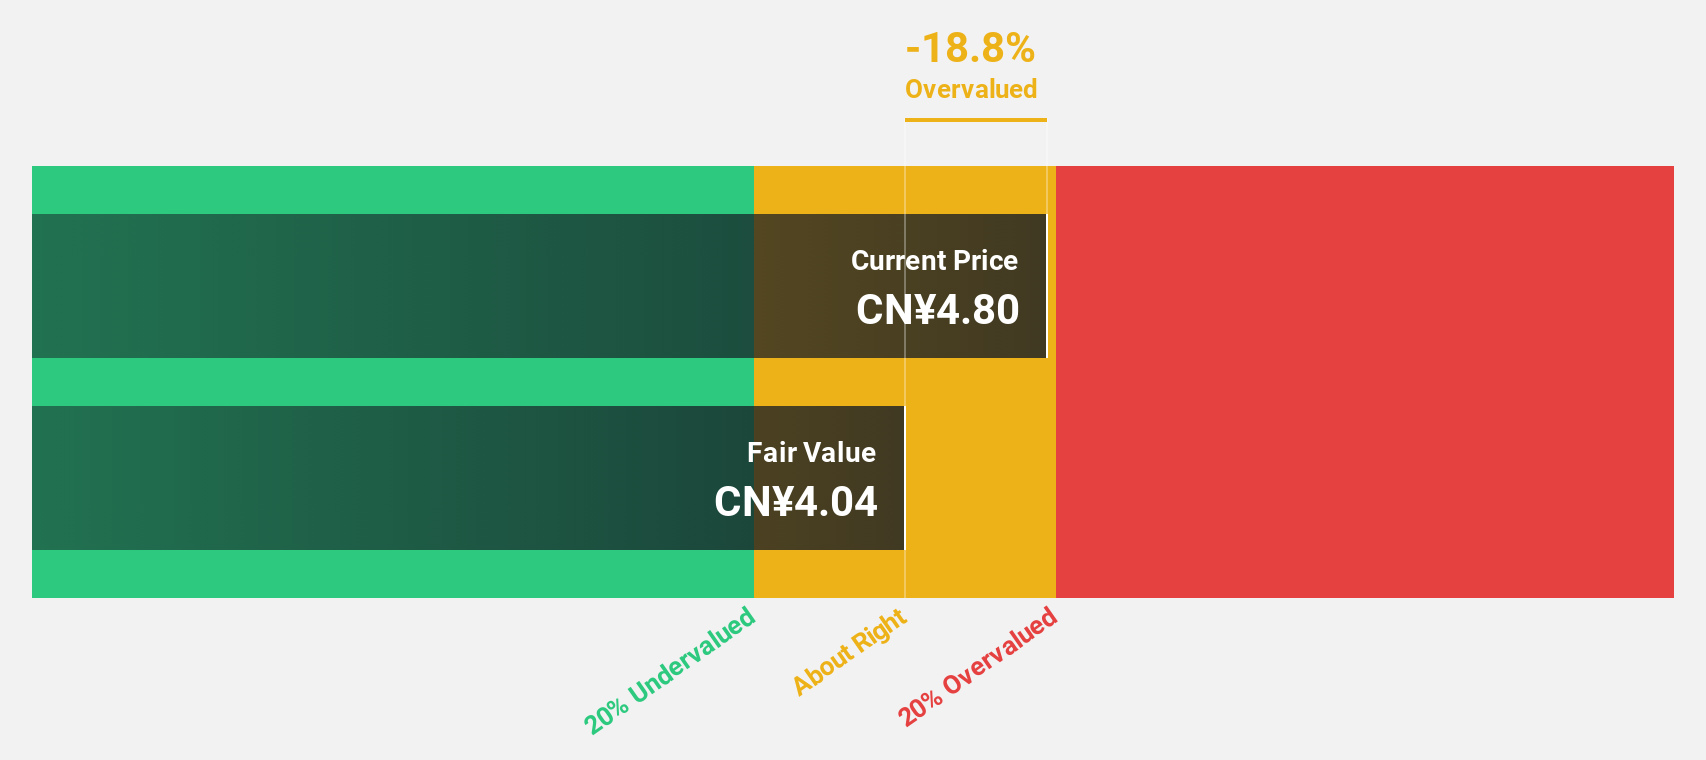
Estimated Discount To Fair Value: 20.9%
Guangdong Baolihua New Energy Stock is trading at CN¥5.59, below its estimated future cash flow value of CN¥7.07, highlighting potential undervaluation. Recent earnings show net income growth to CN¥632.79 million from CN¥558.58 million year-on-year despite a slight revenue decline to CN¥4.17 billion from CN¥4.36 billion. Earnings are forecasted to grow by 8.8% annually, though slower than the Chinese market average of 26.9%, and the company has an unstable dividend history.
- According our earnings growth report, there's an indication that Guangdong Baolihua New Energy Stock might be ready to expand.
- Click here and access our complete balance sheet health report to understand the dynamics of Guangdong Baolihua New Energy Stock.
Turning Ideas Into Actions
- Unlock more gems! Our Undervalued Asian Stocks Based On Cash Flows screener has unearthed 175 more companies for you to explore.Click here to unveil our expertly curated list of 178 Undervalued Asian Stocks Based On Cash Flows.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com