


Palomar Holdings (PLMR) Could Be 20% Undervalued As Rating Strength Holds
AM Best’s affirmation of Palomar Holdings (PLMR) with a "bbb" issuer credit rating, stable group outlooks, and a positive view on its surety unit keeps attention on the company’s risk profile and capital strength.
Recent price action around Palomar Holdings has been choppy, with the share price up 3.38% over the past week but down 6.32% over the past three months, while a 1-year total shareholder return of 11.13% and a very large 3-year total shareholder return suggest longer term momentum has been much stronger than the shorter term pullback near the current US$130.76 level.
Scan for other insurers with similar rating strength and recent momentum shifts by running the 31 resilient stocks with low risk scores alongside Palomar Holdings in your research.
Palomar Holdings has pulled back in the short term even as multiyear returns remain strong and AM Best maintains a steady view on its credit profile. Is that enough reason to buy now, instead of waiting for a cheaper entry as valuation comes into focus next?
Most Popular Narrative: 19.9% Undervalued
Palomar Holdings last closed at $130.76, while the most followed narrative places fair value closer to $163.17, so the gap between price and implied worth is front and center for anyone weighing the recent pullback.
Deliberate diversification into crop, casualty, and surety, including the Gray Surety acquisition and rapid growth in crop and surety premiums, is shifting Palomar Holdings mix toward businesses that are less tied to traditional P&C cycles. This can support more stable revenue and earnings even as the loss ratio moves higher.
See why 27 investors see Palomar Holdings as 20% undervalued.
Result: Fair Value of $163.17 (UNDERVALUED)
Still, the Palomar Holdings story could be knocked off course if higher loss ratios in crop and casualty lines squeeze profitability, or if commercial earthquake pricing pressure lingers longer than bulls expect.
Find out about the key risks to this Palomar Holdings narrative.
Another View: Palomar Holdings Through The P/E Lens
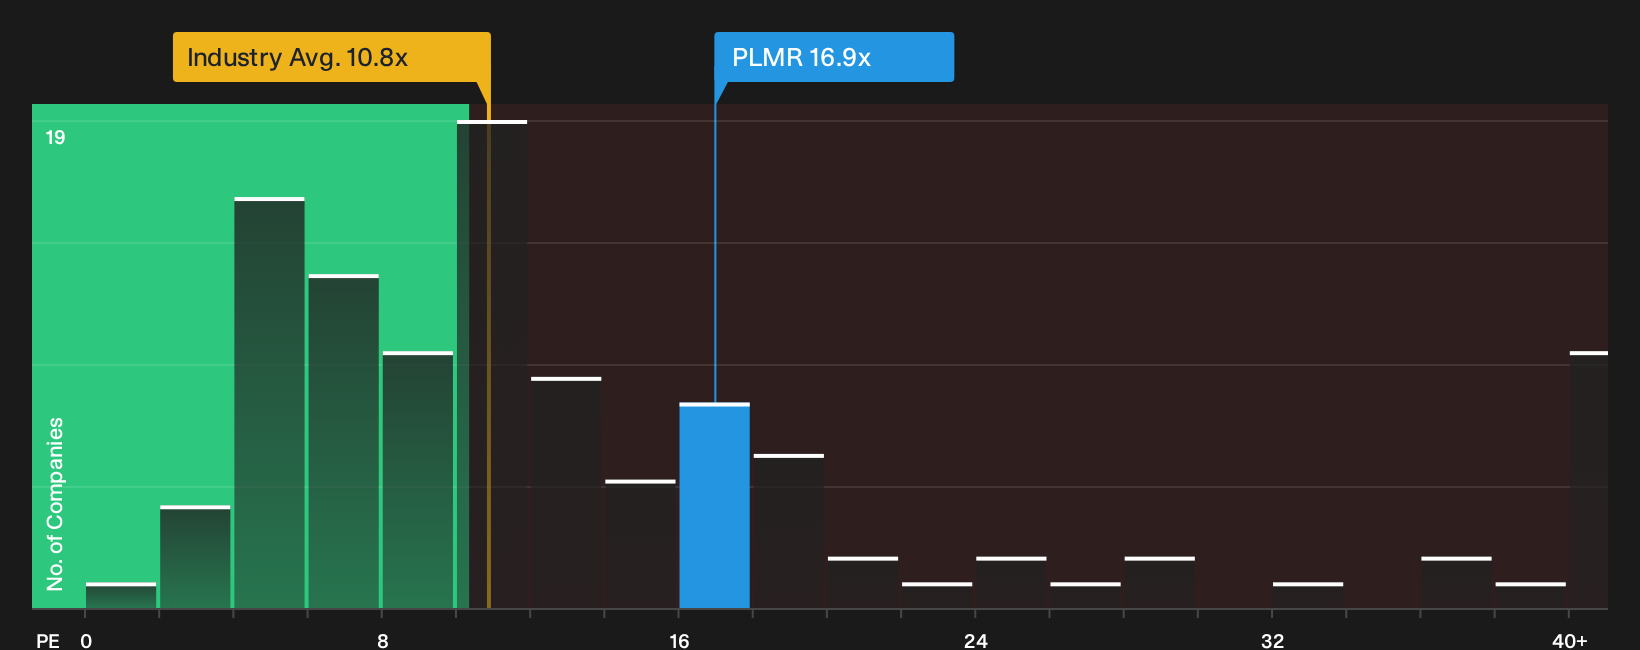
Multiples tell a different story. Palomar Holdings trades on a P/E of 16.9x, which is higher than the US Insurance industry at 10.8x, the peer average at 8x, and even above a fair ratio of 12.9x that the market could eventually lean toward. Is the higher tag justified by quality or just adding valuation risk for new buyers?
For a closer look at how this pricing stacks up against earnings power, it helps to break down what the numbers imply for future returns and downside risk, then weigh that against your own expectations for underwriting discipline and growth in Palomar Holdings over the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Palomar Holdings can leave you torn, so move quickly to test the numbers, weigh the trade offs, and then study the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Palomar Holdings?
If you stop with Palomar Holdings, you risk missing other opportunities that match your style, so broaden your watchlist before the next setup passes you.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) that fit your comfort with risk.
- Hunt for mispriced quality by scanning the 29 high quality undervalued stocks and see which businesses align with your expectations.
- Spot potential future leaders early by checking the 20 high quality undiscovered gems before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com