


Did Deferred Gold Sales Just Shift Freeport McMoRan's Stock Narrative?
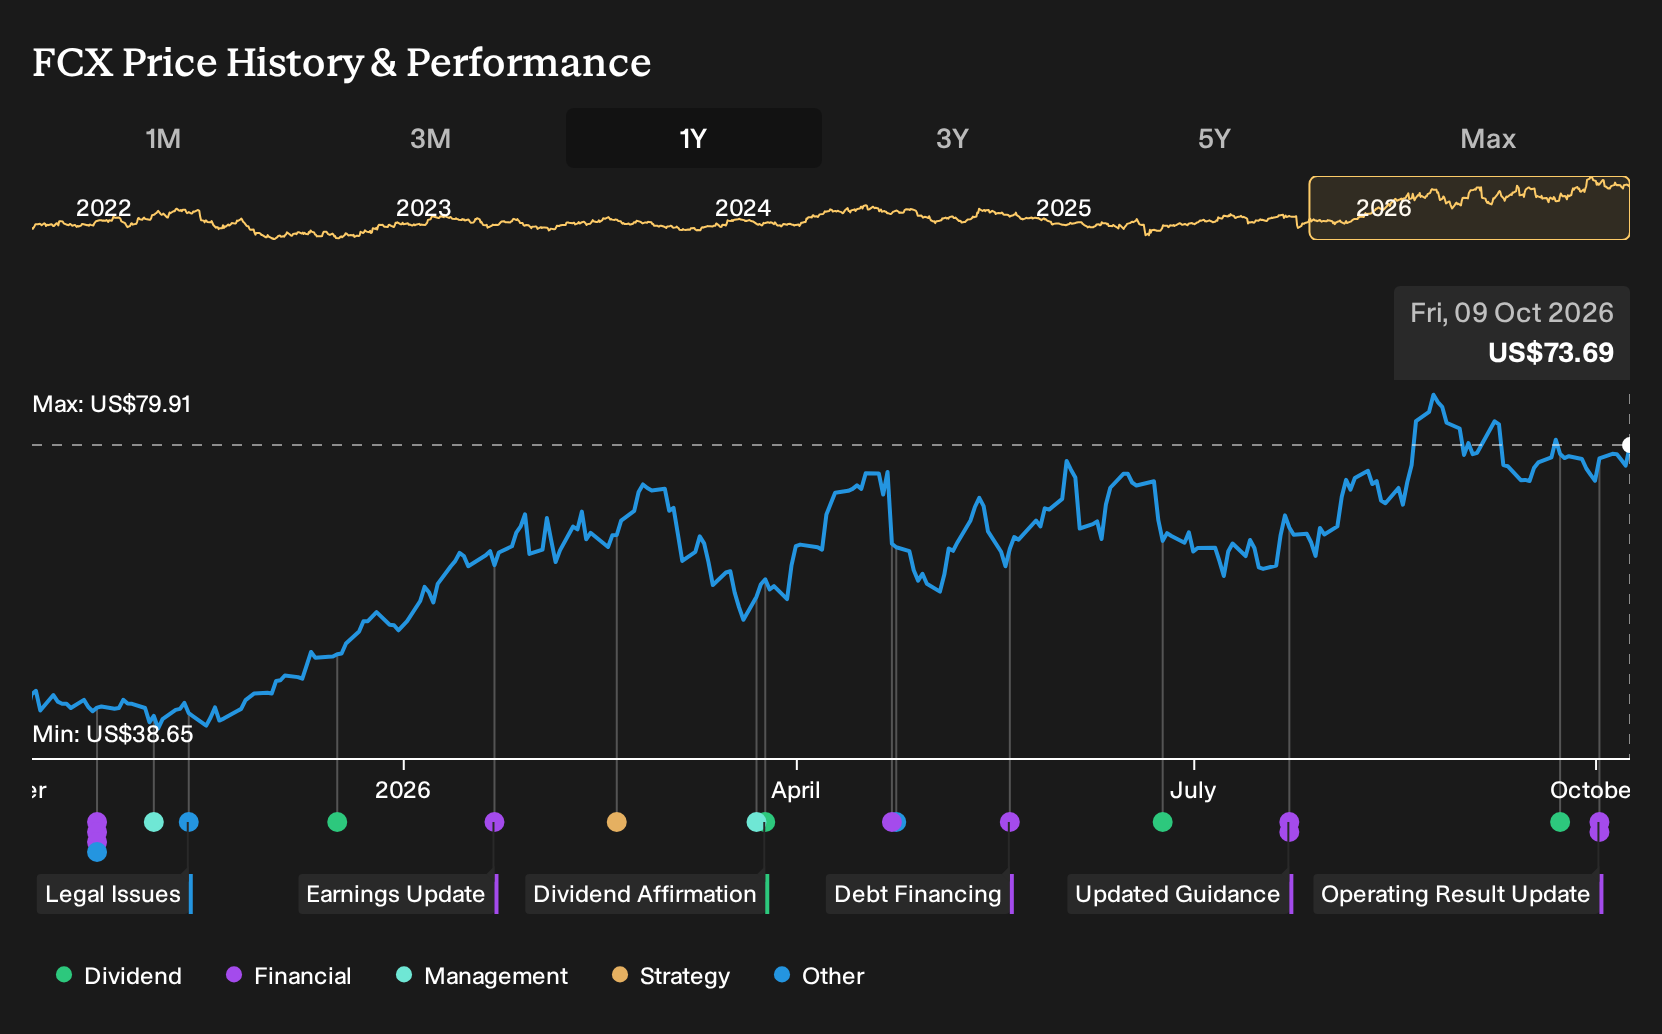
- Freeport-McMoRan reported past third quarter 2026 output with consolidated copper production of about 830 million pounds and gold production of roughly 230 thousand ounces. Around 60 thousand ounces of refined gold sales at PTFI shifted from that quarter into the fourth quarter.
- The updated guidance now points to third quarter 2026 copper sales of roughly 750 million pounds and gold sales of about 100,000 ounces. This highlights how timing shifts at PTFI can affect reported volumes even when underlying mine performance broadly tracks expectations.
- We will now look at how this Freeport-McMoRan production update, especially the deferred PTFI gold sales, interacts with the investment narrative.
Freeport-McMoRan Investment Narrative Recap
To own Freeport-McMoRan, you need to be comfortable with a copper and gold producer that leans heavily on complex Indonesian assets, long dated U.S. expansions and large capital projects. The latest production update shows copper and gold output tracking expectations, and the PTFI gold deferral appears to be a timing issue rather than a change to the short term thesis.
Right now, the key near term swing factor remains operational execution at Grasberg and the Indonesian smelters. Any fresh disruptions there could affect volumes and cash generation. The biggest risk is still project slippage or higher costs at Grasberg, Bagdad and the U.S. leach program, and this disclosure does not materially alter that balance.
The guidance confirmation for third quarter 2026, with copper sales expected around 750 million pounds and gold sales near 100,000 ounces, is the most relevant fresh datapoint. Those numbers connect the reported timing shift directly to what will flow through the income statement in the near term.
For you as a shareholder, this keeps attention on whether Freeport-McMoRan can turn its production profile and leach or brownfield projects into consistent, planned output rather than on any sudden reset to expectations. Execution at Indonesian operations and the U.S. mines remains at the center of both the potential upside catalysts and the operational risk.
Freeport-McMoRan's current analyst story points to revenues of US$39.0b and earnings of US$5.2b by 2029, based on a projected 14.7% yearly revenue growth rate. That path implies earnings rising by about US$2.3b from US$2.9b today to the 2029 consensus level.
Uncover why Freeport-McMoRan's fair value indicates that it is in line with its current price.
Exploring Other Perspectives
One alternate view around Freeport-McMoRan focuses on rising U.S. cash costs rather than project upside. The most cautious analysts were penciling in revenue of about US$35.2b and earnings near US$3.5b by 2029, well below the US$39.0b and US$5.2b consensus path. This production and guidance update could eventually shift those expectations in either direction.
Explore 3 other Freeport-McMoRan fair value estimates, including one that suggests it could be worth just $73.14.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Freeport-McMoRan research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Freeport-McMoRan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Freeport-McMoRan's overall financial health at a glance.
Looking for more investment ideas beyond Freeport-McMoRan?
Once you have a view on Freeport-McMoRan, it can help to compare that thesis with other listed businesses that share similar risk profiles or balance sheet traits. A targeted screener is one of the quickest ways to do that.
- If you want to stay focused on financial resilience, filter for companies with strong cushions by using the list of solid balance sheet and fundamentals (25 results).
- For investors who care most about valuation support, sort through companies that combine quality fundamentals with potentially attractive pricing via the 29 high quality undervalued stocks.
- If consistent income is a priority, scan for higher yielding payers that still aim to keep payouts supported by fundamentals through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com