


Did Earnings And Sales Guidance Just Shift McCormick Stock's Investment Narrative?
- McCormick reported third quarter 2026 sales of US$2,024.8 million and net income of US$97.6 million, and reaffirmed full year 2026 net sales growth guidance of 13% to 17%.
- The combination of higher sales, sharply lower quarterly earnings per share, and a maintained growth outlook highlights the pressure on McCormick’s profitability while management signals confidence in demand.
- We will now look at how McCormick’s investment narrative is shaped by reaffirmed full year sales guidance alongside weaker quarterly earnings.
McCormick Investment Narrative Recap
To own McCormick, you need to believe this flavor platform can translate strong top line momentum into steadier earnings, while absorbing higher costs and competitive pressure in Consumer Americas. The reaffirmed 13% to 17% net sales growth guidance suggests management still sees healthy demand. The near term catalyst is execution in Consumer and Flavor Solutions pricing and volume, and the weak quarterly EPS keeps that execution firmly in focus.
The biggest current risk sits around profitability and integration. Lower third quarter earnings against higher sales put more weight on cost control, mix and productivity, especially with a high debt load and the Unilever Foods deal ahead. If integration or regulatory remedies drag, the sales story might not show up in margins as quickly as investors want.
The reaffirmed full year net sales growth guidance is the most relevant recent announcement for this set of results. Holding a 13% to 17% outlook while third quarter net income fell to US$97.6 million and EPS from continuing operations moved to US$0.36 keeps attention on how McCormick converts volume and pricing into cash, not just reported revenue.
For catalysts, that guidance ties directly into the planned Unilever Foods combination and the cost synergy targets around it. Regulatory reviews and required divestitures, such as Colman’s mustard, remain operational swing factors that can influence how quickly McCormick reaches its margin ambitions and free cash flow goals, and how much flexibility it has to manage debt and ongoing brand investment.
What the McCormick Forecasts Are Really Asking You To Believe
McCormick's narrative projects US$8.9 billion of revenue and US$699.2 million of earnings by 2029. That profile lines up with analyst assumptions of 5.1% yearly revenue growth and an earnings decline of about US$800.8 million from current earnings of US$1.5 billion.
Uncover how McCormick's fair value indicates a 22% potential upside to its current price that could narrow quickly.
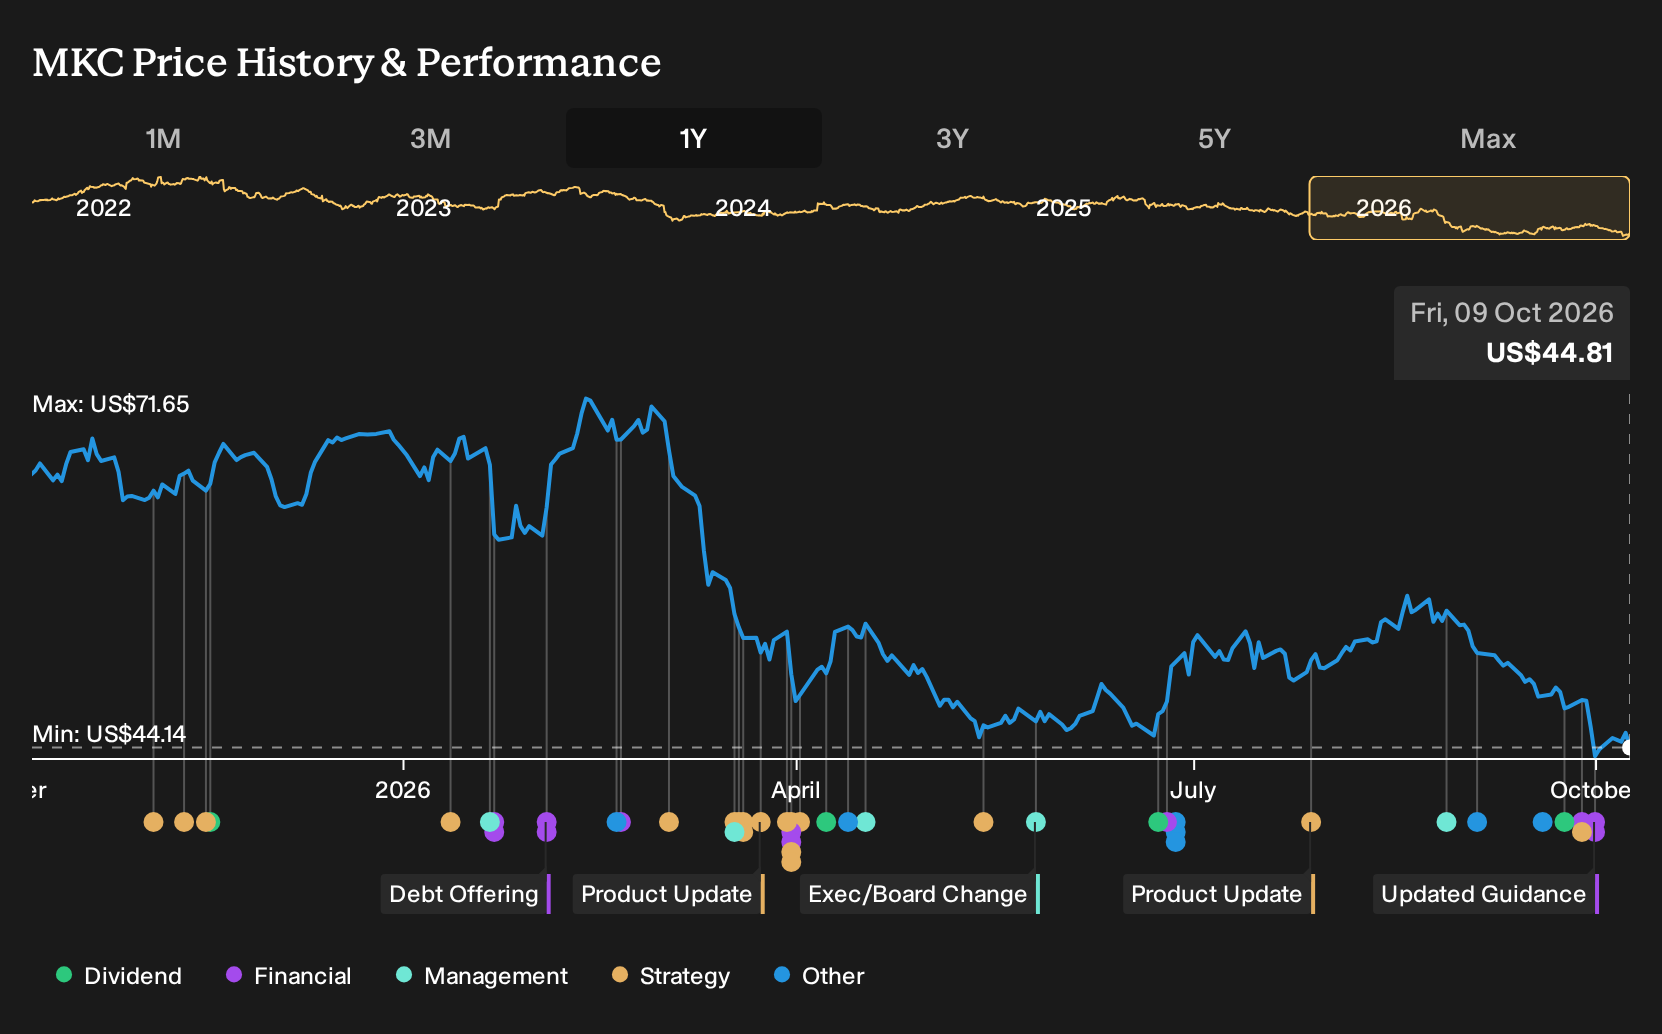
Exploring Other Perspectives
One alternate angle on McCormick focuses squarely on integration risk from the Unilever Foods deal. The most cautious analysts were already building in slimmer margins and earnings of about US$736.5 million on roughly US$9.0b of revenue by 2029 before this guidance news. That is a far more pessimistic script. Use it as a reminder that views can differ widely, and explore several of these pre news forecasts as you decide how this latest update might reshape the story.
Explore 5 other McCormick fair value estimates, including one that suggests it could be worth just $47.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your McCormick research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for McCormick. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McCormick's overall financial health at a glance.
Looking for more McCormick sized investment ideas?
If the McCormick story has you thinking about what else might be mispriced or misunderstood, you can widen your field of vision using the Simply Wall St Screener to source other stocks with specific qualities that fit your own approach.
- For investors who care most about quality at a reasonable entry point, start with a curated set of 29 high quality undervalued stocks that may align with your preferred balance between fundamentals and price.
- If capital preservation sits high on your list, consider companies flagged as 31 resilient stocks with low risk scores and see which ones best match your comfort with volatility and business resilience.
- For those focused on balance sheet strength and financial footing, scan the list of solid balance sheet and fundamentals (25 results) to find businesses where debt and liquidity metrics may better support long term plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com