


Is Brookfield (TSX:BN) Undervalued Ahead Of Its November 12 Results?
Brookfield (TSX:BN) has scheduled its next major update, with third quarter 2026 results set for release on November 12, followed by a conference call that morning.
Recent trading has been mixed for Brookfield, with a 1-day share price return of 1.30% at CA$52.95 offering a brief lift against a 90-day share price decline of 13.76% and a year-to-date drop of 17.38%, which points to fading momentum ahead of the earnings update.
Scan how Brookfield stacks up against a curated list of solid balance sheet and fundamentals (7 results) that has also held up through tougher patches in the market.
For Brookfield, a small recent bounce sits against a much steeper slide over the year. Is that move about the multi asset manager’s earnings power, or just sentiment resetting ahead of the next results?
Most Popular Narrative: 35% Undervalued
The leading narrative on Brookfield says fair value sits well above the recent CA$52.95 close. This frames the current weakness as a valuation gap rather than a verdict on the whole business.
On IFRS numbers BN looks like a low-return, highly levered conglomerate. On its own look-through measures it earns low-to-mid teens on equity. Which lens is right is the investment question.
See why 2 investors see Brookfield as 35% undervalued.
Result: Fair Value of CA$82 (UNDERVALUED)
Still, the Brookfield story only holds if carry actually converts to cash and if Wealth Solutions’ related party exposure does not start to erode that earnings base.
Find out about the key risks to this Brookfield narrative.
Another Take On Brookfield’s Valuation
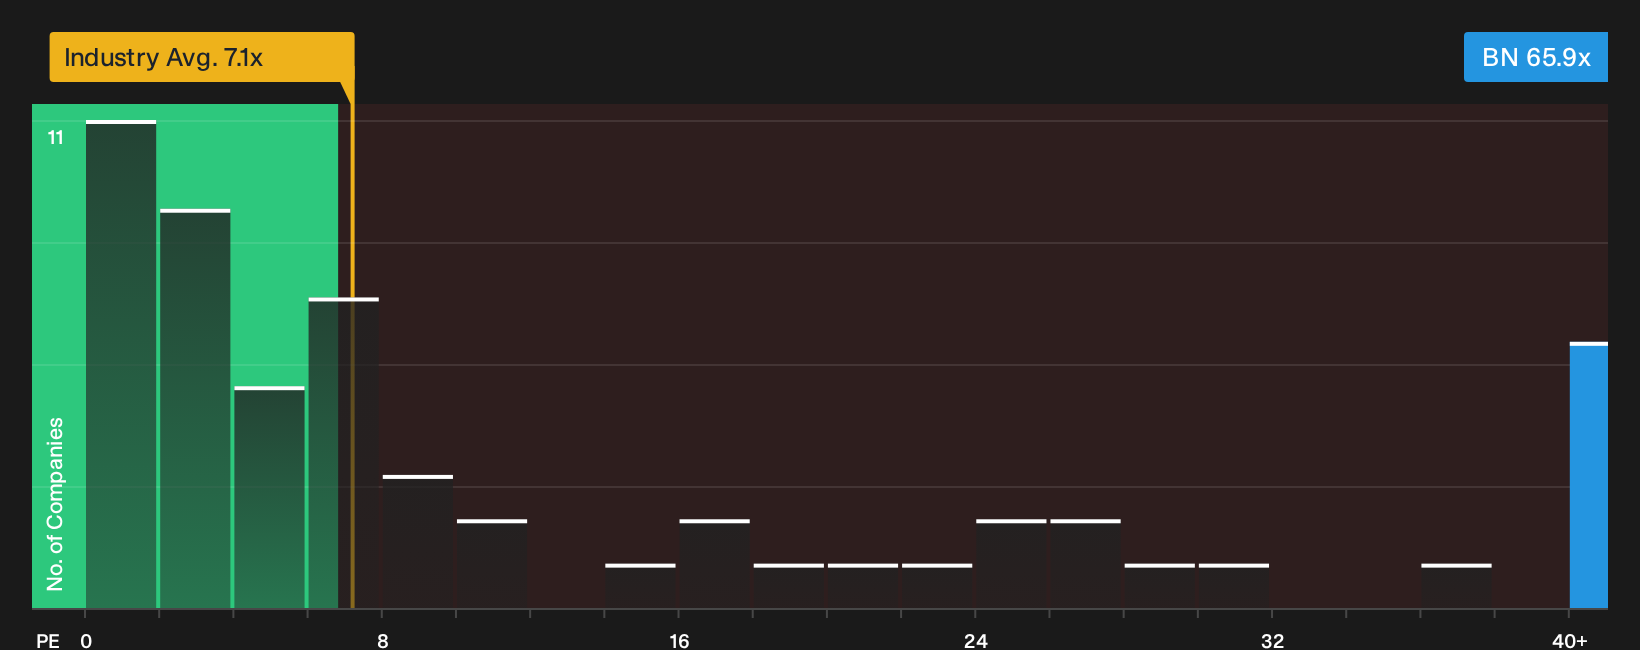
Cash earnings and fair value work up to a rich picture for Brookfield, yet the plain P/E ratio tells a very different story. At roughly 65.9x earnings versus about 7.1x for the wider Canadian Capital Markets industry and 16.3x for peers, the stock looks heavily priced on this yardstick alone.
Paying that kind of multiple leaves little room for disappointment. If the market edges closer to the industry or peer averages instead of supporting a premium, holders wear the adjustment. The question is whether that gap reflects genuine quality or simply valuation risk that has not been fully priced in. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Brookfield story points in different directions, so it makes sense to move fast, review the full data set, and decide where you land. To balance the upside arguments with the areas investors are more cautious about, take a close look at the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Brookfield?
If Brookfield has you thinking harder about valuation, use that momentum and widen your watchlist with a few focused screens that surface different types of opportunities.
- Target resilient income by scanning for companies that behave like potential income anchors through the 3 dividend fortresses.
- Hunt for quality at a sensible price by reviewing the 8 high quality undervalued stocks that combine stronger fundamentals with more modest valuations.
- Unearth future candidates before the crowd by working through the 9 high quality undiscovered gems that pair solid metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com