


REA Group (ASX:REA) Faces Housing Weakness, Is The Stock Getting Too Pricey?
REA Group (ASX:REA) has been thrown into the spotlight as Australian housing values retreat across more than 80% of suburbs. Higher interest rates and tax changes are driving fresh scrutiny of the stock’s recent volatility.
Recent moves tell a mixed story for REA Group. The share price has climbed over the past quarter, with a 90 day share price return of 4.43% and a 1 day gain of 2.24%. However, the year to date share price return is down 15.71% and the 1 year total shareholder return has fallen 28.92% as investors reassess growth prospects, competitive threats and regulatory risk. This is in contrast to a richer long term total shareholder return of 1.34% over three years and 5.67% over five years.
Scan how other property exposed businesses are reacting to these housing headwinds by reviewing the hand picked list of solid balance sheet and fundamentals (12 results).Bulls point to REA Group’s rising revenue and profit alongside the recent 90 day rebound, while bears focus on housing weakness, regulatory risk and competition. Which story fits the current A$155.75 share price?
Most Popular Narrative: 5% Overvalued
According to ANTONI0, the most followed valuation story for REA Group pegs fair value at A$148 per share, slightly above the A$155.75 last close, which leaves the stock trading at around a 5% premium to that estimate when markets are already wrestling with softer housing data.
On the asset's own ~8.5% cost of capital the conservative DCF (~AU$148), a de-rated own-history multiple (~AU$148) and a strategic/SOTP value all sit at or above today's price; the book-anchored Montgomery model is structurally inapplicable to a capital-light network and is shown but not counted. Static margin of safety is thin (~9%), but on the elite-compounder forward frame and a ~14% base owner's return the entry clears.
See why 10 investors see REA Group as 5% overvalued.
Result: Fair Value of A$148 (OVERVALUED)
Still, that story could crack if the ACCC pricing probe reshapes how REA Group charges agents, or if CoStar backed Domain starts taking share more quickly.
Find out about the key risks to this REA Group narrative.
Another View On REA Group’s Valuation
There is a second story running beside ANTONI0’s A$148 fair value. Simply Wall St’s DCF model values REA Group at A$165.01 per share, which frames the current A$155.75 quote as slightly undervalued on projected cash flows rather than modestly overvalued on A$148.
Both approaches lean on future cash generation, but they weigh growth, risk and discount rates differently. For an investor trying to make sense of that gap, the real question is which set of assumptions feels closer to how REA Group could actually perform.
Look into how the SWS DCF model arrives at its fair value.
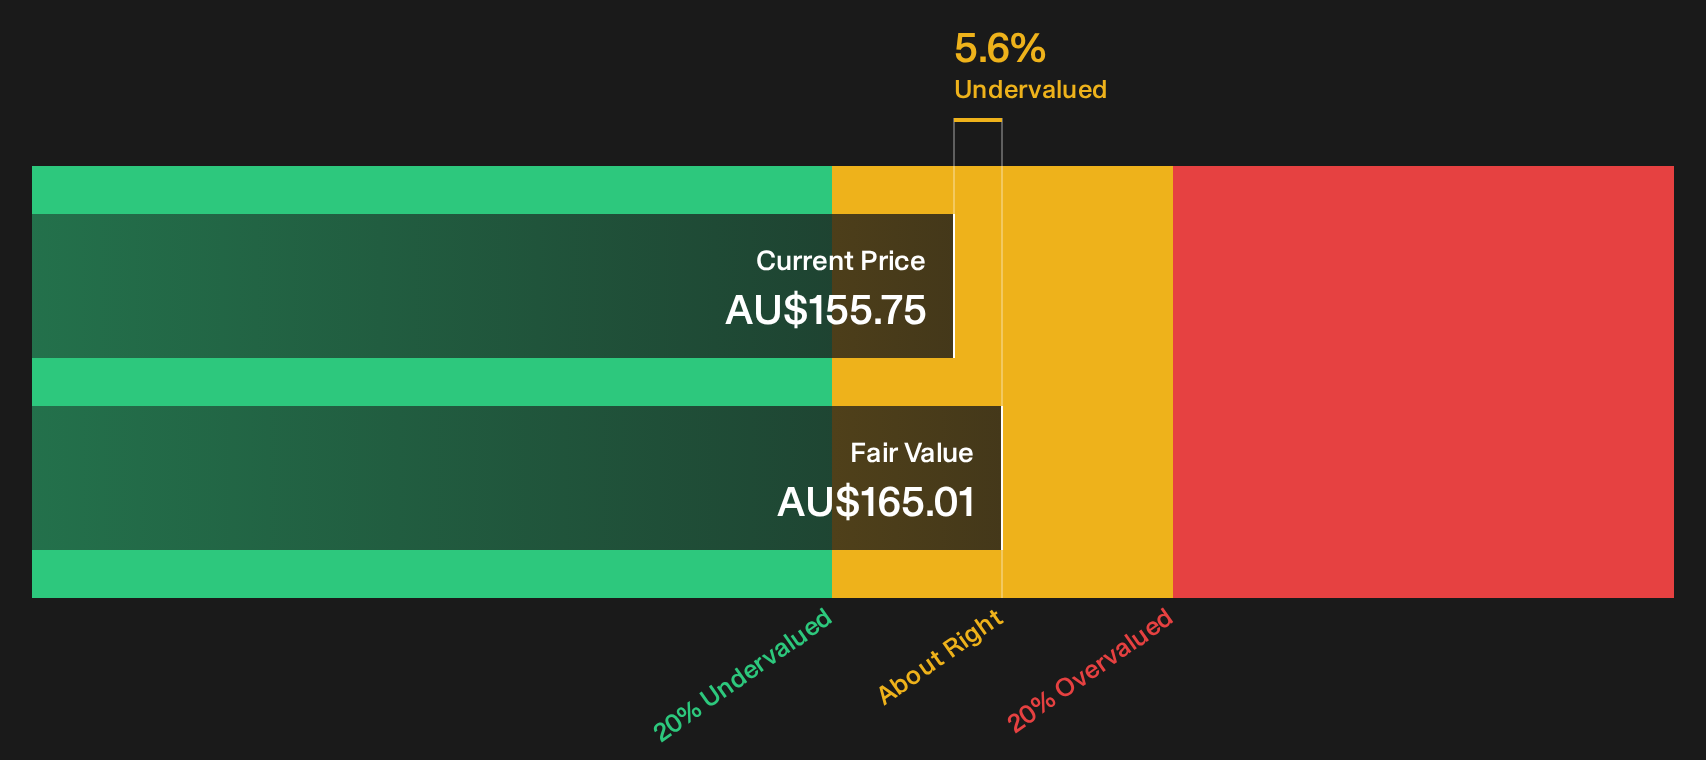
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out REA Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the split between overvalued and undervalued views on REA Group, or starting to lean one way already? Move quickly from headline narratives to your own evidence based stance by reviewing the 2 key rewards.
Looking For More Investment Ideas Beyond REA Group?
If the mixed signals around REA Group have you reassessing your watchlist, this is the moment to broaden your opportunities with a few focused stock screens.
Use these ideas to pressure test your current holdings and spot gaps in your approach before other investors move first.
- Target resilient compounding potential by reviewing a curated 4 high quality undervalued stocks that combine quality fundamentals with prices that do not fully reflect those traits.
- Strengthen your income stream by scanning a set of 6 dividend fortresses that aim to sustain payouts while the market debates growth stories like REA Group.
- Protect your downside first by focusing on a 7 resilient stocks with low risk scores that score well on balance sheet strength and financial risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com