


How Investors May Respond To DuPont (DD) Sugar Separation Tool Launch
- DuPont de Nemours recently introduced the DuPont Sugar Separation Advisor, a digital tool that helps sugar and sweetener manufacturers screen chromatographic separation options and shortlist DuPont AmberLite resins for further testing using lab based experimental data.
- The tool turns years of DuPont chromatography work into a self service resource for manufacturers. This can strengthen customer relationships at the earliest design stage of sugar recovery and purification projects.
- We will now look at how DuPont de Nemours' new Sugar Separation Advisor could influence the broader investment narrative around the group.
Expand your search beyond DuPont de Nemours by scanning our hand picked list of solid balance sheet and fundamentals (25 results), which also includes companies leaning into specialized process technologies and industrial know how.
DuPont de Nemours Investment Narrative Recap
To own DuPont de Nemours, you need to be comfortable with a focused industrial materials group that leans on productivity programs, a concentrated Healthcare & Water Technologies portfolio, and disciplined capital allocation rather than rapid top line expansion. The Sugar Separation Advisor fits that story as another applied technology asset, but it does not materially change near term drivers on its own.
The near term swing factor still sits in execution on 3% annual COGS productivity and cost of poor quality reduction, especially with input cost inflation and pricing friction in the background. The biggest risk remains environmental and legal exposure tied to historical PFAS issues, which can absorb cash that might otherwise support investment or returns.
Among recent developments, the sharpened focus on Healthcare & Water Technologies and Diversified Industrials is most relevant to this new chromatography tool. Management is concentrating capital on niches where application know how and R&D, around 2.5% of sales, can support differentiated products such as AmberLite resins and filtration platforms.
The Sugar Separation Advisor appears to be a practical expression of that focus, turning lab work and AI enabled workflows into something that can make customer screening faster and more data driven. For you as a shareholder, the key question is whether DuPont de Nemours can replicate this kind of tool across more applications, while still managing PFAS liabilities and oil and gas linked cost pressure without eroding margins.
What The Current DuPont de Nemours Forecasts Assume
On current analyst numbers, DuPont de Nemours is being framed as a slower but steadier compounder that leans more on margin improvement than on big swings in sales. Consensus points to revenue expanding by about 4.4% a year over the next few years, which is a measured pace for an industrial materials group with a tight portfolio. That backdrop matters when you look at niche tools like the Sugar Separation Advisor, because these kinds of offerings tend to reinforce pricing power and product mix rather than fundamentally changing how fast total sales move.
Earnings expectations are much more ambitious than the top line. Analysts see profit moving from US$306.0 million today to US$942.0 million by 2029, which implies earnings a little over three times higher on this timeframe. That scale of change depends heavily on profit margins lifting from 4.4% to 11.8%, supported by productivity work, lower cost of poor quality and tighter capital deployment into areas such as Healthcare & Water Technologies. For an investor, the Sugar Separation Advisor slots into that story as an example of lab know how and data tools being turned into commercial assets that can support those higher profitability assumptions.
The valuation overlay is demanding. To line up with the current analyst target, you would need to accept revenue of US$8.0b and earnings of US$942.0 million in 2029, with DuPont de Nemours trading on a P/E of 27.7x against a sector level of 18.2x. That gap means you are paying for the combination of cleaner portfolio focus, productivity execution and capital returns to play out largely as expected. Any shortfall in cost savings, PFAS cash outflows or the ability to keep pricing roughly in step with input inflation could leave that multiple looking full.
Tools like the Sugar Separation Advisor can still matter in that context. Faster and more accurate resin screening can support tighter project economics for customers, which can strengthen relationships and help DuPont de Nemours defend or improve pricing in chromatography and filtration. When these kinds of workflow tools are repeated across more product families, they can contribute to the broader push toward the targeted margin improvement that sits behind the consensus earnings path.
DuPont de Nemours' current analyst framework points to revenue of US$8.0b and earnings of US$942.0 million by 2029, built on assumed yearly revenue growth of 4.4% and an earnings increase of about US$636.0 million from US$306.0 million today.
Uncover why DuPont de Nemours' fair value indicates a 31% potential upside to its current price that may not last much longer.
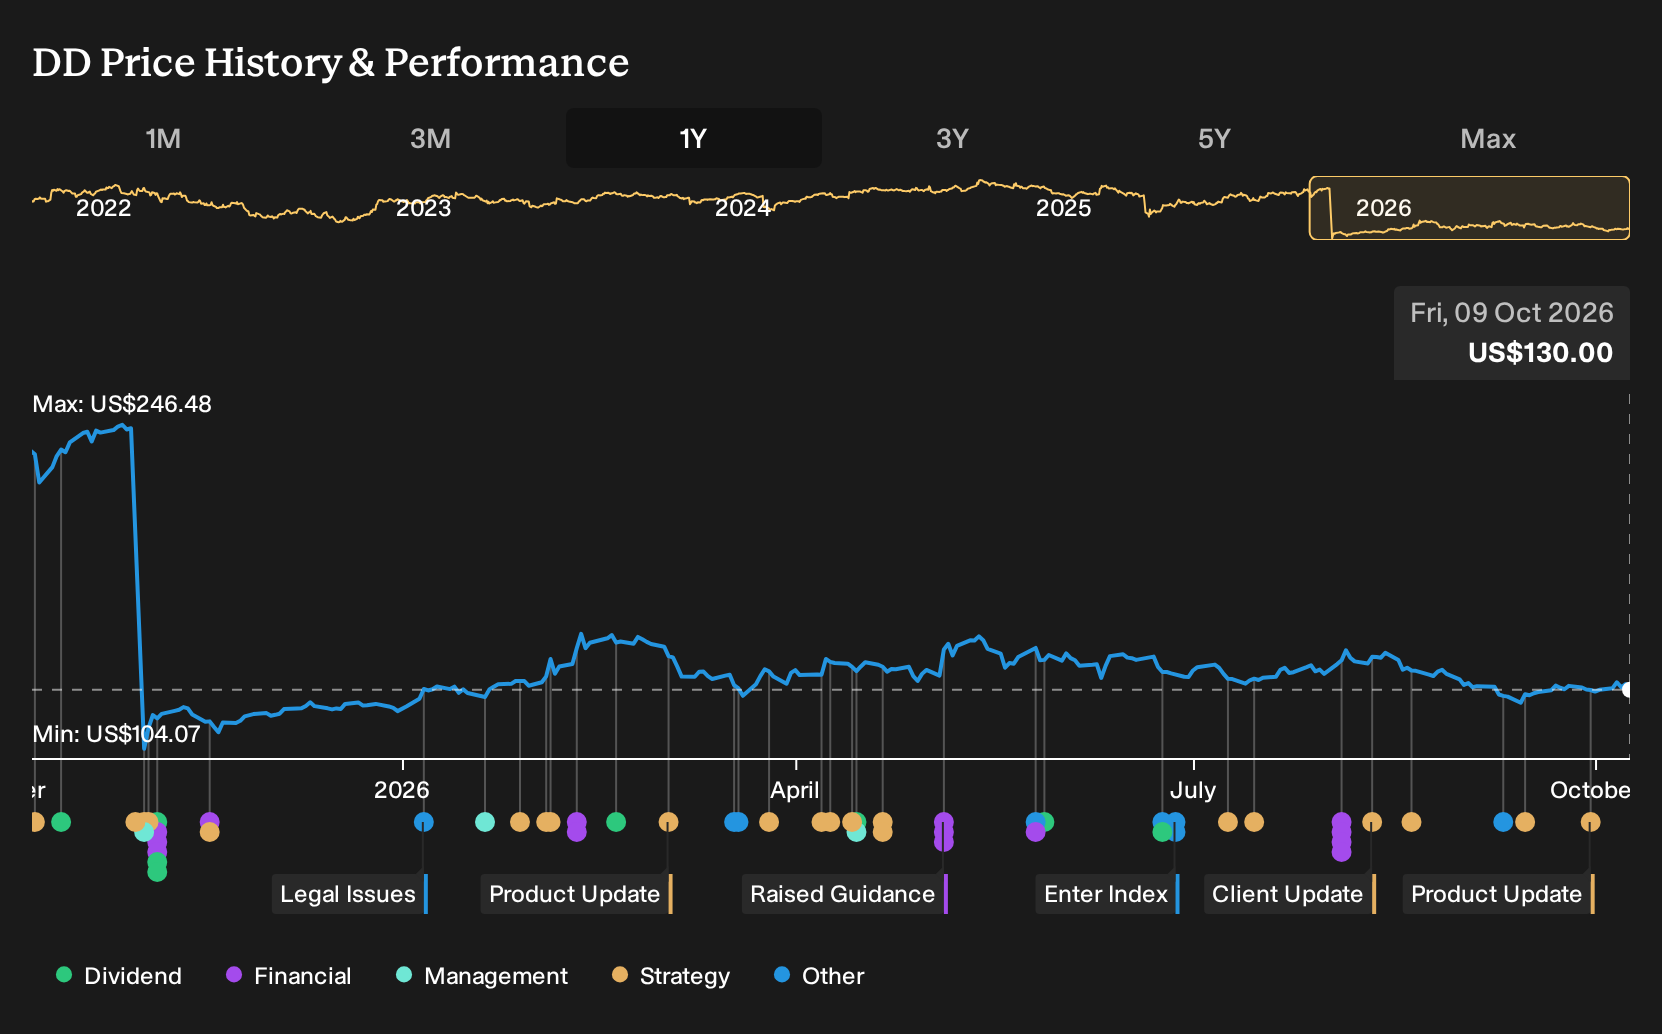
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into DuPont de Nemours’ AI assisted product pipeline as the real swing factor, not just cost control. Before this Sugar Separation Advisor launch, they were already pencilling in revenue of about US$8.1b and earnings near US$1.0b by 2029. You can treat this new tool as a fresh data point and decide whether those pre news expectations still feel realistic, or whether your own view sits closer to, or even below, that bullish camp.
Explore 3 other DuPont de Nemours fair value estimates, including one that suggests as much as 53% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DuPont de Nemours research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DuPont de Nemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DuPont de Nemours' overall financial health at a glance.
Looking For More Investment Ideas Beyond DuPont de Nemours?
If the DuPont de Nemours story has you thinking about portfolio balance, it can help to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for traits that match what you want, whether that is resilience, income, or underappreciated quality.
- For investors who care most about capital preservation and steadier profiles, start with a set of 31 resilient stocks with low risk scores that keep risk scores in tighter territory.
- If long term compounding is your priority and you are hunting for quality at a reasonable price, scan through 20 high quality undiscovered gems that pair solid fundamentals with less market attention.
- For those who want their portfolio to work harder on the income side, shortlist 8 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com