


How US Redomiciliation Approval At Aegon (ENXTAM:AGN) Has Changed Its Investment Story
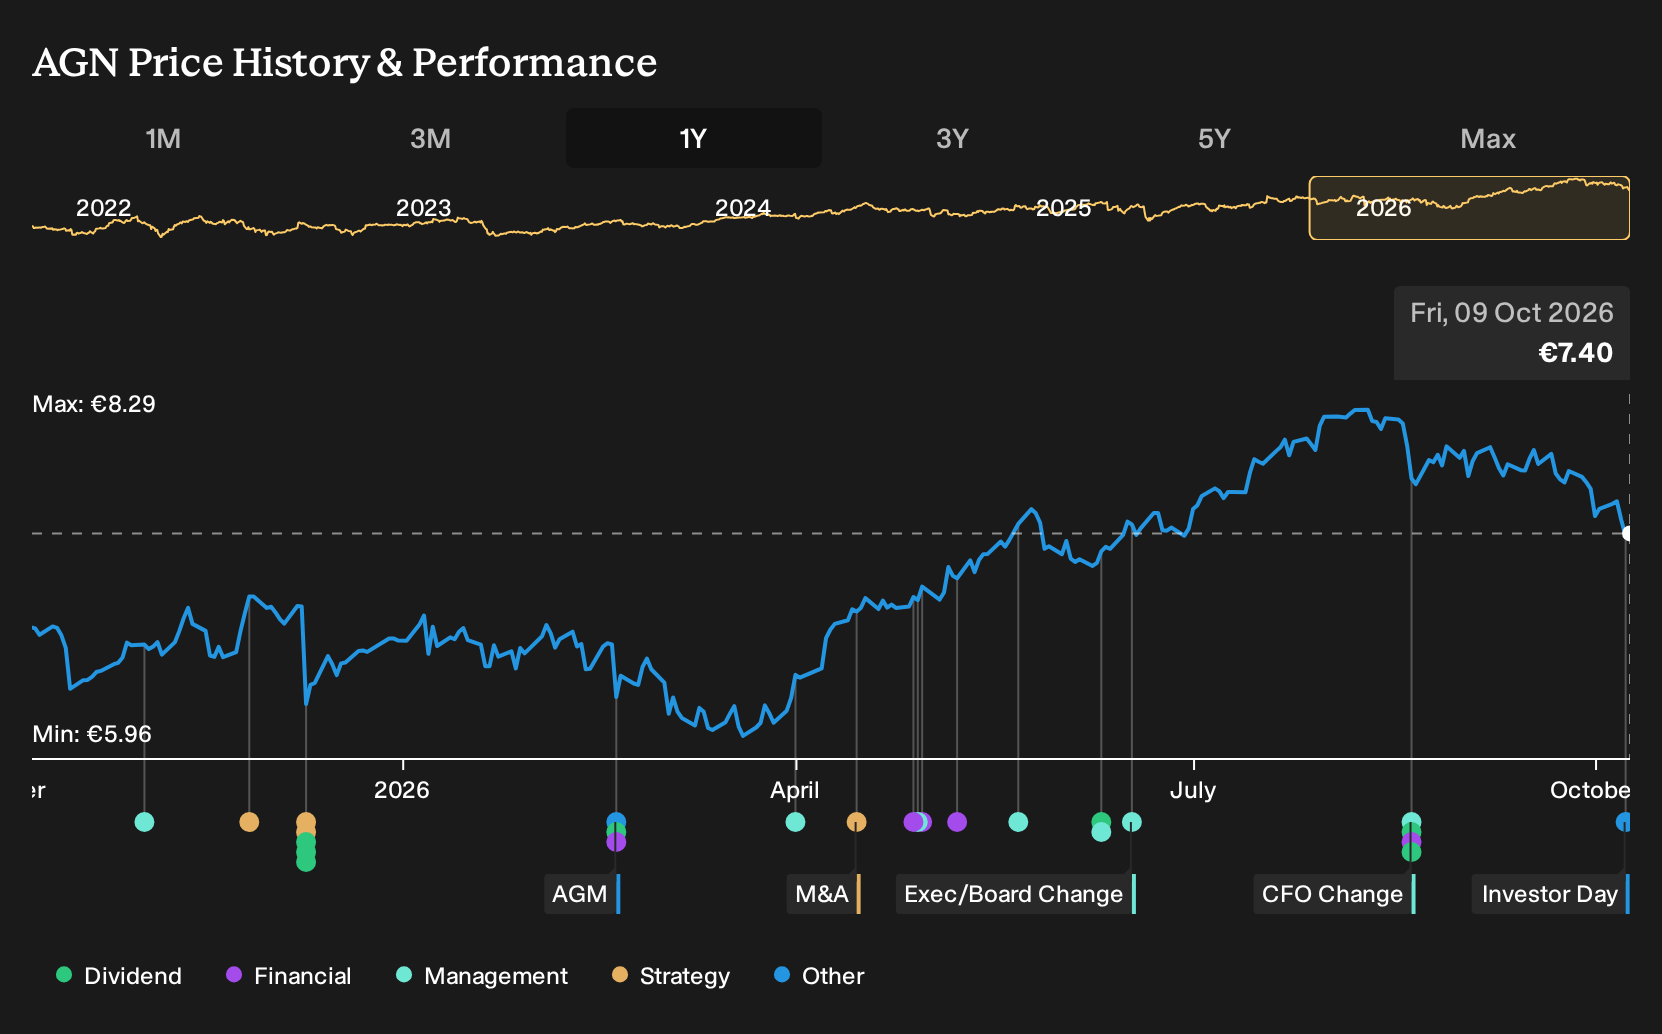
- Aegon recently received approval to redomicile to the US and introduced a new Omnibus Incentive Plan that reshapes governance and executive compensation frameworks around its largest market.
- The combination of a US corporate base and a refreshed incentive scheme could tighten alignment between management decisions, regulatory structures, and Aegon’s fee-focused insurance and retirement operations.
- We will now look at how Aegon’s investment narrative could be influenced by the US redomiciliation decision and Omnibus Incentive Plan.
Scan how other insurers and retirement platforms are priced against similar regulatory shifts by running through our curated list of list of solid balance sheet and fundamentals (204 results) for comparison with Aegon.
Aegon Investment Narrative Recap
To own Aegon, you need to be comfortable with a business that leans heavily on U.S. retirement, life and savings products and is trying to simplify around fee based activities. The big near term swing factor is how efficiently that core U.S. engine converts earnings into cash, especially while revenue is expected to decline and profit growth is moderate.
The biggest risk sits in execution. Redomiciling, shifting to U.S. GAAP and restructuring head office functions add moving parts that can weigh on operating capital generation, particularly while legacy Universal Life and variable annuity blocks still carry actuarial and capital uncertainty.
The U.S. redomiciliation approval is the announcement that matters most for this story. Aegon now has a structure that lines up corporate governance, accounting and executive incentives with the market that drives roughly 70% of its operations. This alignment may make reporting and decision making more U.S. centric.
The Omnibus Incentive Plan ties leadership rewards more closely to outcomes under the new framework. For you, the question is whether management can execute the transition without heavy transition costs or operational disruption, keep pressure on capital light, fee driven lines and steadily reduce risk in runoff portfolios at the same time.
Aegon's narrative projects €9.7 billion revenue and €1.3 billion earnings by 2029, based on analyst estimates that assume revenue will decline by 6.1% per year and earnings will rise from €970.0 million today to an increase of about €330 million by the forecast period.
Uncover how Aegon's fair value indicates a 9% potential upside to its current price before that discount has a chance to close.
Exploring Other Perspectives
You see one sharp contrast around World Financial Group. The most optimistic analysts lean on its U.S. expansion as a key growth engine, backing forecasts of revenue at about €9.4b and earnings near €1.5b by 2029. That is a clear step up from consensus, and both views predate the redomiciliation news. Consider how this fresh development could shift those narratives before you commit to one camp.
Explore 3 other Aegon fair value estimates, including one that suggests as much as 213% potential upside from the current price.
Form Your Own Verdict
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Aegon research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aegon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aegon's overall financial health at a glance.
Looking for more Aegon-sized investment ideas?
Once you have a handle on Aegon, it can help to line it up against other opportunities that match your preferred mix of quality, risk and income. Use the Simply Wall St Screener to surface a wider set of candidates that share the traits you care about most.
- If you want potential value combined with balance sheet strength, scan through our 178 high quality undervalued stocks that may offer a more compelling risk to reward trade off for you.
- For investors who care about resilience first, filter for companies with steadier profiles by running a search across our 223 resilient stocks with low risk scores.
- If you lean toward income and want yield supported by fundamentals, sort through our 221 dividend fortresses and see which businesses deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com