


Nittetsu Mining (TSE:1515) Reassured On Arqueros Progress, Is The Stock Now Too Pricey?
Nittetsu Mining (TSE:1515) just clarified progress at its Arqueros Copper Mine, telling investors that construction and site access are intact while it works toward production by the fiscal year ending March 31, 2027.
Recent trading already reflected rising expectations around Nittetsu Mining, with a 90 day share price return of 27.02% and a year to date share price gain of 37.61%. The 1 year total shareholder return of 85.81% points to strong longer term momentum even after a 16.01% share price pullback over the past month as the market absorbed the Arqueros delay and the recently completed buyback program.
Scan 16 top copper producer stocks to find other copper focused stocks where project updates and production timelines, like Nittetsu Mining's Arqueros progress, could be key catalysts for the next move.
Nittetsu Mining has already delivered a very strong run, yet the pullback since the Arqueros delay leaves a fresh question for you: Is most of the upside already spent, or does valuation still leave room ahead?
Price-to-Earnings of 15.2x: Is It Justified for Nittetsu Mining?
Nittetsu Mining currently trades on a P/E ratio of 15.2x, which places the ¥3,070 share price at a richer level than both its direct peers and the wider Japanese metals and mining group.
The P/E multiple compares what you are paying today for each unit of earnings. For a resources focused business like Nittetsu Mining, this ratio often reflects how the market weighs current profit quality against the risks of commodity cycles, project execution and capital intensity.
Recent fundamentals give some context to that premium. Earnings grew 91.5% over the past year and have risen 10.2% per year over the past 5 years, and those profits are flagged as high quality. Earnings growth over the past year also exceeded the wider Metals and Mining industry, which recorded 26.1%.
Relative to peers, the valuation gap is clear. The 15.2x P/E is above the peer group average of 14.3x. It is also higher than the broader JP Metals and Mining industry average of 11.3x. This signals that the market is willing to pay more for Nittetsu Mining's earnings than for sector comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 15.2x (OVERVALUED)
Still, Nittetsu Mining relies heavily on copper and mining projects, so any setback in Arqueros execution or commodity pricing could quickly challenge that premium P/E story.
Find out about the key risks to this Nittetsu Mining narrative.
Another View: What The SWS DCF Says About Nittetsu Mining
The P/E premium tells one story, yet the SWS DCF model paints a very different picture for Nittetsu Mining. With the shares at ¥3,070 and an estimated future cash flow value of ¥956.03, this framework points to an overvalued stock where expectations already run high.
That gap raises a practical question for you: Is this a case where cash flow assumptions are too cautious, or has recent share price strength simply run ahead of what the underlying business can justify over time?
Look into how the SWS DCF model arrives at its fair value.
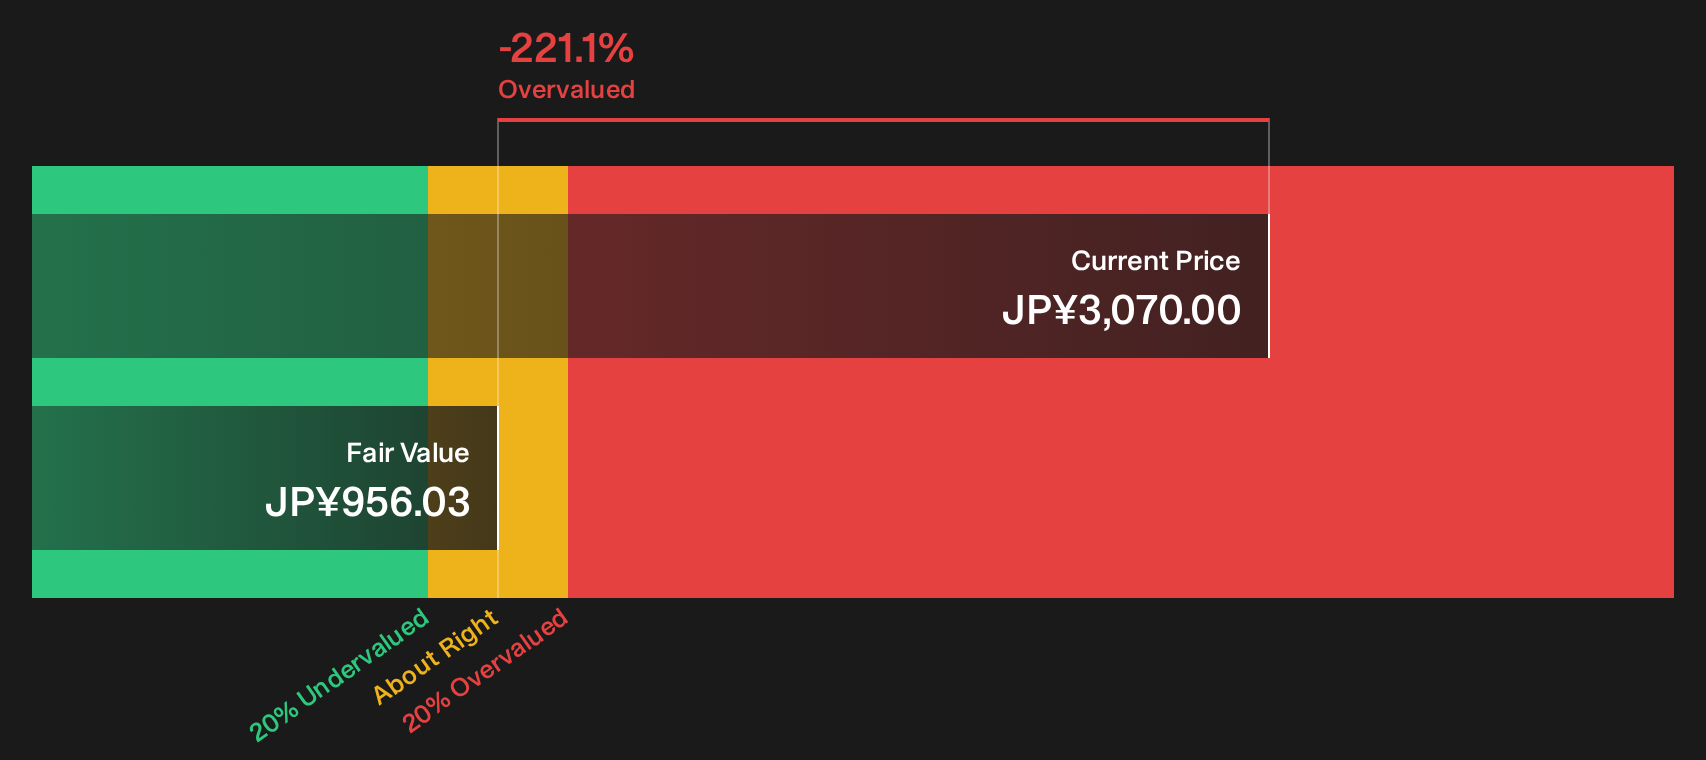
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nittetsu Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Nittetsu Mining can feel confusing, so consider reviewing the data for yourself and weighing both the upside and the downside. To see the balance of potential positives and areas of concern in one place, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Nittetsu Mining?
If Nittetsu Mining has sharpened your focus, do not stop here. The real edge comes from comparing several clear opportunities side by side using structured data.
- Target resilient income by scanning for high yielding payers built on solid fundamentals through the 28 dividend fortresses.
- Hunt for quality at a sensible price by checking the 13 high quality undervalued stocks that pair stronger balance sheets with attractive valuations.
- Spot tomorrow's potential leaders early by running through the 74 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com