


Is PagerDuty (PD) Overvalued After Its Earnings Beat And Customer Growth?
PagerDuty (PD) just posted earnings that beat revenue expectations, delivered solid operating income, and reported fresh customer additions, and the stock has climbed more than 24% since that announcement.
That earnings surprise did not land in a vacuum. PagerDuty’s recent 1-month share price return of 14.69% and 90-day share price return of 49.08% point to building momentum, even though the 5-year total shareholder return is still down 60.89%.
Scan how this PagerDuty move compares with other software players showing strong price and fundamentals momentum by reviewing the curated 20 high quality undiscovered gems.
Bulls see PagerDuty’s earnings beat, new customers and recent rally as a reset, while bears point to flat revenue, weak long term returns and modelled overvaluation. Which side does the valuation math support next?
Most Popular Narrative: 28% Overvalued
PagerDuty last closed at $16.16, compared with the most followed narrative fair value estimate of $12.64. That gap frames the current bull and bear tug-of-war around the stock.
The transition from seat-based to usage-based pricing models, validated by rapid growth in usage-based product lines (60%+ year-over-year) and strong initial customer feedback, aligns future topline growth more closely with actual customer value realization. This may set the stage to reaccelerate ARR growth and improve net retention as automation reduces per-seat dependency.
See why 18 investors see PagerDuty as 28% overvalued.
Result: Fair Value of $12.64 (OVERVALUED)
Still, customer downgrades tied to automation and the shift to usage based pricing could pressure PagerDuty’s revenue stability and make future cash flows harder to predict.
Find out about the key risks to this PagerDuty narrative.
Another View: PagerDuty Looks Cheap On Earnings
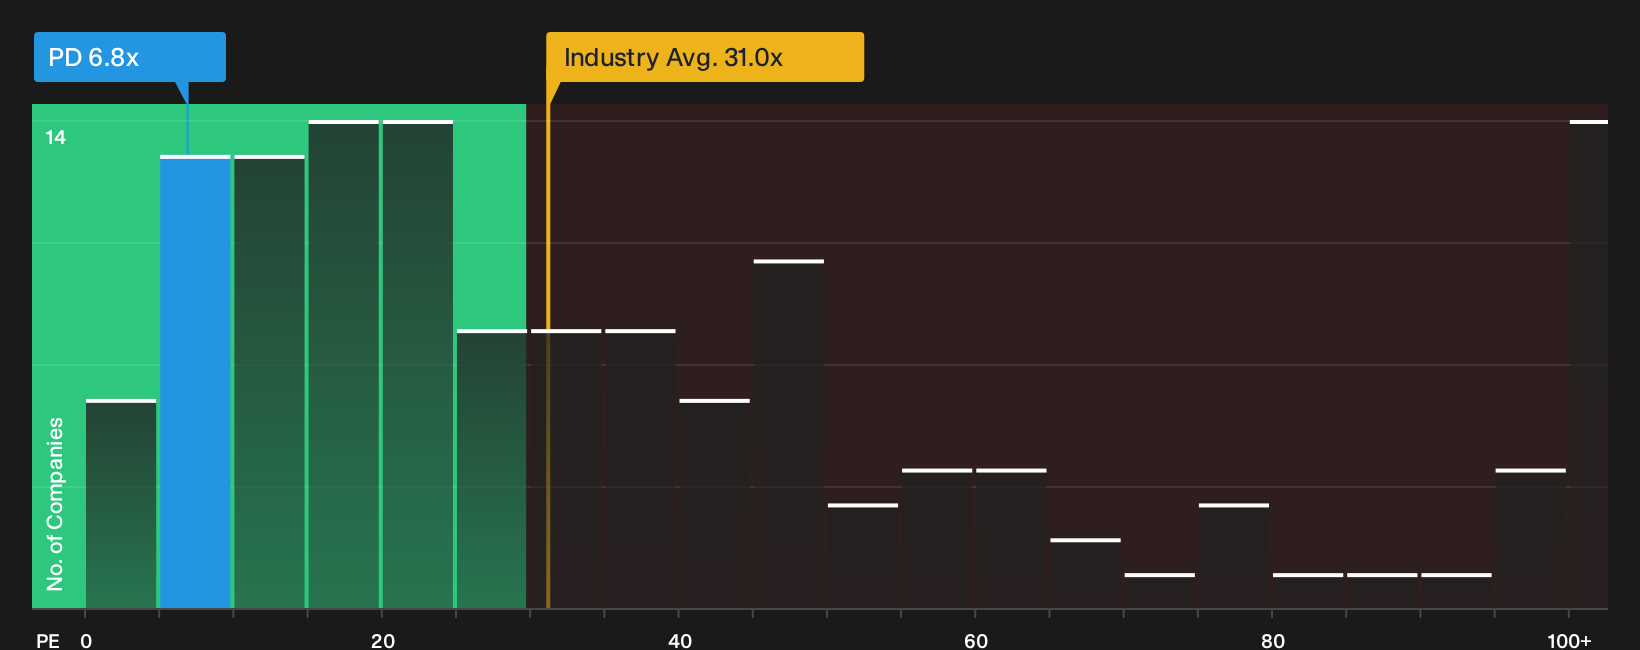
While the community narrative flags PagerDuty as 28% overvalued versus a $12.64 fair value, the current P/E of 6.8x tells a different story. That figure is far below both the US Software industry at 31x and peers at 51.7x, and only slightly above a fair ratio of 5.8x. For investors, that kind of gap can represent either a valuation cushion if earnings hold up or a warning that the market expects profits to fade. Which explanation fits best with your own read on PagerDuty’s future cash generation?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around PagerDuty can feel messy, yet that is exactly when fresh data matters most for your decision. To pressure test both the upside story and the risk case, start with the balance of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PagerDuty?
If PagerDuty has you rethinking where the real opportunities sit, do not stop at a single ticker. Broaden your watchlist with ideas shaped by clear financial filters.
- Target resilient balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Spot potential value gaps in quality businesses by reviewing the 29 high quality undervalued stocks.
- Prioritise capital protection and sleep-better-at-night holdings through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com