


Is Mitsubishi Materials (TSE:5711) Undervalued After Its Cutting Tools Sales Restructuring?
Mitsubishi Materials (TSE:5711) just approved a restructuring that folds its own and MOLDINO Tool Engineering’s domestic cutting tools sales into a single subsidiary, aiming to sharpen focus, accelerate decision-making, and provide more coherent customer support.
The Mitsubishi Materials share price has eased over the past month, with a 30 day share price return of 7.92% and a 7 day decline of 2.85%. Momentum over longer periods remains strong, given the 31.14% year to date share price gain and 72.40% 1 year total shareholder return, as investors weigh the restructuring news against an already powerful multi year total shareholder return of 148.74% over five years.
Compare how Mitsubishi Materials stacks up against peers making similar moves by running the curated 13 high quality undervalued stocks, which could be pricing in restructuring upside before it fully shows up in the numbers.
Mitsubishi Materials now trades at ¥4,839 while analyst targets and intrinsic value estimates point higher. How far away is a fair value anchor for this restructuring story?
Preferred P/E of 6.6x for Mitsubishi Materials: Is it justified?
The valuation gap on Mitsubishi Materials is clear. The last close at ¥4,839 screens as low relative to both its peers and the assessed fair P/E level implied by Simply Wall St's work.
The preferred yardstick here is the P/E ratio, which connects the share price to the profits that the group generates per share. For a cyclical resources and materials business like Mitsubishi Materials, this measure helps you judge what investors are willing to pay for current earnings in a sector where cash flows can swing sharply from year to year.
Mitsubishi Materials currently trades on a P/E of 6.6x. That sits materially below the Metals and Mining industry average of 11.3x and also below the peer group average of 11.4x. The internal fair P/E estimate is 14.8x, a level the market could move towards if sentiment on the earnings profile and balance of risks shifts closer to what this fair ratio implies.
Explore the SWS fair ratio for Mitsubishi Materials.
Result: Price-to-earnings of 6.6x (UNDERVALUED)
Still, the Mitsubishi Materials thesis can wobble if restructuring synergies prove slow or if earnings momentum fades while the share price already bakes in optimism.
Find out about the key risks to this Mitsubishi Materials narrative.
Another View on Mitsubishi Materials: DCF Signals A Much Bigger Gap
P/E makes Mitsubishi Materials look inexpensive, but the SWS DCF model goes further. At ¥4,839 against an estimated future cash flow value of ¥14,885.06, this framework presents the stock as very deeply undervalued. The question for you is whether that gap reflects caution or opportunity.
Look into how the SWS DCF model arrives at its fair value.
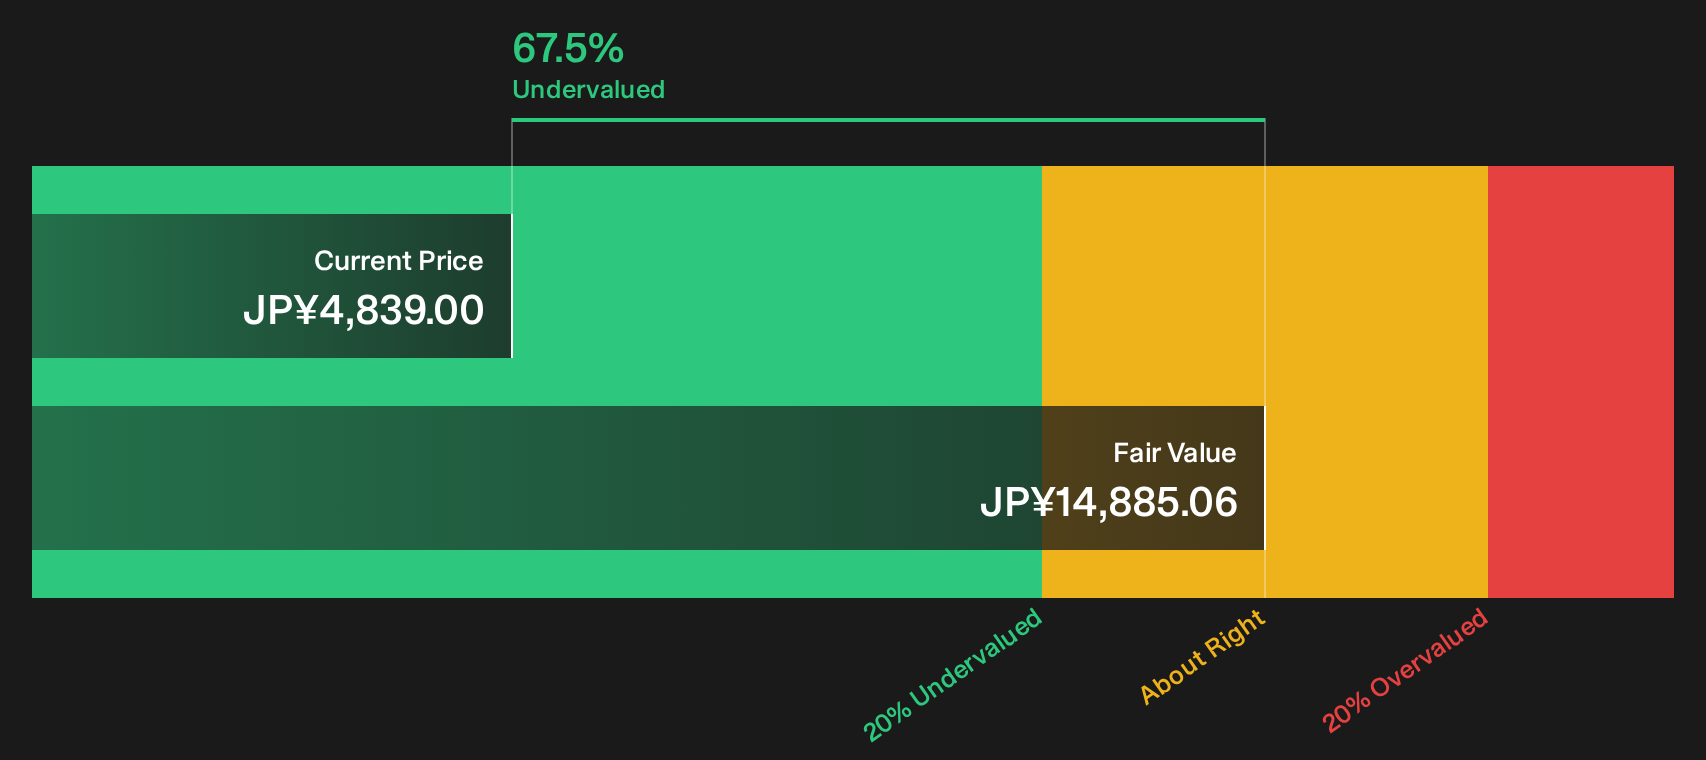
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether Mitsubishi Materials really justifies this kind of valuation debate? Act quickly, review the data, and weigh both the upside and the concerns by checking the 3 key rewards and 3 important warning signs.
Looking for more Mitsubishi Materials sized opportunities?
Do not stop with Mitsubishi Materials. Use the Simply Wall St screener to uncover fresh ideas that fit your return goals and risk comfort.
- Target potential mispricings by scanning a curated universe of companies that screen as attractively valued through the 13 high quality undervalued stocks.
- Strengthen capital protection by focusing on businesses with resilient finances using the list of solid balance sheet and fundamentals (23 results).
- Hunt for under followed prospects with strong fundamentals before the crowd pays attention through the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com