


ExlService Holdings (EXLS), Why Is It Getting Attention Today?
ExlService Holdings (EXLS) just rolled out a broad integration of agentic AI across its insurance and healthcare platforms, centering on the new EXL LifePRO Agentic Suite and upgraded payment integrity tools.
Against this product roll out, ExlService Holdings has seen mixed market sentiment, with the share price gaining 29.13% over the past 90 days. However, the year-to-date share price return is still down 10.73% and the 1-year total shareholder return is down 10.81%, while the 3-year total shareholder return of 26.34% points to momentum that has been stronger over a longer holding period.
Scan other AI-focused operators reshaping insurance and healthcare workflows by moving through our curated list of 34 healthcare AI stocks while you assess what ExlService Holdings is building here.
ExlService Holdings has rallied hard in recent weeks, yet the shares still sit well below both analyst targets and intrinsic value estimates. Does that spread signal opportunity, or a warning on where fair value really lies?
Most Popular Narrative: 100% Overvalued
The most followed narrative pegs ExlService Holdings at a fair value of $18.40, which sits well below the recent close of $36.79. That gap puts the spotlight squarely on how durable its AI and operations contracts really are.
Offshore analytics and managed-operations provider that runs mission-critical claims, underwriting, payment-integrity and finance workflows for large insurers, healthcare payers and banks, and is repositioning that base into data and AI-led delivery. Roughly 53% of revenue is recurring, embedded operations protected by 12 to 30 months of transition friction, which is enough to make permanent capital loss unlikely at a low entry price. It is not enough to underwrite compounding, five years of mix shift into AI-led work has produced no gross margin expansion, contracts are terminable without cause, and the AI work is re-won through pilots rather than inherited. The thesis is therefore a price thesis, not a quality thesis
See why 4 investors see ExlService Holdings as 100% overvalued.
Result: Fair Value of $18.40 (OVERVALUED)
Still, two pressure points could quickly change the ExlService Holdings story if they shift: client concentration around the top ten accounts and labor costs tied to India.
Find out about the key risks to this ExlService Holdings narrative.
Another View: What The SWS DCF Model Says About ExlService Holdings
The user narrative frames ExlService Holdings as 100% overvalued at a fair value of $18.40. The SWS DCF model points in the opposite direction. On that framework, EXLS at $36.79 is trading below an estimated future cash flow value of $81.12, which suggests the market might be underpricing its cash generation. Which story do you think fits the risk you are willing to take?
For readers who want to see how the cash flow assumptions stack up line by line, Look into how the SWS DCF model arrives at its fair value.
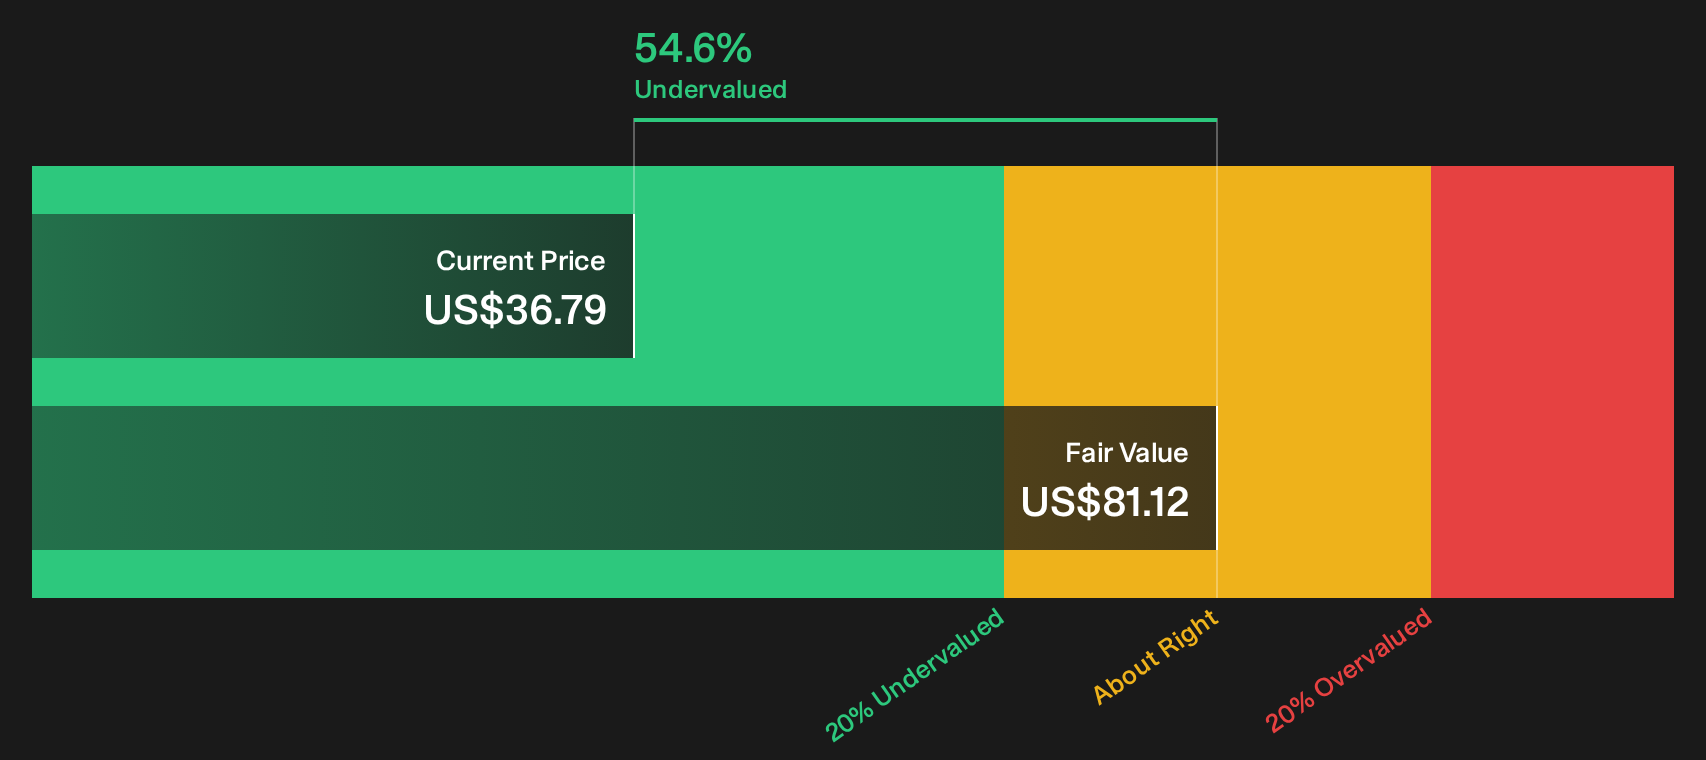
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ExlService Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution feels familiar, treat it as a prompt to pressure test the numbers yourself and move quickly from headline to hard data. To see what the current optimism is focused on, start with the 4 key rewards.
Looking for more ExlService Holdings investment ideas?
Use this as a springboard. If ExlService Holdings has you thinking harder about risk, reward and pricing, widen your search before the next move passes you by.
- Target stronger upside potential by scanning a curated pool of 29 high quality undervalued stocks that pair robust fundamentals with prices that may not fully reflect them yet.
- Prioritize resilience first and hunt through a 31 resilient stocks with low risk scores that focuses on businesses with steadier balance sheets and lower overall risk scores.
- Spot future contenders early and work through a 20 high quality undiscovered gems that surfaces under-the-radar companies with solid financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com