


How Investors May Respond To Volkswagen (XTRA:VOW3) EU China Hybrid Export Cut
- The European Union and China recently reached a preliminary deal to cut Chinese hybrid vehicle exports to Europe by more than half. This eases direct competitive pressure on Volkswagen in its key region as it prepares new affordable electric models and partnerships.
- The export reduction gives Volkswagen a clearer runway to test whether heavy spending on battery joint ventures and new EV architectures can translate into stronger pricing power and a more resilient earnings mix in Europe.
- The next focus is how Volkswagen's investment narrative around cost restructuring and EV transition interacts with reduced Chinese hybrid competition.
Compare how Volkswagen’s reset on Chinese hybrid competition stacks up against other potential turnaround stories by scanning our hand picked list of 178 high quality undervalued stocks.
Volkswagen Investment Narrative Recap
For Volkswagen to make sense in a portfolio, you need to believe the heavy lift on Future Plan 2030 and the EV shift can translate into cleaner earnings and healthier cash generation over time. The recent EU China hybrid export cut arguably helps the European pricing backdrop, but it does not remove the grind of restructuring or the pressure from weak China equity income.
Right now the near term swing factor is execution on cost cuts and model complexity, especially after the margin outlook for 2026 was reduced to up to 1% following sizeable writedowns and impairments. The biggest risk is that further restructuring charges, labour pushback or tougher Chinese conditions keep margins low and leave that earnings reset looking unfinished.
The BaFin fine of €1.2m for late disclosure on Volkswagen’s 2023 forecast looks small financially, yet it lands in the middle of ambitious turnaround plans and heavy capex on EVs and batteries. For a business leaning on large joint ventures and multi year projects, trust in guidance and disclosure quality becomes part of the investment thesis.
Investors already dealing with thin 1.6% net margins, high restructuring outlays and debt that is not well covered by operating cash flow now have one more governance watchpoint to track. Any repeat of disclosure issues could feed into scepticism around long term margin targets, which matters when execution on Future Plan 2030 and the battery JVs is the central catalyst.
Volkswagen's narrative projects €343.0b revenue and €12.7b earnings by 2029. This assumes 2.2% yearly revenue growth and an earnings increase of about €7.5b from €5.2b today.
Uncover why Volkswagen's fair value indicates a 55% potential upside to its current price, which could close faster than many investors expect.
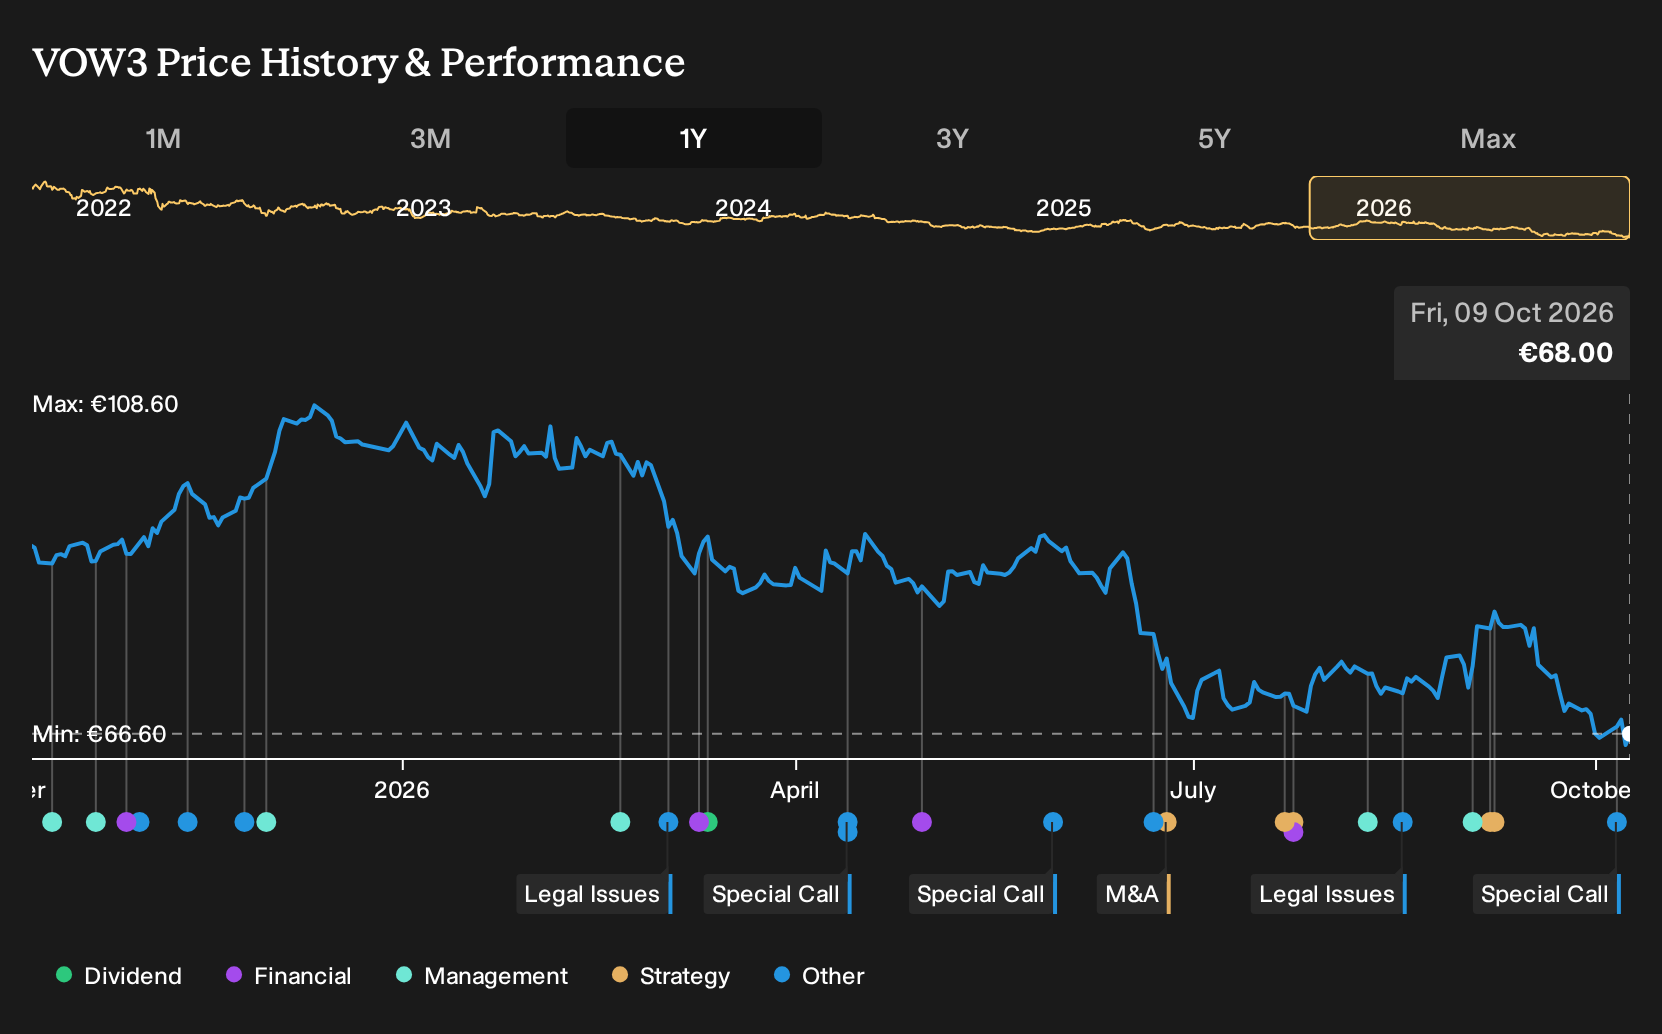
Exploring Other Perspectives
One alternate view focuses on tariffs as the real swing factor for Volkswagen. Before this export news, the most cautious analysts were working off roughly flat revenue expectations to 2029 and earnings of about €12.1b, with a low 3.8x P/E on those figures. You can compare that pessimism with today’s EU China deal and decide which narrative feels closer to your own read.
Explore 6 other Volkswagen fair value estimates, including one that suggests it could be worth just €84.54!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Volkswagen research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Volkswagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volkswagen's overall financial health at a glance.
Looking For More Ideas Beyond Volkswagen?
If Volkswagen's reset on hybrids has you rethinking your whole watchlist, it can help to line it up against other potential opportunities with very different risk and reward profiles.
- For investors who care most about quality and valuation together, scan a curated set of companies that screen well on both fronts with our 178 high quality undervalued stocks.
- If ballast and balance sheet strength matter more to you than excitement, focus on businesses with healthier financing and fundamentals using the list of solid balance sheet and fundamentals (204 results).
- For those hunting for smaller, under-followed situations where the story is still early, widen your search through a hand picked pool of 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com