


Innospec (IOSP) Dropped, So What Is Drawing Attention Now?
Argus recently lifted its price objective on Innospec (IOSP) to US$102, putting a spotlight on this specialty chemicals producer and its three segment model across performance chemicals, fuel additives, and oilfield services.
Recent trading has been choppy, with the share price slipping 2.1% on the day and 1.8% over the past week. Even so, Innospec still carries a 2.6% 1 month share price return and a 25.4% year to date gain, contributing to a 32.5% 1 year total shareholder return that indicates momentum has been building rather than fading.
Scan beyond Innospec and see how other specialty and materials stocks with solid fundamentals stack up in our hand picked list of solid balance sheet and fundamentals (25 results).
Innospec has already logged a solid run, yet the stock still trades below Argus’s US$102 target and an estimated intrinsic value. Do you lean into today’s price, or wait for a cleaner pullback before committing more capital?
Most Popular Narrative: 5.3% Undervalued
On the most followed view, Innospec’s fair value sits at $101 per share, a touch above the latest $95.65 close. This puts the focus squarely on execution rather than a bargain-bin price.
The thesis on Innospec has been reviewed and reaffirmed. The updated view now focuses more on execution around specific capacity, cash flow and emissions targets, rather than on broad end market growth themes.
Earlier views leaned on broad end market growth for sustainable chemicals and pricing power. The focus now is on specific execution milestones, such as the North Carolina plant repair, capacity uplift, and the effect on Performance Chemicals revenue and margins.
See why 3 investors see Innospec as 5% undervalued.
Result: Fair Value of $101 (UNDERVALUED)
Still, the Innospec narrative leans heavily on better cash generation and smooth plant operations. Setbacks on either front could quickly challenge that fair value story.
Find out about the key risks to this Innospec narrative.
Another View: Innospec Through The P/E Lens
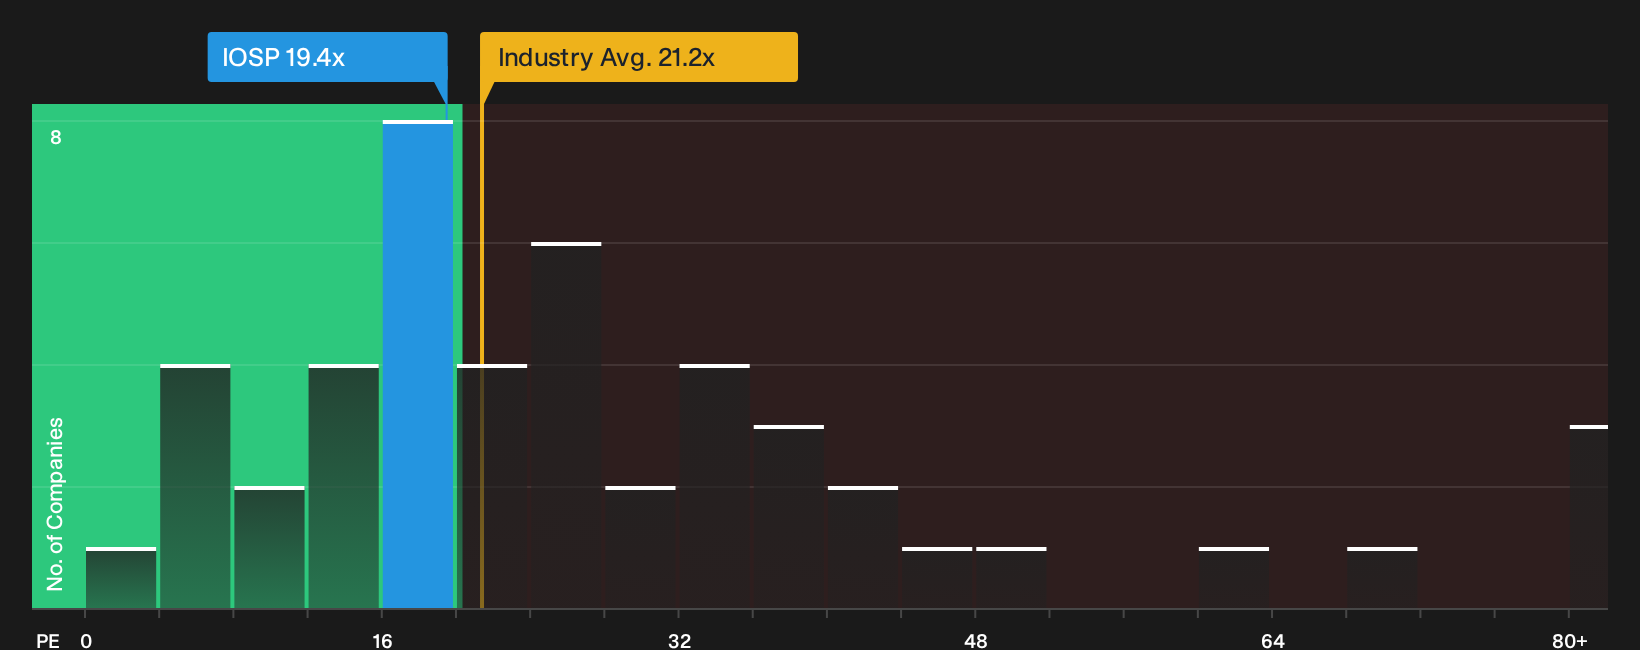
On a simple earnings multiple, Innospec looks less clear cut than the fair value narrative suggests. The stock trades on a 19.4x P/E against a fair ratio of 17.2x, while the US Chemicals group averages 21.2x and close peers sit around 44.8x. That mix of slight premium to the fair ratio yet discount to the wider sector hints at both some valuation risk and some relative cushion. Which side of that trade off feels more important to you right now?
For a closer look at how these earnings multiples tie back to business quality and pricing power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Innospec story so far, right? If you want to move quickly and base your stance on the underlying data, weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Innospec?
If you stop with Innospec, you risk missing other opportunities that fit your style, sector preferences, and risk comfort. Put a broader watchlist to work.
- Target potential mispricing and hunt for quality companies trading below their implied value using our curated 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on companies with robust yields and balance sheet support through the 8 dividend fortresses.
- Reduce volatility risk and focus on financially resilient businesses using the targeted 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com