


DICK'S Sporting Goods (DKS) Faces Lawsuit Pressure, Is It Still Above Fair Value?
DICK'S Sporting Goods (DKS) is back in focus after investors filed a class action lawsuit tied to its Foot Locker acquisition, arguing they were misled on inventory and promotional challenges.
DICK'S Sporting Goods now trades at US$136.65, with a 1-day share price return of 1.50% and a 90-day share price decline of 36.77% that has weighed on sentiment, even though the 3-year total shareholder return of 36.85% indicates longer term holders have still come out ahead.
Scan beyond DICK'S Sporting Goods and stress test your thesis against a curated set of retailers facing their own valuation reset in our 29 high quality undervalued stocks.
That 90 day slide sharpened the split view on DICK'S Sporting Goods, with bulls pointing to earnings power and bears focused on legal and Foot Locker risks. Which side does the current valuation lean toward?
Most Popular Narrative: 21.2% Overvalued
DICK'S Sporting Goods last closed at $136.65, while the most followed narrative pegs fair value at $112.77. The stock price currently sits well above that anchor in a way that sharpens the bull versus bear divide around Foot Locker and promotions.
Management's structural response to the guidance revision rests on a consistent rhetorical architecture. The DICK'S business is performing, the headwinds are real but temporary, the investments being made today are exactly the right investments. Each claim is internally defensible. Taken together, they produce a framework in which virtually any near-term result can be framed as consistent with long-term strategy. That is not an accusation, it is a description of how the communication is built.
See why 2 investors see DICK'S Sporting Goods as 21% overvalued.
Result: Fair Value of $112.77 (OVERVALUED)
Still, the Foot Locker earnings revision and the sharper promotional pressure on legacy footwear could both upend the current valuation story for DICK'S Sporting Goods.
Find out about the key risks to this DICK'S Sporting Goods narrative.
Another View On DICK'S Sporting Goods Valuation
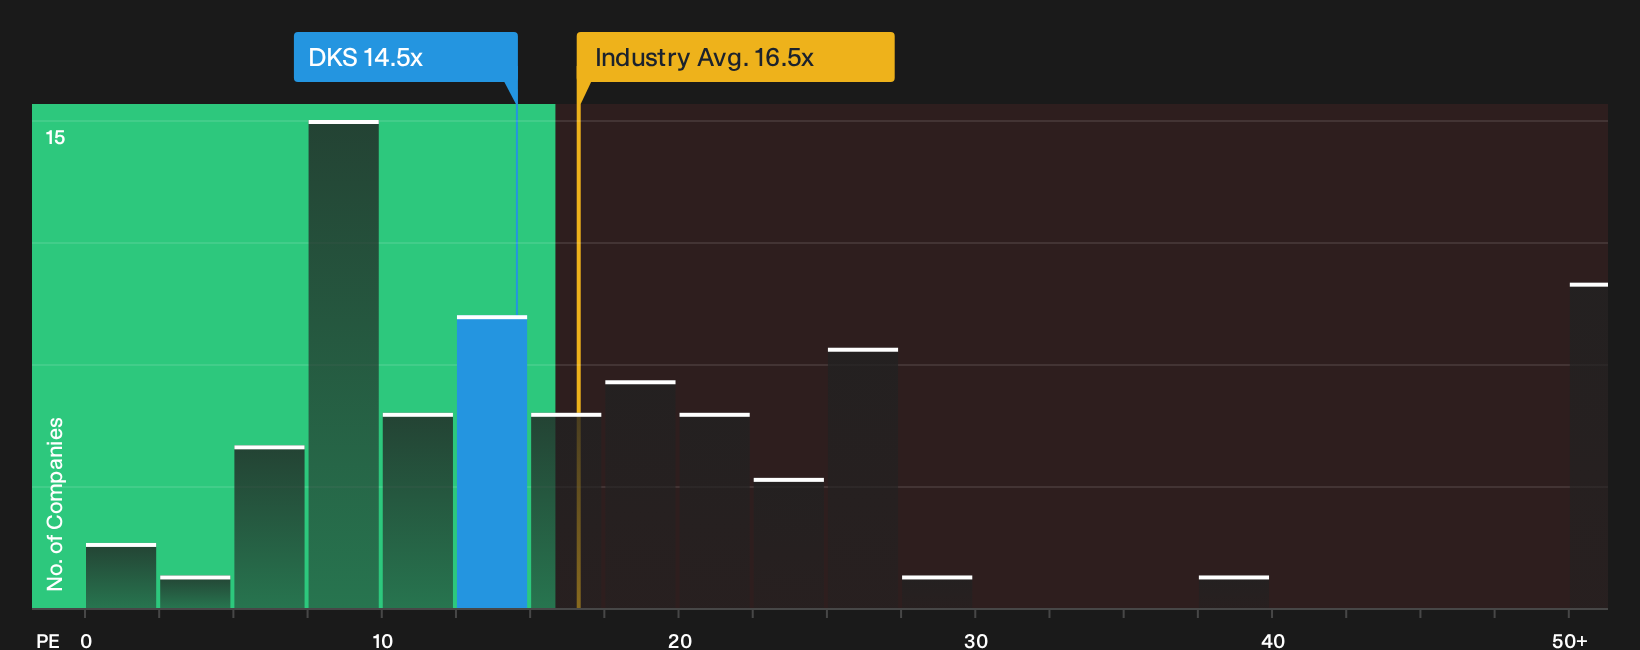
The most followed narrative flags DICK'S Sporting Goods as overvalued at $136.65 versus a fair value of $112.77. Yet on a simple P/E check, the picture shifts. DKS trades at 14.5x earnings compared with 16.5x for the US Specialty Retail industry and 21.1x for peers, while the fair ratio sits at 18.5x. That discount on earnings can either signal a margin of safety or reflect the lawsuit, Foot Locker drag and profit pressure the market is already pricing in. Which story do you think those gaps are really telling?
For a deeper look at how this earnings based view stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment like this around DICK'S Sporting Goods is exactly when your own work matters most, so take a close look at both sides and weigh the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond DICK'S Sporting Goods?
Do not stop with DICK'S Sporting Goods. Broaden your watchlist with a few focused screens that can surface opportunities you might otherwise miss.
- Target resilient payers by reviewing a curated group of income ideas in the 8 dividend fortresses.
- Hunt for mispriced quality by scanning the 20 high quality undiscovered gems that many investors are not watching yet.
- Cut downside risk by focusing on financially sturdy businesses highlighted in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com