


Wendel (ENXTPA:MF) Hires New Product Chief Following Push Into Asset Management Growth And Fair Value Debate
Wendel (ENXTPA:MF) has moved into focus after appointing Bénédicte Rabier as Chief Product Officer for Wendel Investment Managers, a hire aimed at sharpening product design and expanding third party asset management.
Recent trading suggests interest in Wendel is rebuilding, with the share price at €79.35 after a 1-day share price return of 1.34% and a 7-day share price return of 2.65%. However, the 30-day share price return is down 4.74% and, year to date, the share price has slipped 2.82%, while the 1-year total shareholder return of 2.95% and 3-year total shareholder return of 26.71% point to steadier gains over a longer horizon.
Scan how Wendel compares with other asset managers repositioning for product led growth by reviewing our curated list of 178 high quality undervalued stocks.
Wendel is reshaping its asset management arm just as the share price has drifted, which puts you at a fork in the road: step in after this product pivot, or wait for a different entry point as the valuation picture comes into focus next?
Most Popular Narrative: 26% Undervalued
On the most followed view of Wendel, a fair value of €106.67 sits well above the last close at €79.35. This puts recent price action in the shadow of longer term expectations built on its asset management build out.
Expansion of third-party assets under management, combined with a significant pipeline of undeployed capital and new product initiatives (retail fund offerings, European private credit), is set to increase fee-paying AuM, supporting top-line growth and earnings visibility for the asset management division.
See why 5 investors see Wendel as 26% undervalued.
Result: Fair Value of €106.67 (UNDERVALUED)
Still, the consensus story on Wendel can break if fundraising slows at Monroe or IK, or if key unlisted holdings like Stahl and Scalian continue to underperform.
Find out about the key risks to this Wendel narrative.
Another View On Wendel’s Valuation
The popular story has Wendel trading well below an estimated fair value of €106.67. Our DCF model points in a different direction. On this view, the share price of €79.35 sits above an estimated future cash flow value of €61.04, which screens as overvalued. That split raises a simple question: Which set of assumptions do you trust more, the asset growth narrative or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
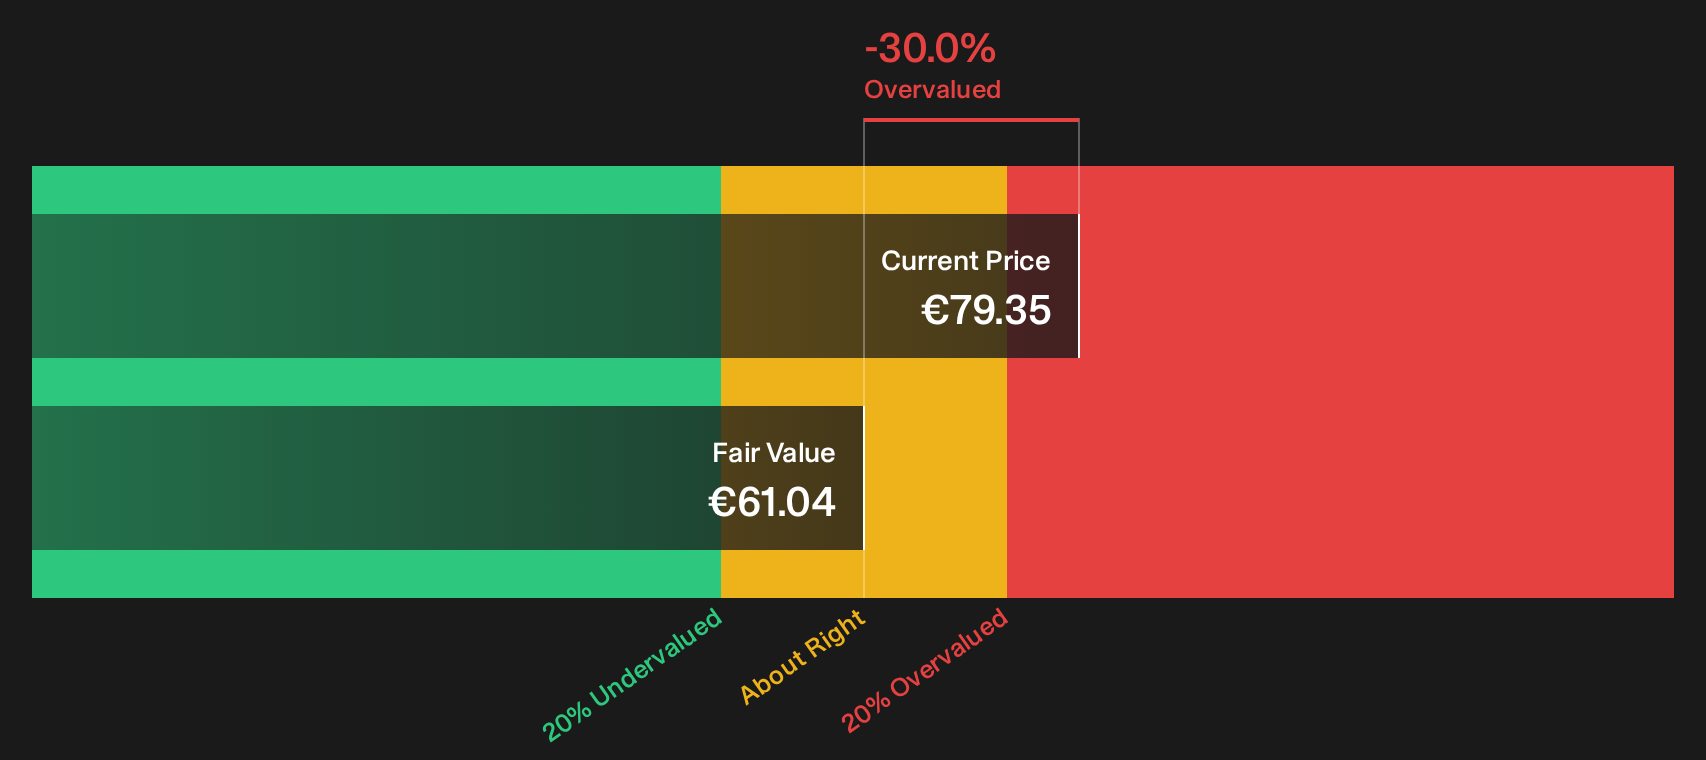
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wendel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in Wendel’s story so far. If you want to move before sentiment shifts again, consider the balance between its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Wendel?
If you stop with Wendel, you only see one angle. Broaden your watchlist now so you are not chasing opportunities after everyone else spots them.
- Target quality at a discount by scanning companies on our 178 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them yet.
- Build a steadier income stream by reviewing the 223 dividend fortresses that currently provide higher yields with a focus on resilience.
- Strengthen your core holdings by focusing on financially robust businesses through the list of solid balance sheet and fundamentals (204 results) that can better absorb shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com