


Learn Why The Bull Case For Chevron Stock Could Change Following Gulf Production Shutdowns
- Chevron temporarily shut offshore platforms and faced refinery risk in the Gulf of Mexico as Hurricane Isaias disrupted regional oil and fuel supply.
- The storm related outages combined with a Gulf tanker attack tightened crude availability, highlighting how sensitive Chevron’s earnings are to sudden supply shocks.
- We will now look at how Chevron's investment narrative is affected by hurricane related shutdowns that tightened oil supply and pricing.
Scan how Chevron reacts to this supply shock, then size up other energy producers facing similar weather and policy risks using the curated list of 29 high quality undervalued stocks in the sector.
Chevron Investment Narrative Recap
An investor in Chevron needs to be comfortable with a large, integrated energy business that leans on low cost upstream barrels, a wide refining footprint and long dated projects in places like Venezuela. The short term swing factor right now is commodity pricing around these hurricane related supply shocks, which may help near term cash generation but does not change the long term thesis.
The biggest risk remains how fast energy demand shifts away from hydrocarbons compared with how quickly Chevron’s lower carbon and power projects scale. Current refinery and offshore disruptions look operational rather than structural. The more important test is execution on cost programs, Hess integration and disciplined capital spending.
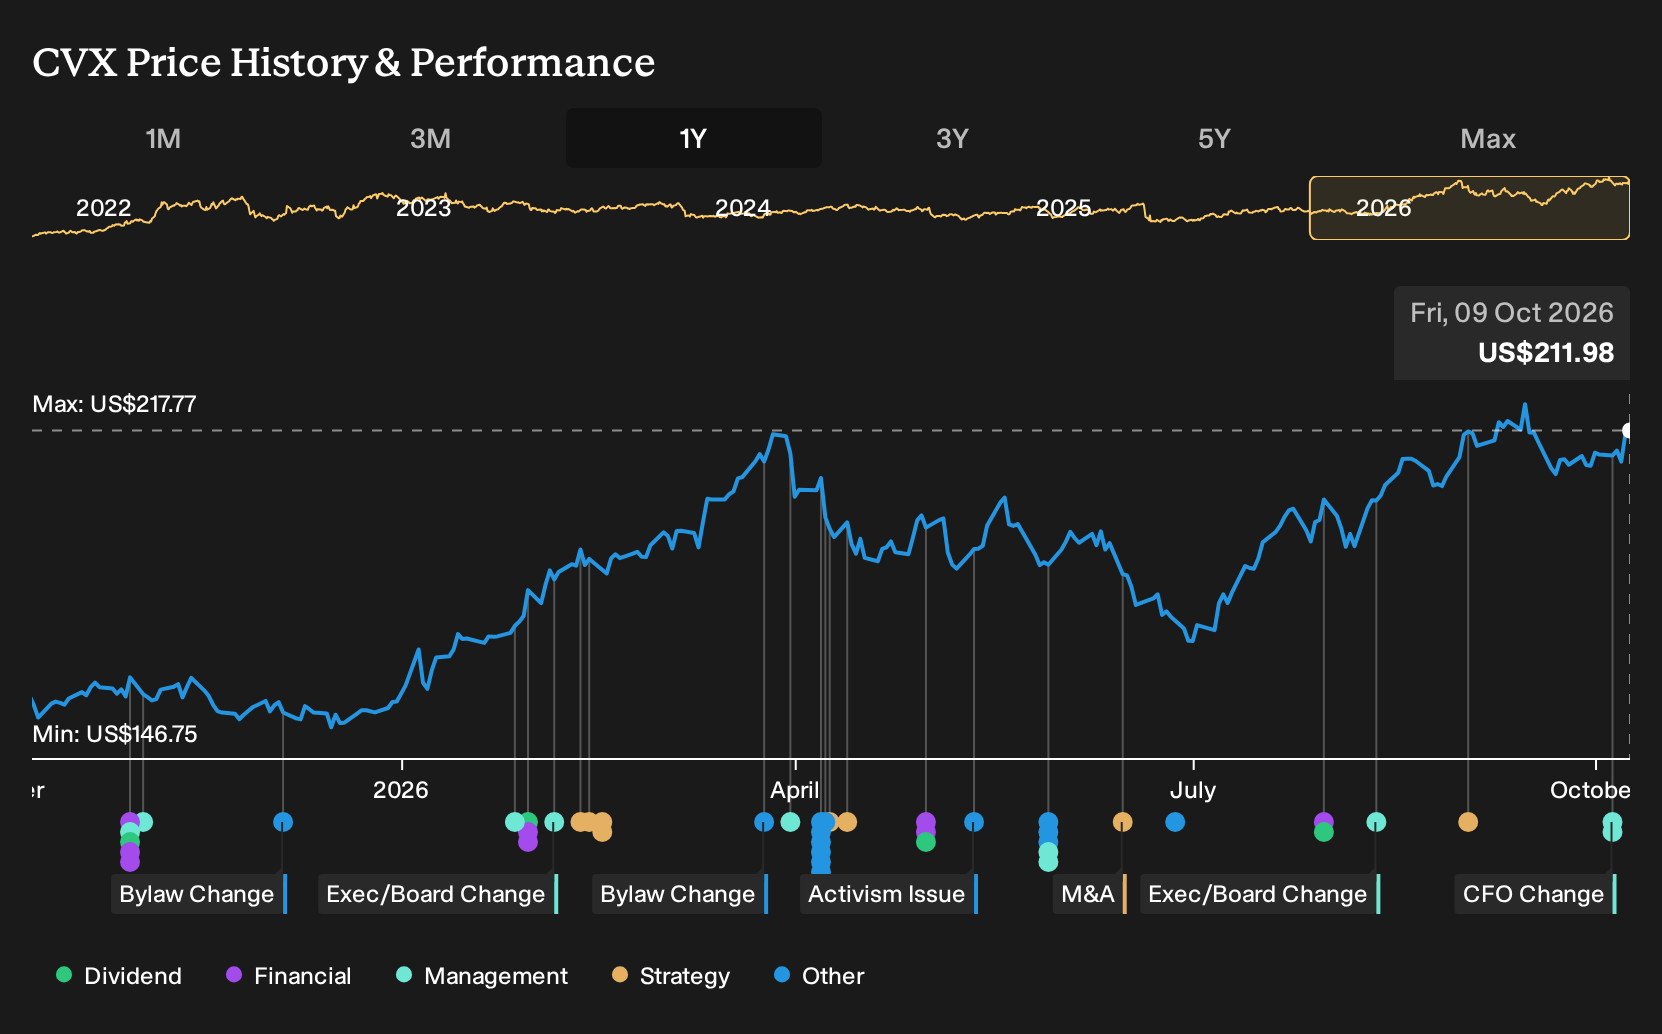
The most relevant recent development for this storm driven story is the leadership reshuffle around finance and operations. From 1 January 2027, Jeff Gustavson becomes CFO while current CFO Eimear Bonner moves to president, Oil, Products & Gas, taking direct responsibility for safe operations, capital discipline and value chain optimization.
That matters for investors watching hurricanes, regulatory changes and midstream deals play through the P&L. The new setup concentrates operational accountability with Bonner and global financial stewardship with Gustavson. He has experience across M&A, planning and New Energies. Execution on refinery reliability, cost control and lower carbon projects will help determine how Chevron absorbs future shocks similar to Hurricane Isaias.
What The Current Chevron Forecasts Assume
Chevron's outlook baked into current analyst models is fairly specific. Analysts are pencilling in a 1.6% yearly revenue decline over the next three years, steadying the top line rather than chasing aggressive expansion. Earnings today are estimated at US$20.6b and the same group expects profit to reach US$25.3b by 2029, which is about a US$4.7b increase on current levels. The story behind that gap is less about sales growth and more about margins, with forecasts for profit margins to move from 9.8% today to 12.7% in roughly three years as cost programs, refinery reliability and Hess integration feed through.
Chevron's narrative projects US$199.4b revenue and US$25.3b earnings by 2029. This assumes a 1.6% yearly revenue decline and about a US$4.7b earnings increase from the current US$20.6b base.
Those numbers also imply a valuation test that matters for anyone tracking hurricane related supply shocks. To line up with the analyst targets, the stock would need to trade on a P/E of 20.1x on 2029 earnings, compared with 19.4x today and above the 13.5x level quoted for the wider US oil and gas group. That gap suggests the market is being asked to pay a premium multiple for Chevron's integrated model, cost work and long duration projects, even while headline revenue is forecast to drift lower.
For investors watching Hurricane Isaias disruptions and future storms, the key question is how those events interact with this margin heavy setup. Weather driven outages, tanker incidents and refinery downtime can tighten physical supply and influence pricing, but the analyst path depends more on management holding the line on costs, lifting refinery utilization over time and keeping big capital projects on schedule. If those levers do not track the current script, the projected move from US$20.6b to US$25.3b in earnings by 2029 becomes harder to justify on a 20.1x multiple.
Uncover why Chevron's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only provides three Chevron fair value estimates, yet they span from about US$223 to US$352 per share, so private investors are clearly split on where the stock should trade. Set those wide ranges against hurricane related outages, shifting methane rules and leadership changes in finance and New Energies, then weigh how differently future cash flows could play out.
Explore 2 other Chevron fair value estimates, including one that suggests it could be worth just $222.67.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Chevron research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Chevron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Chevron's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chevron?
Once you have a handle on how Chevron reacts to storms, refinery issues and shifting regulation, it can be useful to line that up against other businesses with very different risk profiles. The Simply Wall St Screener lets you scan for stocks that better match your own tolerance for volatility, income needs and balance sheet comfort.
- If you want potential growth with tighter filters on quality, review a curated set of smaller opportunities through the 20 high quality undiscovered gems.
- For readers who care most about resilience and capital preservation, focus on companies that pass strict risk checks by using the 31 resilient stocks with low risk scores.
- If financial strength matters more than headline stories, concentrate on businesses with cleaner balance sheets and consistent fundamentals via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com