


Is Viavi Solutions (VIAV) Fully Valued As New Testing Products Fuel Its Growth Story?
Viavi Solutions (VIAV) is back in focus after two closely related product moves: an expanded testing partnership with Calnex Solutions and the launch of the compact CyberFlood CF50 platform for high-capacity application, security and AI workload testing.
Those testing moves come at a time when Viavi Solutions has already drawn attention in the market, with the share price at US$45.46 after a 1-day share price return of 3.11%, a 30-day share price return of 17.32% and a year-to-date share price return of 150.47%, alongside a 1-year total shareholder return of 270.50% that reflects the strong longer term momentum behind the stock.
Scan Viavi Solutions' peers riding the same network testing and AI workload momentum by zeroing in on our hand-picked 92 AI infrastructure stocks for potential candidates.
Viavi Solutions now appears to be a stronger testing platform business than it was a year ago. After a share price move this sharp, the key question is whether that quality is being fairly valued or is already fully reflected in the price.
Most Popular Narrative: 26% Undervalued
Analysts following Viavi Solutions see more upside than the current $45.46 share price suggests, with their fair value estimate anchored at $61.43 and tied directly to long term earnings and margin assumptions.
Viavi is experiencing robust and sustained demand across the data center ecosystem, with customers updating optical connectivity to 400G, 800G, and now 1.6T enabling multi-year upgrade cycles and expanding its total addressable market, which should drive structural revenue growth through 2026 and beyond.
See why 15 investors see Viavi Solutions as 26% undervalued.
The widely followed narrative builds its $61.43 fair value using an 8.93% discount rate and a detailed set of revenue and earnings forecasts. Revenue is modeled to reach $2.5b by 2029, with profits moving from a loss of $30.4m today to earnings of $503.0m, implying a future P/E of 46.3x on those projected earnings.
That view also leans heavily on the idea that Viavi Solutions can shift from a telecom heavy exposure to a mix that includes aerospace, defense and data centers, while lifting profit margins from a net loss position to 20.1%. In addition, analysts factor in share count growth of 7.0% per year over the next 3 years and still arrive at a fair value that sits well ahead of the current share price.
None of this is risk free. The same narrative flags cyclicality in service provider spending, integration risk around recent acquisitions and a balance sheet funded entirely by higher risk borrowing, plus new term loan debt. It also points to geopolitical exposure in manufacturing hubs such as China, Thailand and Vietnam, and to pressure in wireless infrastructure testing if large equipment vendors continue to delay spending.
For readers, the real question is whether those long range margin and earnings targets feel realistic given Viavi Solutions' current loss making status and the recent reduction in modeled fair value from $64.43 to $61.43 as growth and margin assumptions were softened. The 26% gap between that updated estimate and the live market price is only meaningful if you are comfortable with the path to $503.0m of earnings and a P/E multiple above the current US Communications industry level.
Result: Fair Value of $61.43 (UNDERVALUED)
Still, the bullish Viavi Solutions story can unravel quickly if wireless test demand stays weak or if new, debt-funded acquisitions fail to integrate cleanly.
Find out about the key risks to this Viavi Solutions narrative.
Another View: Viavi Solutions Looks Expensive On Sales
The 26% analyst upside story for Viavi Solutions meets a very different signal when you look at the current P/S ratio. The stock trades on 7.4x sales, which is much richer than the US Communications sector at 2.3x and still above a ratio of 8x that the market could move toward, leaving less room if sentiment cools again.
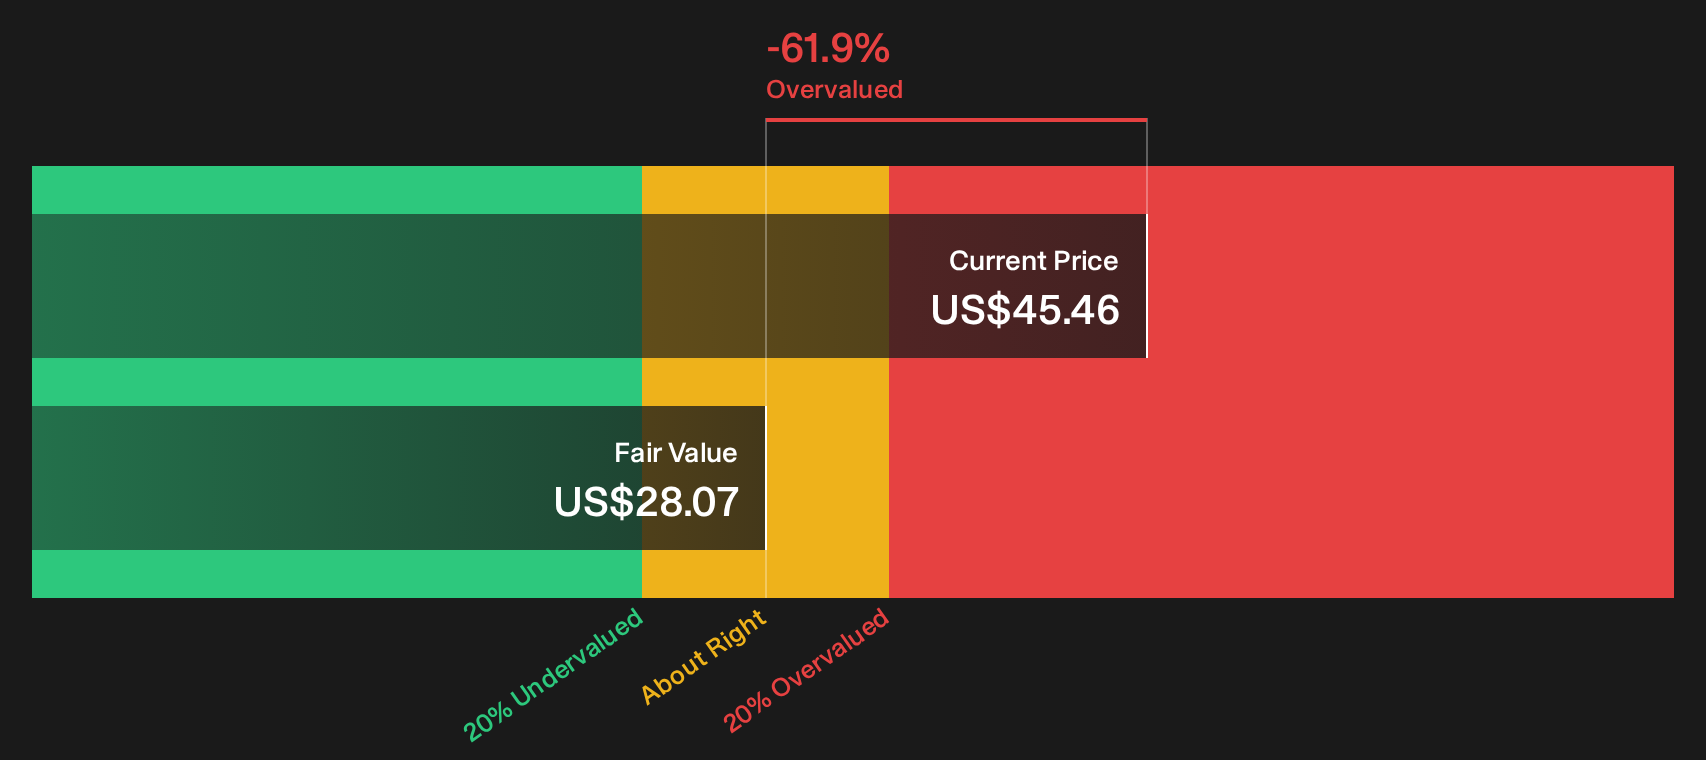
Our DCF model also points a different way, with Viavi Solutions at $45.46 compared with an estimated future cash flow value of $28.07. This screens as overvalued on that lens and raises a simple question for investors: Which set of assumptions do you trust more, the earnings narrative or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Viavi Solutions is clearly split. This is exactly why you should move quickly, review the underlying data yourself and weigh both the upside and the warning flags highlighted in the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Viavi Solutions?
If Viavi Solutions has sharpened your focus, do not stop here. Broaden your opportunity set with targeted lists that surface very different kinds of potential candidates.
- Target potential mispricings by scanning companies that combine quality and value through the 29 high quality undervalued stocks.
- Prioritise resilience by sizing up businesses that feature strong financial footing using the list of solid balance sheet and fundamentals (25 results).
- Hunt for off-the-radar potential by checking out a curated pool of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com