


Is International Bancshares (IBOC) Undervalued After Its Recent Pullback?
International Bancshares (IBOC) has drawn attention after recent price weakness, with the share price down over the month and over the past 3 months, even as longer term total returns remain positive.
Short term momentum for International Bancshares has cooled, with the share price down 4.3% over the past month and 10.5% over 3 months. However, the 1-year total shareholder return of 5.4% and 3-year total shareholder return of 71.2% point to a still resilient longer term record.
See how International Bancshares compares to other resilient financials by checking a curated group of 31 resilient stocks with low risk scores.
Bulls see recent weakness in International Bancshares as a chance to buy a solid regional bank on sale. Bears argue the pullback is a warning, not an opportunity. Which case does the current valuation lean toward next?
Price-to-Earnings of 10.2x: Is it justified?
On a simple earnings yardstick, International Bancshares looks inexpensive. The stock trades on a P/E of 10.2x while the peer group averages 19.7x, and the broader US Banks industry sits at 11.4x.
The P/E ratio tells you what investors are willing to pay today for each dollar of current profits. For a regional bank like International Bancshares, this depends on how durable its earnings are, how it manages credit risk, and how shareholders view its long run profitability.
International Bancshares carries some clear positives for that earnings stream. The business reports high quality earnings and has grown profits by 12.2% per year over the past 5 years, even though the most recent year showed a slower 0.3% outcome and a small step down in net profit margin from 50.9% to 49.3%. The trade off is that return on equity sits at 12.2%, which is classified as low, and the bank has a high level of bad loans at 3% with a 57% allowance, which may justify some investor caution around the headline discount.
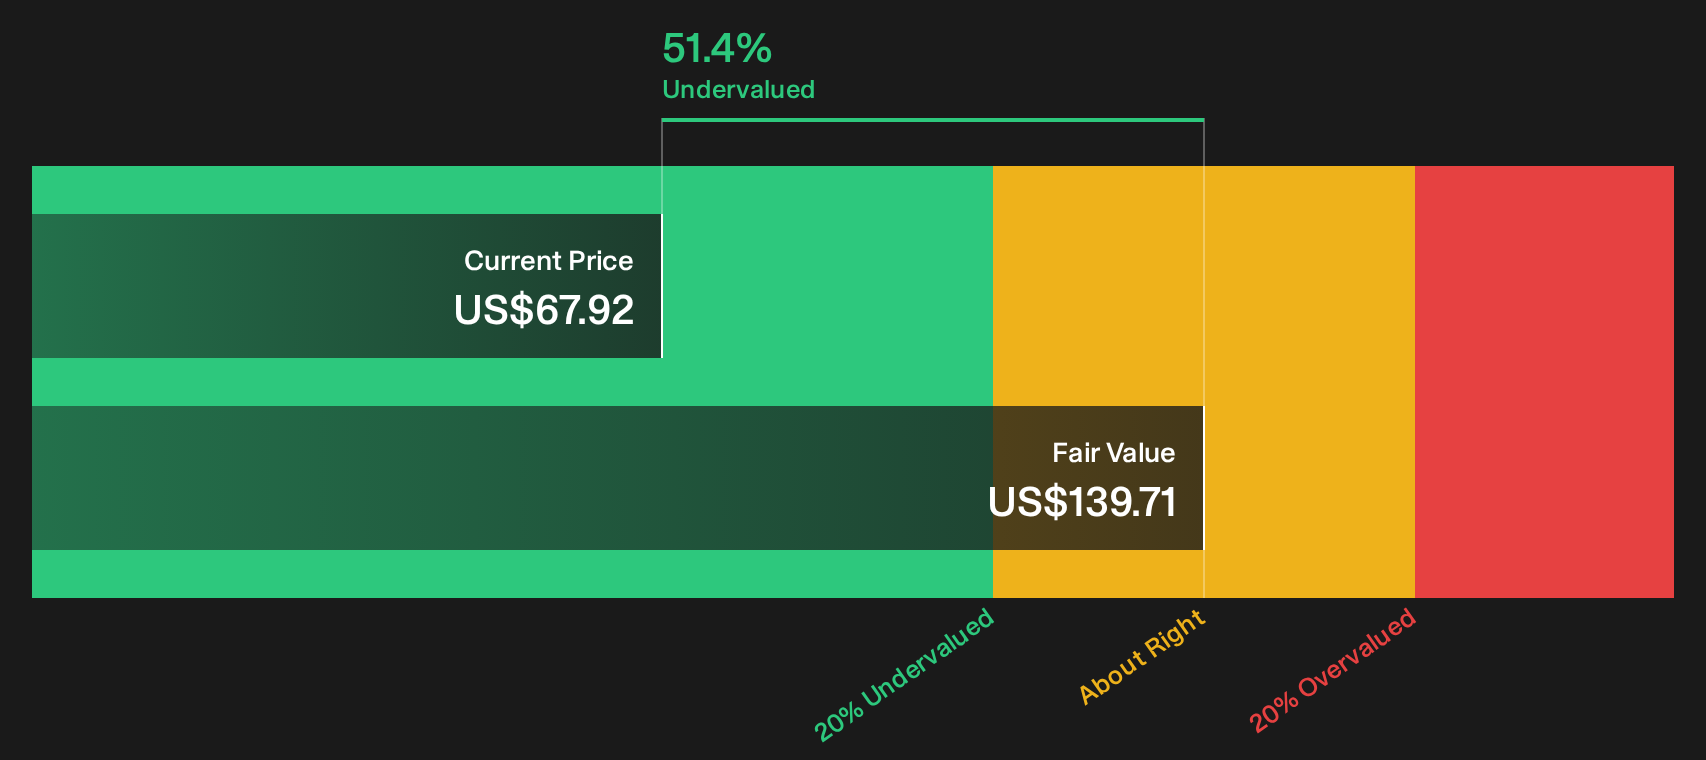
Compared with US Banks overall, a P/E of 10.2x is not just slightly cheaper. It sits below both the industry level of 11.4x and the peer average of 19.7x, which is strong relative value on this single metric. The SWS DCF model also indicates the shares trade well below an estimated future cash flow value of $139.71, or around 51.4% below that internal fair value marker.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 10.2x (UNDERVALUED)
Still, elevated bad loans and a lower return on equity at International Bancshares could quickly pressure that discount if credit conditions or profitability weaken further.
Find out about the key risks to this International Bancshares narrative.
Another View: What If The DCF Has It Wrong?
The earlier P/E workup presents International Bancshares as relatively inexpensive, but the SWS DCF model is even more generous. That approach puts fair value near $139.71 per share, which is well above the current $67.92 price and indicates a very wide margin between market price and model value.
DCF outputs always rest on long term cash flow assumptions, and small changes to those inputs can shift fair value significantly. For an investor reading this today, the useful question is whether that gap reflects opportunity or simply optimistic cash flow expectations that are hard to rely on.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out International Bancshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around International Bancshares can make the story feel murky, so consider reviewing the key numbers yourself and weighing both sides. To see a single view of the main concerns alongside the potential bright spots, start with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond International Bancshares?
If International Bancshares has you thinking more carefully about value and risk, use that focus to hunt for other opportunities that match your own checklist.
- Target durable balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center.
- Hunt for potential mispricings by running through a focused list of 29 high quality undervalued stocks that pair quality metrics with attractive valuations.
- Build a cash flow focused watchlist by zeroing in on 8 dividend fortresses designed for investors who care about income as much as price moves.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com