


This Nvidia Partner Was My Top Pick for 2026, and It's Up 43%: Here's Why It's Still a Great Value Now
Key Points
ON Semiconductor is poised for strong growth in EVs and industrial applications, including physical AI and AI data centers.
Management projects significant growth in revenue and free cash flow through 2030.
The Synaptics acquisition could further boost ON's role in physical AI markets.
ON Semiconductor (NASDAQ: ON) was a great value going into 2026, and despite the 43% rise in 2026, it's arguably still one now. The investment case for the stock rests on the idea that its current core exposure to electric vehicles (EVs) and industrial applications implies ongoing growth.
Meanwhile, it has a fast-growing exposure to AI data center infrastructure, including a key partnership with Nvidia (NASDAQ: NVDA). Equally important, long-term growth comes from its exposure to physical AI.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
ON Semiconductor is an AI stock now
The company is best known for its power and sensing chips, which are primarily sold into the automotive market (mainly electric vehicles) and to a wide range of industrial customers (EV infrastructure, industrial automation, motor control, robotics, etc.). Its power solutions enable lightweight, long-range EVs, and its sensing technology is used in advanced driver assistance systems (ADAS).
Its "other" end market is what management lumps in everything else. Usually, "other" would be something of an afterthought. Still, its fast-growing data center business is included, and it is largely responsible for the fast-growing revenue you can see in the chart.
Management expects its data center revenue to double to $500 million in 2026, and "we have visibility into 2027 where this business is going to double again," according to Achyut Shah, president of its power solutions group, in the recent investor day presentation.
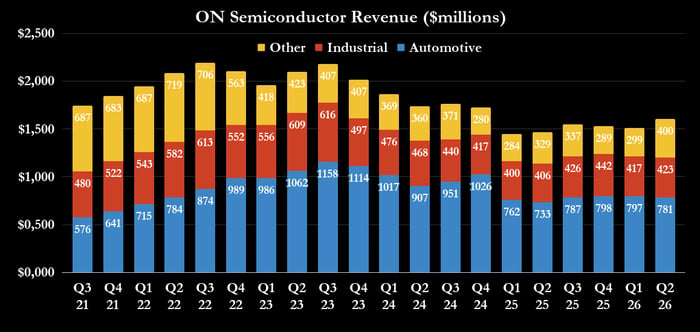
Data source: ON Semiconductor presentations. Chart by the author.
In fact, management expects its end markets to grow at the following compound annual growth rate (CAGR) from 2026 to 2030:
- Automotive to grow at a 9% CAGR, driven by electrification, ADAS/autonomy, and software-defined vehicles -- secular megatrends that enable growth
- Industrial to grow at a 10% CAGR, with 40% of its revenue driven by traditional industrial applications and 60% driven by secular growth trends connected with AI, such as high voltage power grid infrastructure and physical AI
- AI data center to grow at more than 50%, driven by growth in power technology in AI data centers, including its partnership with Nvidia to develop power solutions for new 800-volt direct current (VDC) data centers starting next year.
All told, management expects an overall revenue CAGR of 12% to 14% from 2026 to 2030, with operating income increasing at a 30% CAGR, and free cash flow (FCF) more than doubling to $3.5 billion in 2030.
For argument's sake, and taking a very conservative valuation benchmark of 20 times FCF, ON Semiconductor could trade at $180 in 2030, implying an annual return of slightly more than 20% on the stock.
Image source: Getty Images.
ON Semiconductor's growth is just getting started.
Moreover, these forecasts don't include any impact from the Synaptics (NASDAQ: SYNA) acquisition, which management hopes to close in mid-2027. The acquisition ties in with the long–term growth trend of physical AI, likely to lead to another kick in its growth in the future.
Simply put, ON Semiconductor already has the intelligent power, sensing, and control chips to be a major player in the physical AI market, and with Synaptics, it will add the computing power for AI edge applications. Consider physical AI products like robots and autonomous driving that require power density to operate, computing power to run AI models in real time, and sensing and control functions to gather data.
Physical AI is a long-term growth market that will continue to accelerate after the AI data center infrastructure market's growth starts to slow, following the enormous build-out underway.

Image source: Getty Images.
A stock to buy
The company's core end markets are cyclical, and in the semiconductor market, that can mean brutal swings in demand and pricing. As such, the company is definitely not immune to risk. On the other hand, within that cyclicality, there's a strong undercurrent of the secular growth trends (electrification, AI data centers, physical AI, automation, etc.).
It all positions ON Semiconductor to win out in the medium- and long term, as these secular trends are unlikely to go away anytime soon, and ultimately drive its growth higher over the long term.
Lee Samaha has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Nvidia. The Motley Fool recommends ON Semiconductor and Synaptics. The Motley Fool has a disclosure policy.