


Clorox (CLX) Launches Purell ProCare As The Market Weighs Its Fair Value
Clorox (CLX) just rolled out Clorox Purell ProCare, a new health and hygiene platform that combines its CloroxPro unit with GOJO, the Purell maker it acquired earlier this year.
Against that launch, Clorox shares trade at US$83.80. The 7 day share price return of 4.2% offers a brief rebound after the share price fell 4.5% over 30 days and the 1 year total shareholder return declined 27%.
Scan how Clorox compares with other established consumer and hygiene companies by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
So after that sharp slide and brief bounce, do you lean into Clorox at today’s price, or hold cash and wait for a deeper reset as the valuation picture comes into focus next?
Most Popular Narrative: 16.8% Undervalued
Against the last close at $83.80, the most followed narrative on Clorox anchors on a fair value estimate of $100.76, which points to a meaningful valuation gap that investors are actively debating rather than ignoring.
The main thing that has to go right is that Clorox turns its larger health and hygiene platform, including GOJO and Clorox Healthcare, into sustained growth and profitability while managing persistent cost inflation and value seeking consumer behavior.
The current valuation implies investors are pricing Clorox as if margin pressure, muted category growth, and legal or governance overhangs will weigh more heavily on the share price than the potential upside from health and hygiene growth, ERP driven productivity, and GOJO accretion.
See why 44 investors see Clorox as 17% undervalued.
That framework uses a 7.24% discount rate and a fair value of $100.76 for Clorox, which sits above both the current $83.80 trading level and the analyst consensus target of about $100.76, so it captures a view that the market is treating category pressure and cost inflation more harshly than the forecast improvement in earnings and cash generation coming from ERP and the enlarged health and hygiene platform.
Result: Fair Value of $100.76 (UNDERVALUED)
Still, the narrative can break if input and logistics costs, guided at slightly over US$200 million in fiscal 2027, bite harder than ERP savings or if the roughly 85% to 90% dividend payout limits flexibility when Clorox needs cash elsewhere.
Find out about the key risks to this Clorox narrative.
Another View: Clorox Through The P/E Lens
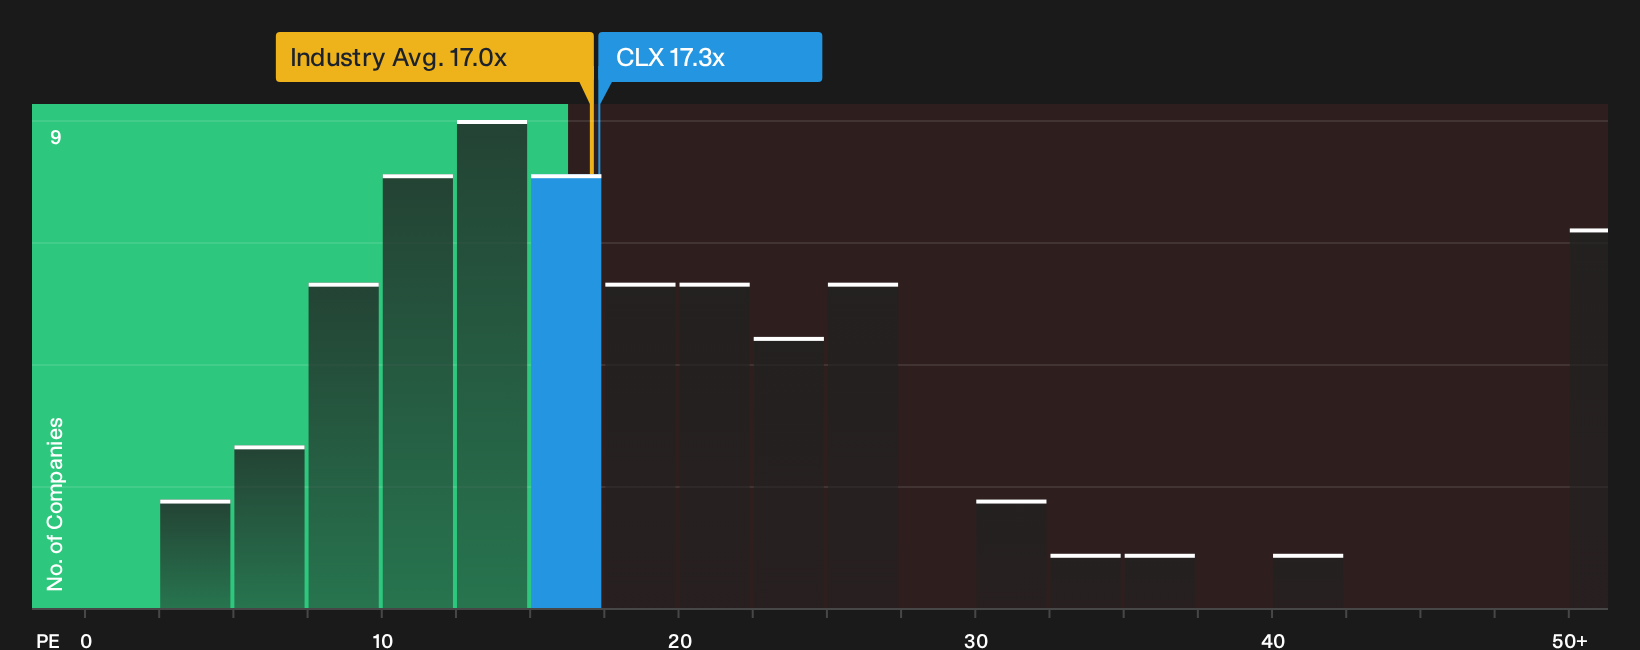
The SWS DCF framework paints Clorox as meaningfully undervalued, yet the simple P/E check is more cautious. At 17.3x earnings, the stock trades slightly richer than the global Household Products group at 17x, while still below peers at 19.8x and an estimated fair ratio of 19.2x. Is that a margin of safety or just a modest discount for slower growth and higher debt risk?
To pressure test that pricing and see how the current multiple compares with the fair ratio the market could drift toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Clorox story can be a strength if you use them well, so move fast on the data and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Clorox?
If Clorox raises more questions than answers for your portfolio right now, widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- Target quality at a discount by scanning companies that combine strong fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- Lock in potential portfolio resilience by reviewing the 31 resilient stocks with low risk scores for businesses with steadier risk profiles.
- Spot early potential by assessing smaller companies with solid financials via the 14 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com