


Production Growth Outlook Could Be A Key Test For Antero Resources Stock
- Antero Resources reported quarterly revenue of US$1.48b, up 22.7% year on year, alongside more than 20% higher production and over 10% lower costs, although revenue and earnings both missed analyst forecasts.
- The company is leaning on HG Energy acquisition synergies. Management expects net production to exit the year over 25% above the prior period while continuing to trim per unit costs.
- We will now assess how this mix of faster production growth and weaker than expected earnings shapes Antero Resources investment narrative from here.
Scan how investors are pricing similar production growth stories by reviewing our curated list of 29 high quality undervalued stocks, which combines expanding output with disciplined cost control.
Antero Resources Investment Narrative Recap
To own Antero Resources, you need to believe the company can turn its higher production base and lower unit costs into more resilient cash generation over time. The latest quarter supports that operating angle, with output up more than 20% and costs down over 10%, even though revenue and earnings landed below market expectations.
The near term swing factor is whether management can keep ramping volumes from the HG Energy assets while holding the line on discipline. The biggest risk is that weaker pricing or renewed cost creep erodes the benefit of that growth, especially given past margin pressure highlighted by external analysis.
The HG Energy acquisition remains the key announcement behind this update, because management is explicitly tying the recent 20% plus production uplift and cost reductions to that deal. The current quarter effectively serves as an early scorecard on whether those acquired West Virginia assets perform in line with prior operational plans.
For you as a shareholder, the acquisition is tightly linked to catalysts and execution risk. If Antero Resources keeps integrating HG while driving toward its multi year cost reduction ambitions, the asset base could support the export linked gas and liquids narrative that analysts focus on. If integration stumbles, the balance between growth and returns becomes harder to sustain.
Analysts currently project that Antero Resources will reach approximately US$7.1b in revenue and US$1.4b in earnings by 2029, based on 7.0% annual revenue growth and an earnings increase of roughly US$300m from about US$1.1b today.
Uncover why Antero Resources' fair value indicates a 40% potential upside to its current price, which could narrow quickly.
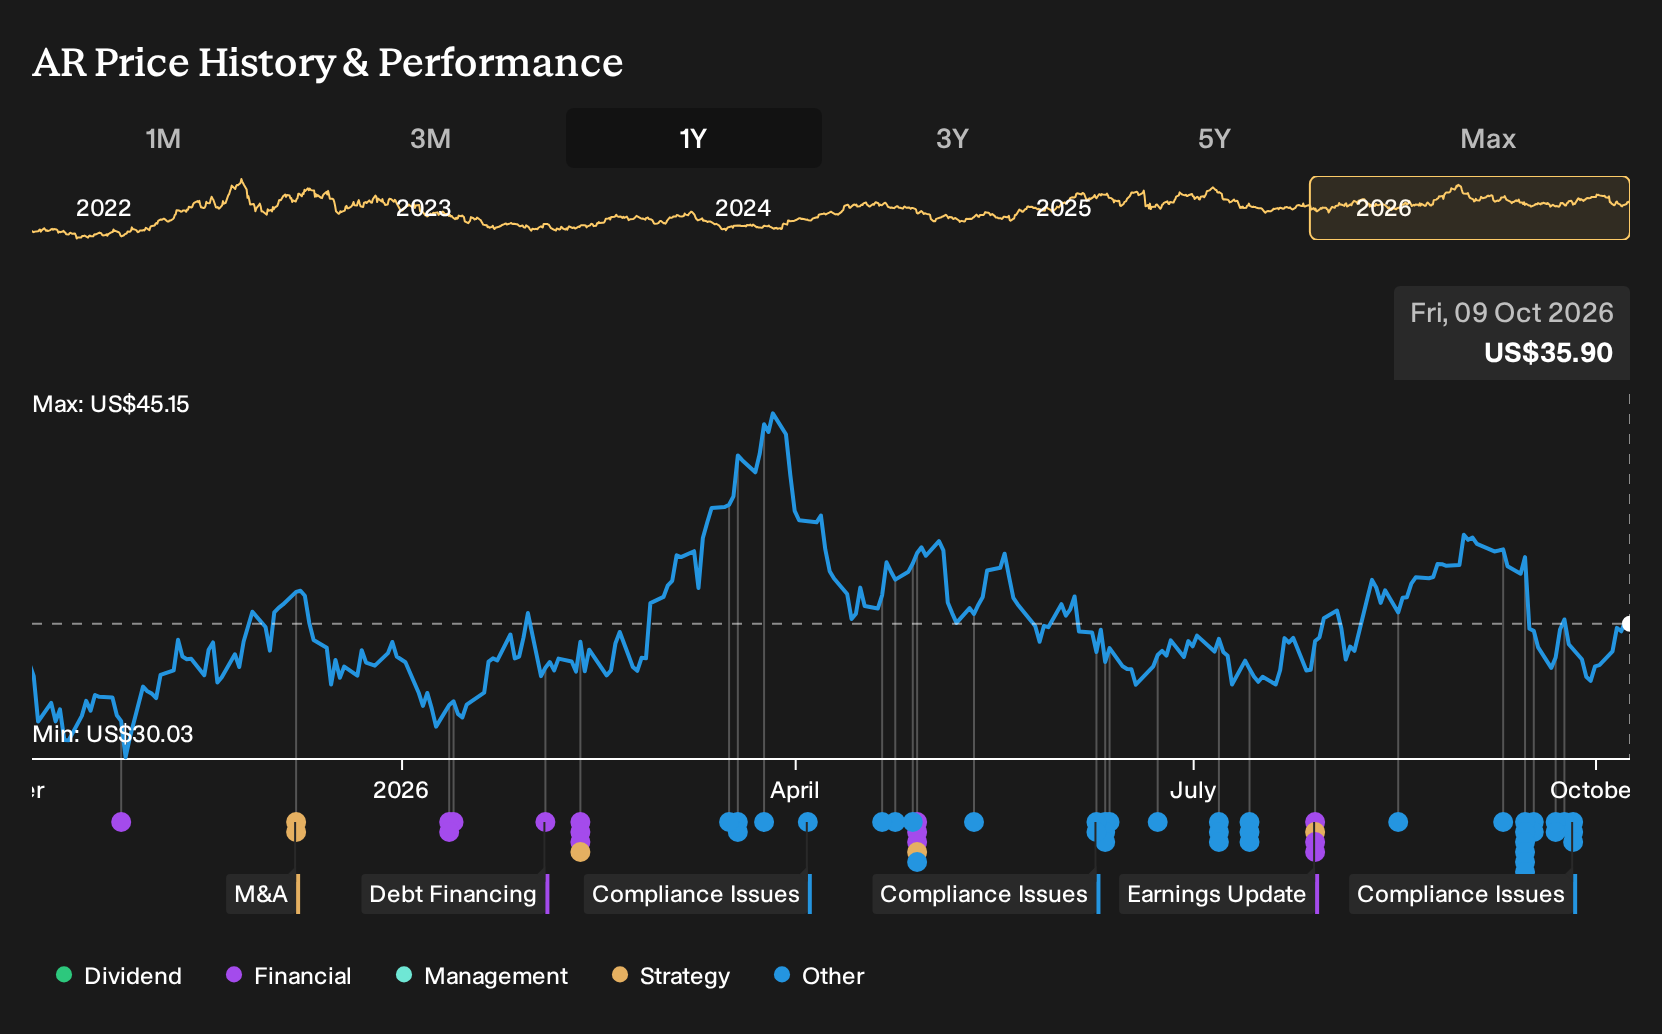
Exploring Other Perspectives
Some of the most optimistic analysts on Antero Resources focus on a different catalyst. They see the push toward roughly US$8.3b of revenue and about US$2.1b of earnings by 2029 as proof that cost cuts and HG Energy integration can really shift the story. These forecasts were set before this latest quarter, so you may want to compare the new results with both the bullish and more conservative views.
Explore 3 other Antero Resources fair value estimates, including one that suggests potential upside of up to 315% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Antero Resources research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Antero Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Antero Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Antero Resources?
If the Antero Resources story has you thinking about how production profiles, costs and balance sheets mesh together, it can help to line it up against a broader watchlist. The Simply Wall St Screener lets you quickly filter for other companies that match the type of risk and return trade off you want to focus on next.
- If you want potential value with quality at the forefront, review a curated set of 20 high quality undiscovered gems that pair robust fundamentals with quieter market attention.
- For readers who care most about resilience, scan a 31 resilient stocks with low risk scores that leans toward steadier earnings profiles and lower risk scores.
- When capital preservation and financial strength come first, focus on a list of solid balance sheet and fundamentals (25 results) that highlights companies with cleaner leverage and stronger underlying accounts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com