


EverCommerce (EVCM) Could Be 30% Below Fair Value After AI Fueled EverHealth Focus
Recent coverage around EverCommerce (EVCM) has focused on its use of AI within the EverHealth suite to reduce healthcare administrative costs, a shift that is drawing renewed attention to the stock.
Against this backdrop, EverCommerce’s recent 30 day share price return of 44.85% has arrived after a year to date decline of 20.87%, while the 1 year total shareholder return is down 15.21%. This pattern may indicate improving short term momentum following a more challenging longer period.
Scan the AI-focused service platforms that are moving on similar catalysts as EverCommerce by reviewing the hand-picked 38 AI small caps that are already catching the market’s attention.
EverCommerce has just put in a sharp 30 day rebound after a tougher run, so the real question now is whether you lean into this reset or wait for a cleaner valuation entry.
Most Popular Narrative: 30% Undervalued
EverCommerce last closed at $9.14, while the most followed narrative anchors fair value at $13.00. This frames a wide gap that investors now need to test against their own assumptions.
Analyst consensus sees embedded payment adoption as a margin lift, but with only low single-digit percentage penetration at top payment solutions that are growing total payment volume by over 12% year-over-year, there is potential for explosive payments-driven operating leverage, with payments potentially comprising well above 30% of consolidated revenue over time, driving gross margin and EBITDA margin expansion well above current expectations.
See why 0 investors see EverCommerce as 30% undervalued.
Result: Fair Value of $13.00 (UNDERVALUED)
Still, EverCommerce’s reliance on small business customers and ongoing acquisition activity could quickly pressure revenue stability and profit quality if conditions or integrations disappoint.
Find out about the key risks to this EverCommerce narrative.
Another Angle On EverCommerce’s Value
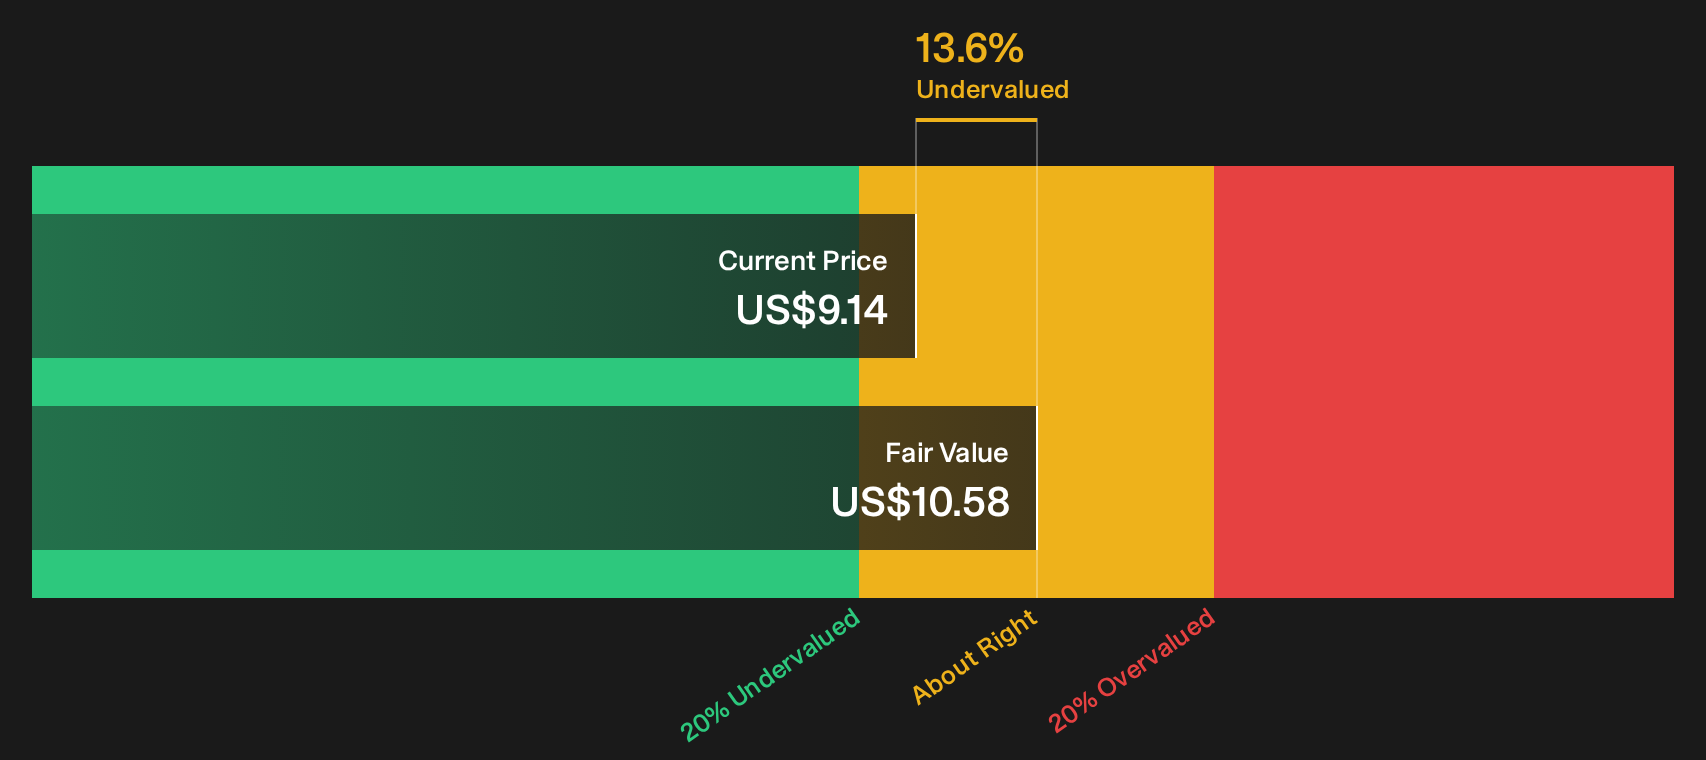
EverCommerce screens as undervalued on the SWS DCF model, with the current $9.14 share price sitting 13.6% below an estimated future cash flow value of $10.58. That supports the $13.00 narrative, but it also raises a question: Is the cash flow view giving you enough margin of safety?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the data can be useful if you use them. Act quickly, review both sides of the story, and weigh the 3 key rewards and 3 important warning signs.
Hunting For More EverCommerce-Style Ideas?
If EverCommerce has sharpened your focus on pricing, risk, and quality, do not stop here. Use curated screeners to surface other clear, numbers-backed ideas fast.
- Target resilient payouts and income resilience by reviewing potential 8 dividend fortresses that could complement a growth-focused holding like EverCommerce.
- Zero in on balance sheet strength by scanning a list of solid balance sheet and fundamentals (25 results) so you are not surprised by hidden financial strain.
- Pounce on mispriced potential by combing through 20 high quality undiscovered gems before wider attention pushes valuations away from your comfort zone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com