


Ferrari (BIT:RACE) Is Drawing Fresh Attention But What Is Behind It?
The FIA’s decision to tighten rules on so called Macarena rear wings from 2027 puts Ferrari (BIT:RACE) under fresh scrutiny, as its heavily rotating design faces the steepest compliance challenge.
Ferrari’s €347.85 share price comes after a 6.07% 90 day share price return and a 9.97% year to date share price return. Its 5 year total shareholder return of 88.27% contrasts with a softer 2.21% total shareholder return over the past year, suggesting momentum has cooled recently even as long term holders have still seen strong compounded gains.
Scan beyond Ferrari to see how other high performance automakers are priced for potential rule shake ups with our hand picked 618 high quality undiscovered gems.
Ferrari appears to be a powerhouse on the track and in recent financial metrics, yet the share price near €347.85 after a cooler 1-year return raises a sharper question: Is this still a quality business at a sensible price?
Most Popular Narrative: 10% Undervalued
Ferrari’s most followed valuation storyline pegs fair value at about €388 per share, slightly above the last close at €347.85, which frames the current price as leaving some headroom if those assumptions hold.
The ramp-up of high-margin, recurring revenue streams from brand sponsorships, lifestyle, and personalization, fueled by lifestyle activities, racing events, and growing global brand desirability, will further enhance margin accretion, drive resilient long-term earnings, and reduce reliance on car sales volume alone. Ongoing investments in innovation (e.g., electrification, new manufacturing/paint facilities, and cross-sector technology transfers like the Hypersail project) both future-proof the business and leverage secular trends towards luxury experiential goods, likely resulting in higher capital efficiency and supporting sustainable earnings growth over the next cycle.
See why 58 investors see Ferrari as 10% undervalued.
Result: Fair Value of €388.02 (UNDERVALUED)
Still, this storyline can unravel if Ferrari misjudges the pace of electrification, or if luxury buyers pull back and leave high P/E expectations exposed.
Find out about the key risks to this Ferrari narrative.
Another View: Ferrari’s Rich Earnings Multiple
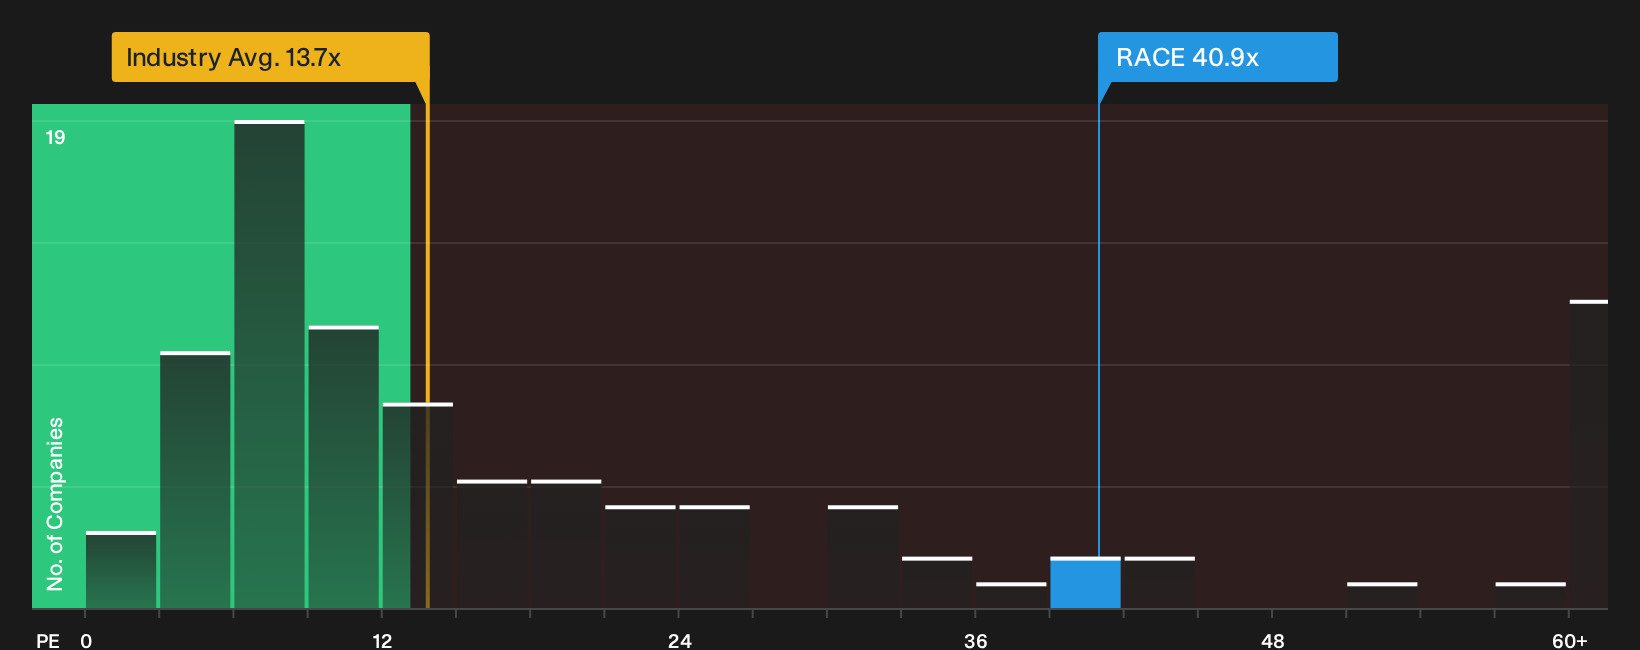
There is a catch. While the popular storyline tags Ferrari as around 10% undervalued at €388 per share, the current P/E of 40.9x looks expensive against the global auto sector at 13.7x and a fair ratio of 21.2x, which implies a lot of optimism is already in the price. If sentiment toward high premium car makers cools, how much compression in that gap are you comfortable with?
For a closer read on what this valuation gap could mean in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Ferrari after all that? Consider reviewing the underlying data for yourself and weighing both the upside and the red flags in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ferrari?
If Ferrari has sharpened your appetite for quality businesses, do not stop here. Put a few more focused filters to work and widen your opportunity set.
- Target resilient balance sheets and cleaner fundamentals by scanning companies in the list of solid balance sheet and fundamentals (204 results).
- Hunt for quality at a potentially reasonable price with the 178 high quality undervalued stocks that filters for strong cash flows and solid financial strength.
- Prioritize income today and potential staying power tomorrow by reviewing companies in the 223 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com