


Moderna Cancer Vaccine Buzz Has Retail Investors Searching Oncology Stocks
A fresh surge of attention on Moderna’s cancer vaccine has pulled oncology stocks back into the spotlight, as traders try to work out which companies might benefit or be left on the sidelines. Market-moving trial results, a high profile index return and an October 24 data reveal have created real FOMO for investors watching biotech. This article walks through three oncology stocks closely exposed to that news and explains why they matter now.
The stocks covered below are only a small sample of what traders are watching, as the full oncology-focused screen surfaced 63 more listed businesses with equally compelling cancer and immunotherapy narratives that are not discussed in this article. If you want to move beyond headlines and systematically sort potential oncology ideas by size, quality and risk, head straight to the Oncology-focused biotech stocks screener to analyze the field and identify your own highest conviction setups.
Revolution Medicines (RVMD)
Overview: Revolution Medicines is a clinical-stage precision oncology biotech developing RAS(ON) inhibitors and companion drugs for hard to treat RAS-addicted cancers.
Market Cap: US$40.7b
Revolution Medicines fits this oncology focused screen as a pure play on targeted cancer drugs, with RAS mutant tumors like pancreatic and lung cancer squarely in focus, at the same time that Moderna’s vaccine data is pulling more investor attention toward advanced cancer treatment platforms.
"The U.S. FDA approved Rasonque (daraxonrasib) for adults with previously treated metastatic pancreatic adenocarcinoma or those who are not candidates for multiagent chemotherapy, based on the Phase 3 RASolute 302 trial that reported a 60% reduction in risk of death and median overall survival of 13.2 months compared with standard chemotherapy."
What happens to future pricing power and long term demand if a single unseen constraint on broad access or reimbursement begins to bite?
If that pressure point proves real rather than theoretical, the full narrative for Revolution Medicines explains how pricing power, access and RAS oncology positioning could still accelerate the story.

BeOne Medicines (ONC)
Overview: BeOne Medicines is a pure-play oncology drug developer with commercial and pipeline therapies targeting blood cancers and solid tumors worldwide.
Operations: BeOne Medicines generates US$6.1b from pharmaceutical products, with revenue led by the U.S. at US$3.3b, followed by China and Europe.
Market Cap: US$40.3b
BeOne Medicines fits this oncology focused screen as a fully committed cancer specialist, with commercial therapies and a deep pipeline that put real weight behind the current interest in new treatment modalities.
"BeOne Medicines remains heavily reliant on BRUKINSA as the core driver of growth and profitability, making the company highly vulnerable to clinical, regulatory, or competitive setbacks in this single asset, which could materially impact future revenues and net income."
For investors watching BeOne Medicines, a key consideration is how one concentrated source of strength may influence pricing dynamics and earnings durability.
That reliance cuts both ways, and the full narrative for BeOne Medicines shows how BRUKINSA concentration could either mask broader momentum or cap an otherwise accelerating oncology story.
Zymeworks (ZYME)
Overview: Zymeworks develops antibody based biotherapeutics and drug conjugates that target cancers and immune related diseases through partnered and internal programs.
Operations: The business generates US$37 million from developing next generation multifunctional biotherapeutics, with all reported revenue coming from Canada.
Market Cap: US$1.8b
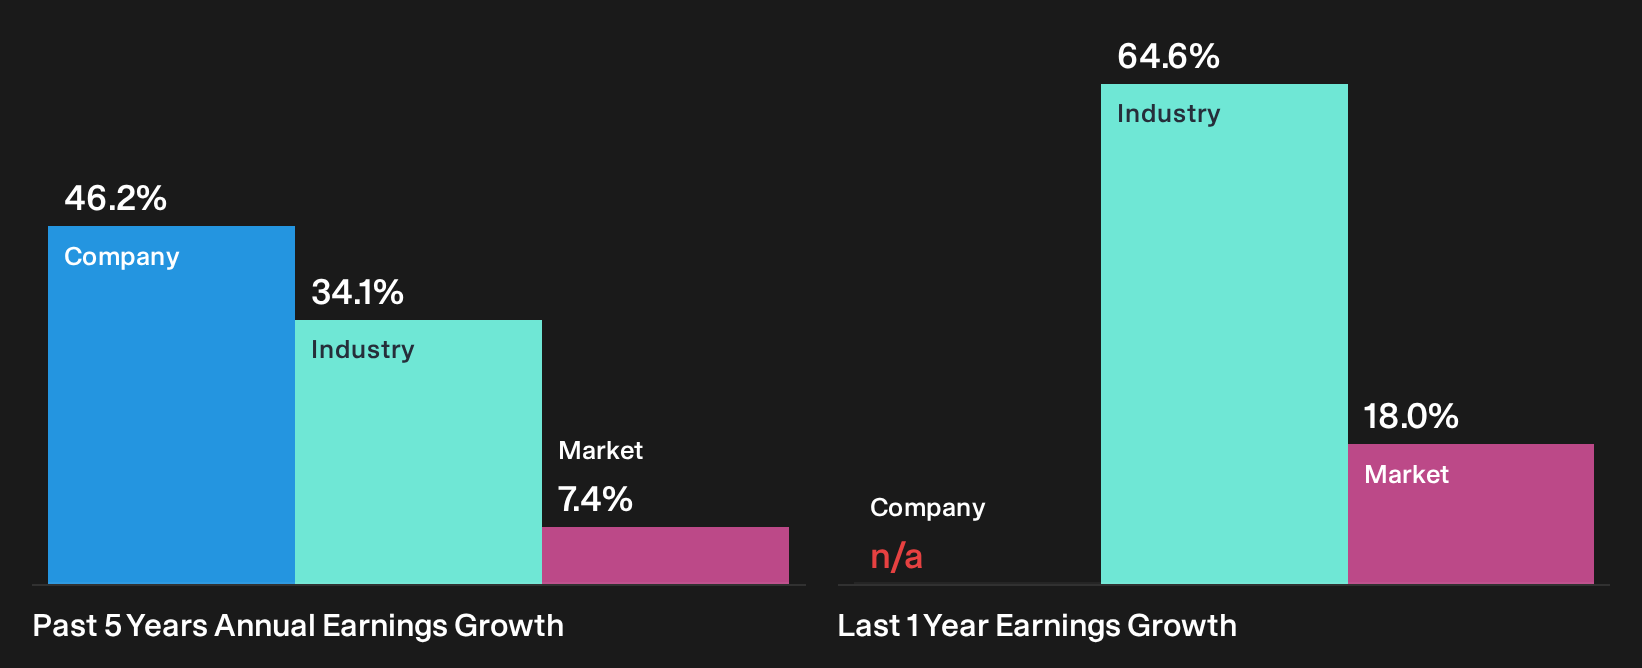
Zymeworks fits this oncology screener as a pure cancer focused biotech, and it is increasingly tied to big ticket HER2 decisions that could reshape how investors think about its royalty driven model.
"Expected regulatory milestones and successful late-stage clinical readouts (notably the Phase III HERIZON-GEA-01 trial for zanidatamab) could trigger substantial milestone payments and sustained royalty streams, driving top-line revenue growth while exercising financial discipline to avoid proportionately increasing operating expenses, improving operating leverage and net income potential."
What happens to that carefully balanced royalty story if just one assumption about future partner execution or regulatory timing starts to slip?
If that risk starts to bite, the full narrative for Zymeworks explains how Zymeworks could still turn partner execution, milestone timing and royalties into an accelerating oncology story.

Seeking Alternatives Before Momentum Flies
Fresh themes are already building breakout potential while they are still under the radar for now. Do not get caught reacting after momentum is flying. Act now.
- Spot resilient cash generators before the crowd and use the list of solid balance sheet and fundamentals (25 results) to focus on businesses built to handle shocks while it matters.
- Ride powerful structural trends by scanning the 43 power grid technology and infrastructure stocks that zeroes in on companies wiring the next generation of energy and grid technology.
- Catch fast moving automation leaders early and lean on the curated 91 robotics and automation stocks to track businesses turning robotics demand into real operating scale.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com