


Avolta (SWX:AVOL) Shares Moved, What Is Behind The Attention?
Avolta (SWX:AVOL) just picked up a new 20-year duty-free contract at Seattle-Tacoma International Airport, giving its Hudson chain more space to test localized, experience-led retail within a key North American hub.
Avolta’s latest contract lands as the share price has slipped, with a 90 day share price return of 18.53% and a year to date share price return of 10.05% in the red, even though the 3 year total shareholder return of 42.26% points to much stronger longer run gains.
Spot under-pressure travel retailers like Avolta that could be setting up for a rebound by scanning our hand-picked 176 high quality undervalued stocks.The question now is whether Avolta’s recent share price pressure reflects cracks in the business or a swing in sentiment that leaves the current valuation behind the fundamentals.
Most Popular Narrative: 19% Undervalued
Avolta’s most followed valuation story puts fair value at CHF51.94, above the last close at CHF42.08. This frames the current share price slide in a very different light.
Expansion into high-growth markets, particularly Asia-Pacific and the Middle East, is expected to increase Avolta's exposure to rising air travel volumes and international passenger flows, thus supporting sustained revenue growth and diversifying earnings streams.
The strong consumer shift toward premium, experiential, and localized travel retail (as seen in high-margin products, flexible "sense of place" stores, and hybrid F&B/retail formats) is anticipated to drive higher average transaction value and support margin expansion.
See why 10 investors see Avolta as 19% undervalued.
Result: Fair Value of CHF51.94 (UNDERVALUED)
Still, the Avolta story can shift quickly if airport concession competition intensifies or if slower North American traffic continues to weigh on regional trading.
Find out about the key risks to this Avolta narrative.
Another View On Avolta’s Valuation
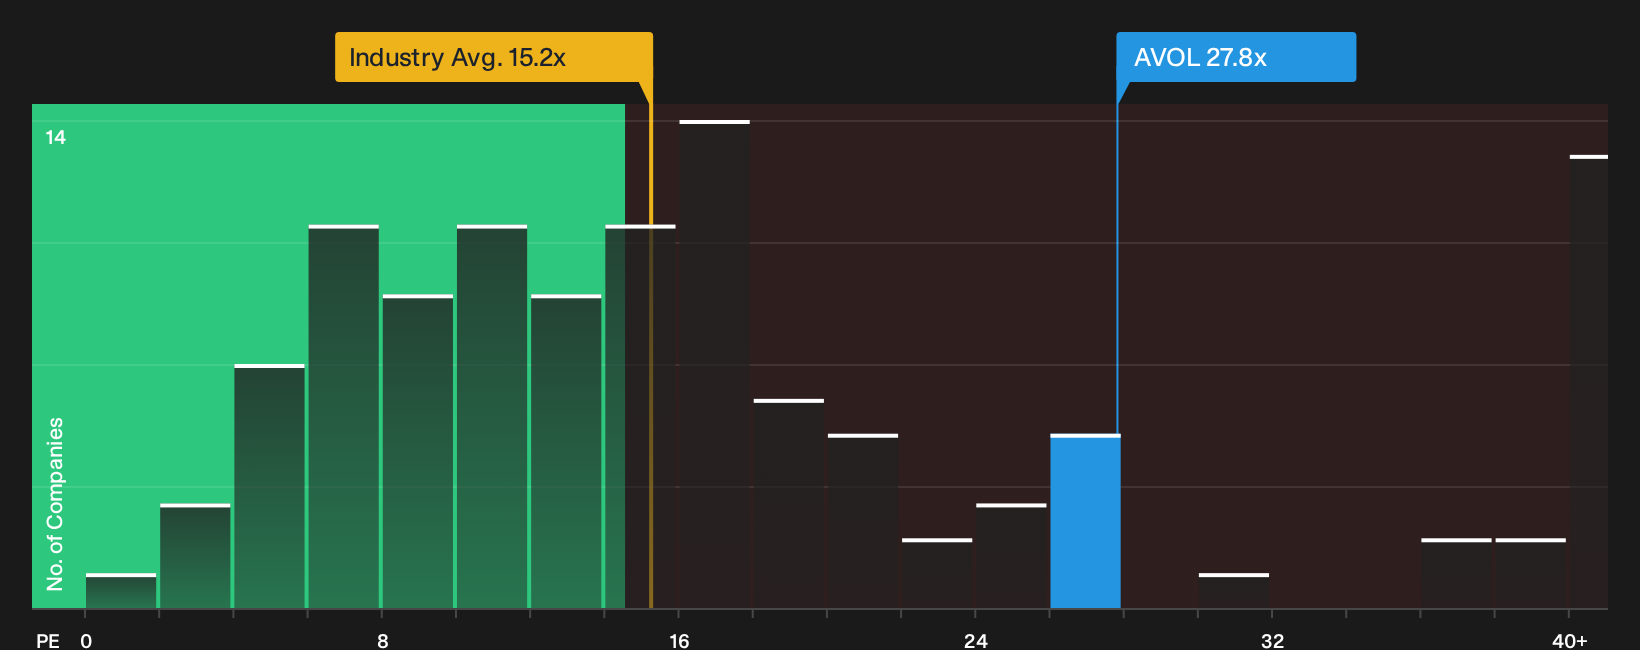
A different lens tells a less generous story for Avolta. The stock trades on a P/E of 27.8x, while the peer group averages 15.6x and the broader European specialty retail space sits at 15.2x. That gap points to a rich premium that could limit upside if sentiment cools.
Investors weighing that premium against the earlier fair value estimate may want to see what the numbers imply at different earnings levels and sector multiples. From there, they can ask whether the current price still leaves enough room for error or surprise.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Avolta feels unresolved, move quickly, review the data for yourself, and carefully weigh both concerns and bright spots through 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Avolta?
If Avolta has your attention, do not stop here. Use the Simply Wall Street Screener to compare other opportunities and stress test your investing checklist.
- Target income first by reviewing companies in the 223 dividend fortresses that may offer cash returns alongside more resilient balance sheets.
- Raise your quality bar by scanning the list of solid balance sheet and fundamentals (204 results) so you are focusing on businesses with financial foundations that can handle shocks.
- Stay ahead of the crowd by checking the 618 high quality undiscovered gems before attention and expectations catch up with the underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com