


Is Lerøy Seafood Group (OB:LSG) Undervalued On Lower Q3 Production?
Q3 production drop puts Lerøy Seafood Group in focus
Lerøy Seafood Group (OB:LSG) has drawn fresh attention after reporting third quarter 2026 operating figures that show lower harvested volumes of salmon, trout and wildcatch compared with the same period last year.
The weaker third quarter production data landed in a year when Lerøy Seafood Group’s share price has already fallen 19.07% year to date, with a 30 day share price return of down 5.02% and a 1 year total shareholder return of down 12.32%. In contrast, the 3 year total shareholder return of 8.64% suggests longer term holders have experienced a very different journey to those focused on the recent pullback.
Scan beyond Lerøy Seafood Group and compare this setback with other seafood players by tracking those with list of solid balance sheet and fundamentals (204 results) that could be better positioned for the next upswing.
Bulls point to Lerøy Seafood Group’s recent profit growth and wide footprint in salmon, trout and whitefish. Bears focus on weaker volumes and a share price that has slipped hard this year. Which side does today’s valuation support?
Most Popular Narrative: 16% Undervalued
Lerøy Seafood Group closed at NOK41.64, while the most followed narrative anchors fair value closer to NOK49.50, so the gap between price and story is hard to ignore.
Lerøy's sustained investment in new farming technologies (such as submerged and shielding technology) and its in-house improvement program have already yielded higher survival rates, lower mortality, and cost reductions, positioning the company for continued increases in production volumes with better efficiency, which should positively impact both revenue growth and net margins.
See why 22 investors see Lerøy Seafood Group as 16% undervalued.
This widely tracked view applies a 6.79% discount rate and assumes Lerøy Seafood Group can turn its vertically integrated model and technology spend into stronger margins over time. It therefore arrives at a fair value of NOK49.50 that sits above both the current NOK41.64 share price and the NOK48.38 analyst target. The result is a narrative that treats recent production softness and weaker share price performance as part of a longer earnings build, not the whole story, while still flagging execution, regulation and biological risks as key swing factors for future returns.
Result: Fair Value of NOK49.50 (UNDERVALUED)
Still, inflation in feed and energy costs, together with stricter quotas in the wildcatch segment, could easily upset the margin story behind Lerøy Seafood Group.
Find out about the key risks to this Lerøy Seafood Group narrative.
Another View on Lerøy Seafood Group’s Price
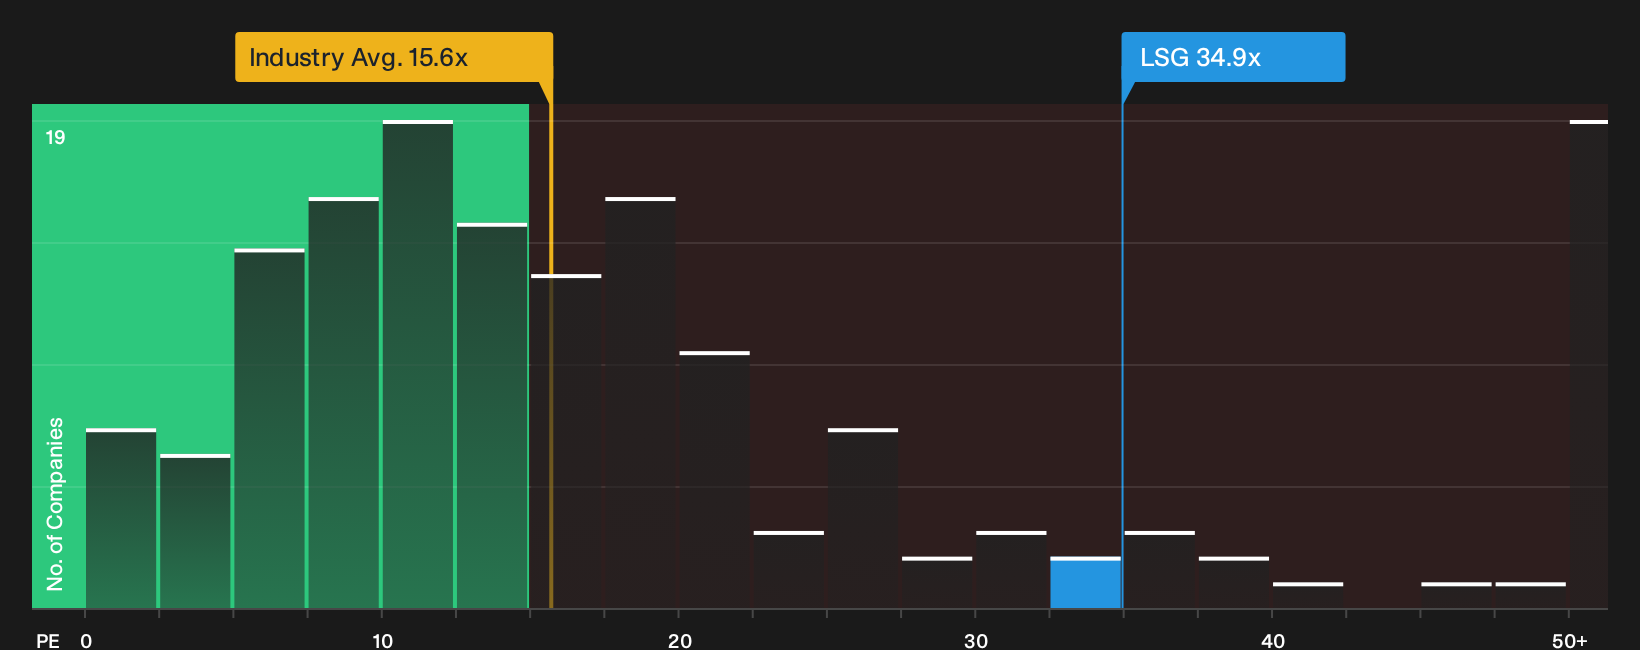
The story flips when you look at simple earnings multiples. Lerøy Seafood Group trades on a P/E of 34.9x, which is rich against both its peer average of 22.9x and a fair ratio of 31.7x. That tilts this yardstick toward overvaluation. Which yardstick do you trust more?
To see how this richer P/E could reshape the risk reward trade off for Lerøy Seafood Group, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Lerøy Seafood Group can be confusing, so move quickly from headline impressions to the underlying numbers and carefully consider both the risks and potential upsides highlighted in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lerøy Seafood Group?
If Lerøy Seafood Group has sharpened your focus on quality and price, you could expand your watchlist with a few carefully filtered ideas that match different investing styles.
- Pinpoint potential bargains by scanning a curated set of 176 high quality undervalued stocks that combine solid fundamentals with more attractive pricing.
- Prioritise resilience by reviewing a 223 resilient stocks with low risk scores that screens for businesses with stronger balance sheets and lower overall risk scores.
- Explore a 618 high quality undiscovered gems that highlights under-the-radar companies with stronger financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com