


Learn Why The Bull Case For Cracker Barrel Stock Could Change Following Earnings Estimate Revisions
- Cracker Barrel Old Country Store filed a definitive proxy statement on October 6, 2026, urging shareholders to reject a proposal that would require investor approval before issuing blank check preferred stock outside routine capital raising or acquisition uses.
- The proxy contest arrives just as analysts highlight sharply higher earnings estimates for the next quarter and full year. This puts Cracker Barrel’s capital flexibility and governance approach in sharper focus for investors weighing its operational turnaround plans.
- We will now look at how Cracker Barrel’s improved earnings outlook, highlighted by recent analyst estimate revisions, could reshape its investment narrative.
Cracker Barrel Old Country Store Investment Narrative Recap
To own Cracker Barrel Old Country Store, you need to believe the turnaround can translate better guest scores and a 12m plus rewards base into steadier traffic and healthier same store sales. The near term swing factor remains whether high single digit traffic declines can soften enough for recent cost cuts and debt reduction to show up more clearly in earnings quality.
The biggest risk is straightforward. If value focused pricing around an average check near US$15.85 meets rising costs or a weaker consumer, margins could remain thin and the fiscal 2027 EBITDA ambitions could appear stretched. The proxy fight on blank check preferred stock feels secondary to those operating questions.
The fresh proxy statement on blank check preferred stock matters because it affects capital flexibility at the same time Cracker Barrel Old Country Store is trying to balance debt reduction, refurbishment needs and a rewards heavy marketing push. A tighter policy on preferred issuance could restrict one potential funding lever during choppy restaurant cycles.
For you as a shareholder, the practical question is how much comfort you want around potential dilution or shifts in voting power relative to management’s desire to keep tools available for capital raising or acquisitions. The earnings estimate revisions indicate optimism, but the main test remains execution on traffic, value positioning and the 2027 EBITDA range.
Cracker Barrel Old Country Store is modeled to reach about US$3.6b in revenue and US$62.0m in earnings by 2029, based on analyst assumptions of 2.5% yearly revenue growth and an earnings increase of roughly US$30.3m from the current US$31.7m level.
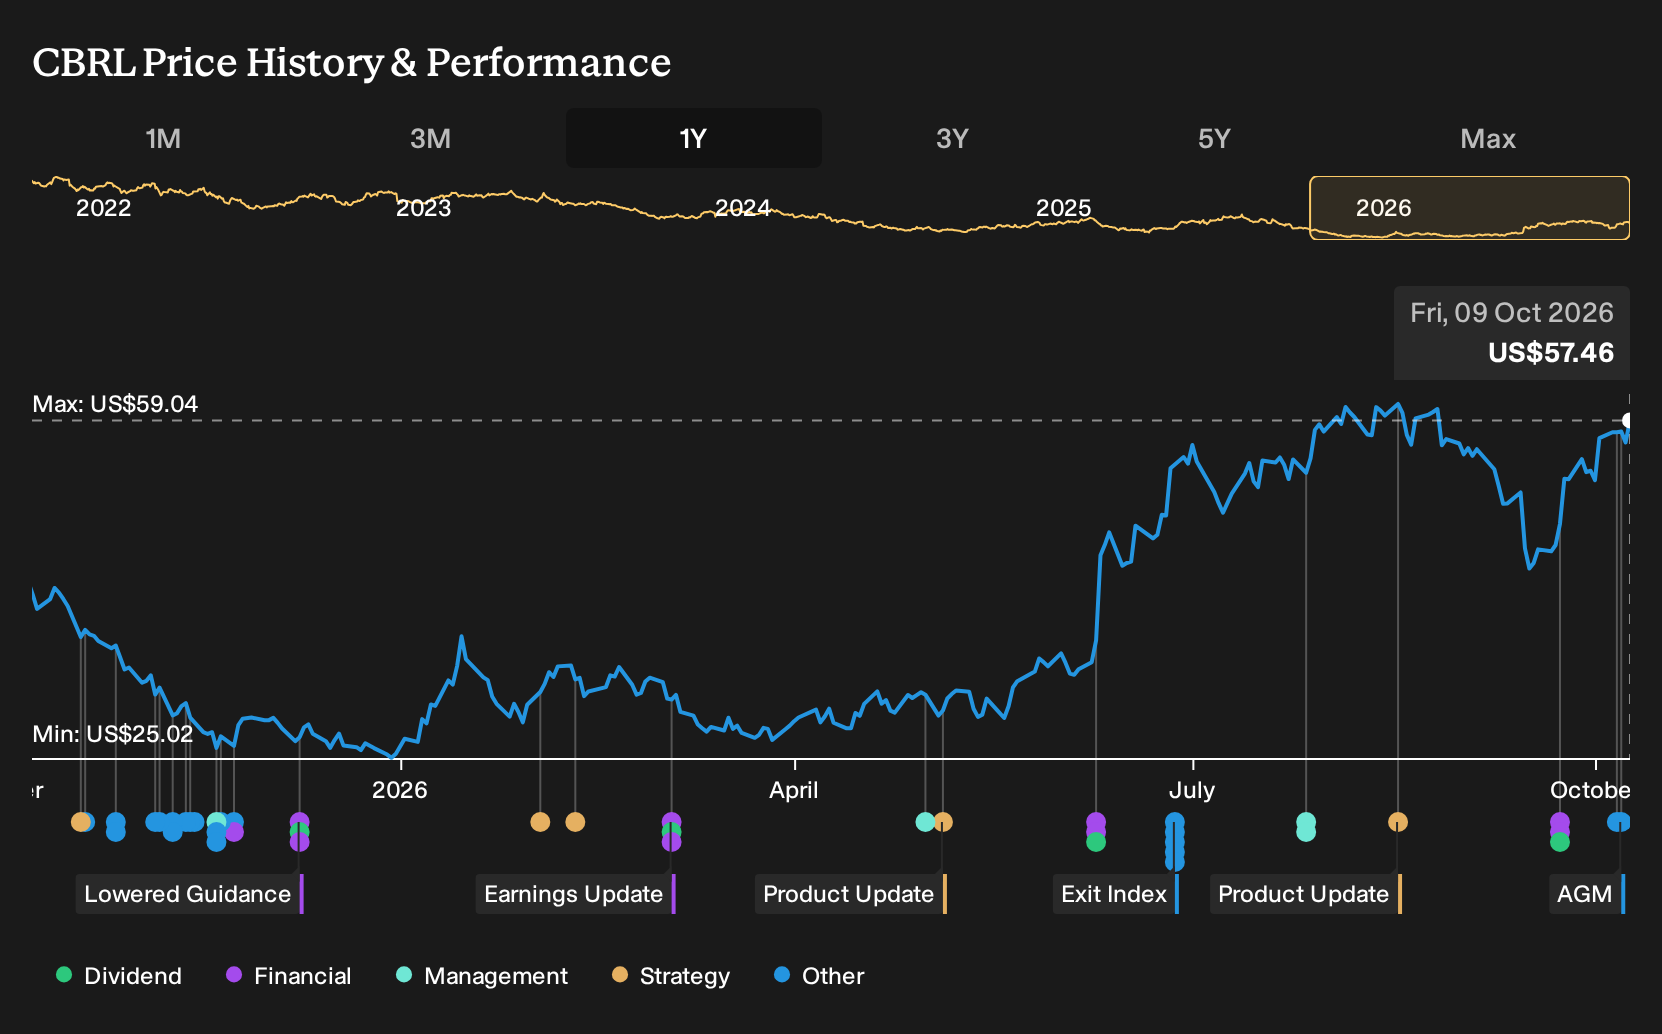
Uncover why Cracker Barrel Old Country Store's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some bullish analysts frame the proxy fight differently. They see capital flexibility as a potential earnings catalyst for Cracker Barrel Old Country Store, since their pre news models already penciled in earnings of about US$68.7m on US$3.6b of revenue by 2029. Those views are more optimistic than consensus and may shift once this governance debate plays through.
Explore 3 other Cracker Barrel Old Country Store fair value estimates, including one that suggests it could be worth as much as $60.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cracker Barrel Old Country Store research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cracker Barrel Old Country Store. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cracker Barrel Old Country Store's overall financial health at a glance.
Looking for more investment ideas beyond Cracker Barrel Old Country Store?
If the Cracker Barrel Old Country Store story has you rethinking where risk, income and value fit in your portfolio, it can help to line it up against other opportunities using a consistent framework.
- For investors who want income to play a bigger role in total return, scan for potential yield opportunities through our curated list of 8 dividend fortresses.
- If capital preservation ranks high on your priority list, narrow your watchlist to companies with steadier profiles by reviewing a universe of 31 resilient stocks with low risk scores.
- When the goal is to back financially robust businesses, focus your research on a list of solid balance sheet and fundamentals (25 results) that meet your quality threshold before you even open a single company report.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com