


Lightspeed Commerce (TSX:LSPD) Stock May Be Below Fair Value As AI Tools Gain Attention
Lightspeed Commerce has seen its stock move around in recent years, and with fresh attention on its payments and AI tools, the real question for investors is whether the current share price lines up with what the business is generating in sales.
- Over the past 5 years the stock has fallen 87.6%, which puts the focus squarely on whether today’s valuation still reflects the revenue base the company has built.
- Recent gains tied to AI features and payments growth may support expectations for higher sales efficiency and better monetisation of its unified commerce platform. This, in turn, feeds directly into how much revenue investors are willing to pay for.
- Your read on Lightspeed Commerce is one view; the desks covering it have another. See what analysts think Lightspeed Commerce's shares could be worth.
The issue now is whether Lightspeed Commerce’s current market value is justified by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales driven valuation question that Lightspeed Commerce now faces across a wider set of AI focused platforms, take a look at 4 AI small caps.
Does Lightspeed Commerce Look Undervalued on Sales?
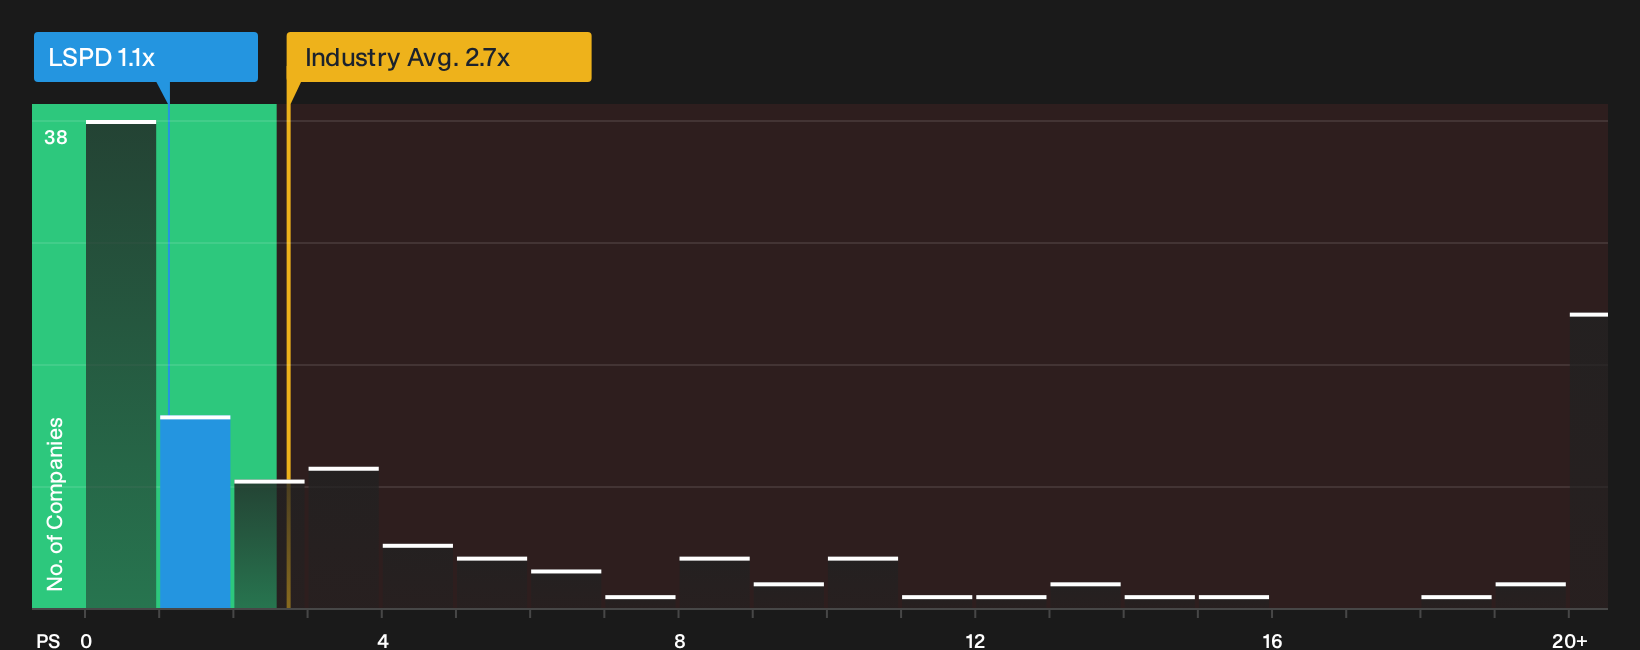
P/S suits Lightspeed Commerce because investors are focused on how much they are paying for each dollar of sales in a software and payments driven model. The stock trades on a P/S of about 1.1x, which is well below the Software industry average of roughly 2.7x and under the peer group at about 3.0x.
That gap also sits below the Fair Ratio benchmark that reflects what might be expected for Lightspeed Commerce once growth prospects, margins, size and risk profile are taken into account, which points to the shares screening as undervalued on this metric. Because the recent AI and payments news has lifted sentiment without pushing the P/S multiple anywhere near peer levels, the current price still asks investors to pay a relatively low sales multiple for the unified commerce platform. Explore the numbers behind Lightspeed Commerce's P/S valuation.
The Lightspeed Commerce Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Lightspeed Commerce pick up where the P/S debate leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Instead of relying on a single ratio or model output, they unpack the future that number rests on so you can watch over time whether those underlying assumptions still hold.
Community narratives on Lightspeed Commerce split between those who see disciplined execution creating upside and those who think competition and costs cap the reward.
Bull case: 14% undervalued
"Rising payment penetration (now at 41% globally and just 35% in efficiency markets) and ongoing conversion to Lightspeed Payments fuel higher transaction-based revenue streams..."
Discover why this Narrative puts Lightspeed Commerce at 14% undervalued.
Bear case: 38% overvalued
"Persistent lack of material free cash flow and ongoing reliance on adjusted EBITDA improvements over hard profitability measures means Lightspeed has limited margin for error..."
Explore why this Narrative puts Lightspeed Commerce at 38% overvalued.
One more piece of the Lightspeed Commerce story to examine
Price tags and sales multiples only tell part of the story for Lightspeed Commerce, because separate research checks have flagged specific concerns that deserve your attention before you lean on valuation alone. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com