


Missed Out On Macerich's Run? Here's The Bet Holders Made
If you had bought Macerich on 9 October 2025, you were stepping into a live argument over whether experiential retail could offset heavy debt and e-commerce pressure. For Macerich shareholders, the return over the past year was 39.4%, including dividends. That payoff now invites a harder question. Faced with bullish talk of revitalized urban malls and bearish warnings about declining mall revenues, what exactly were early buyers weighing at the time?
Macerich has already moved. See which of 28 high quality undervalued stocks still trade below our estimates.
The Two Stories Macerich Investors Had To Price In
The shares cost US$17.06 at the start of the period, and the core question for anyone looking at Macerich was which of two very different stories to believe.
The bullish view argued that experiential retail could lift high quality urban malls, with a Fair Value of US$19.53 that reflected what those assumptions implied rather than a fixed fact. Supporters leaned on expectations that leasing momentum and a 2.2% profit margin assumption could justify a very high future P/E of 352.8x.
The bearish camp pointed to e-commerce pressure and heavy leverage, tying its Narrative to a Fair Value of US$15 that again came from its own model. That side focused on the risk that mall revenues kept declining and that a loss-making margin left refinancing and redevelopment capacity under strain.
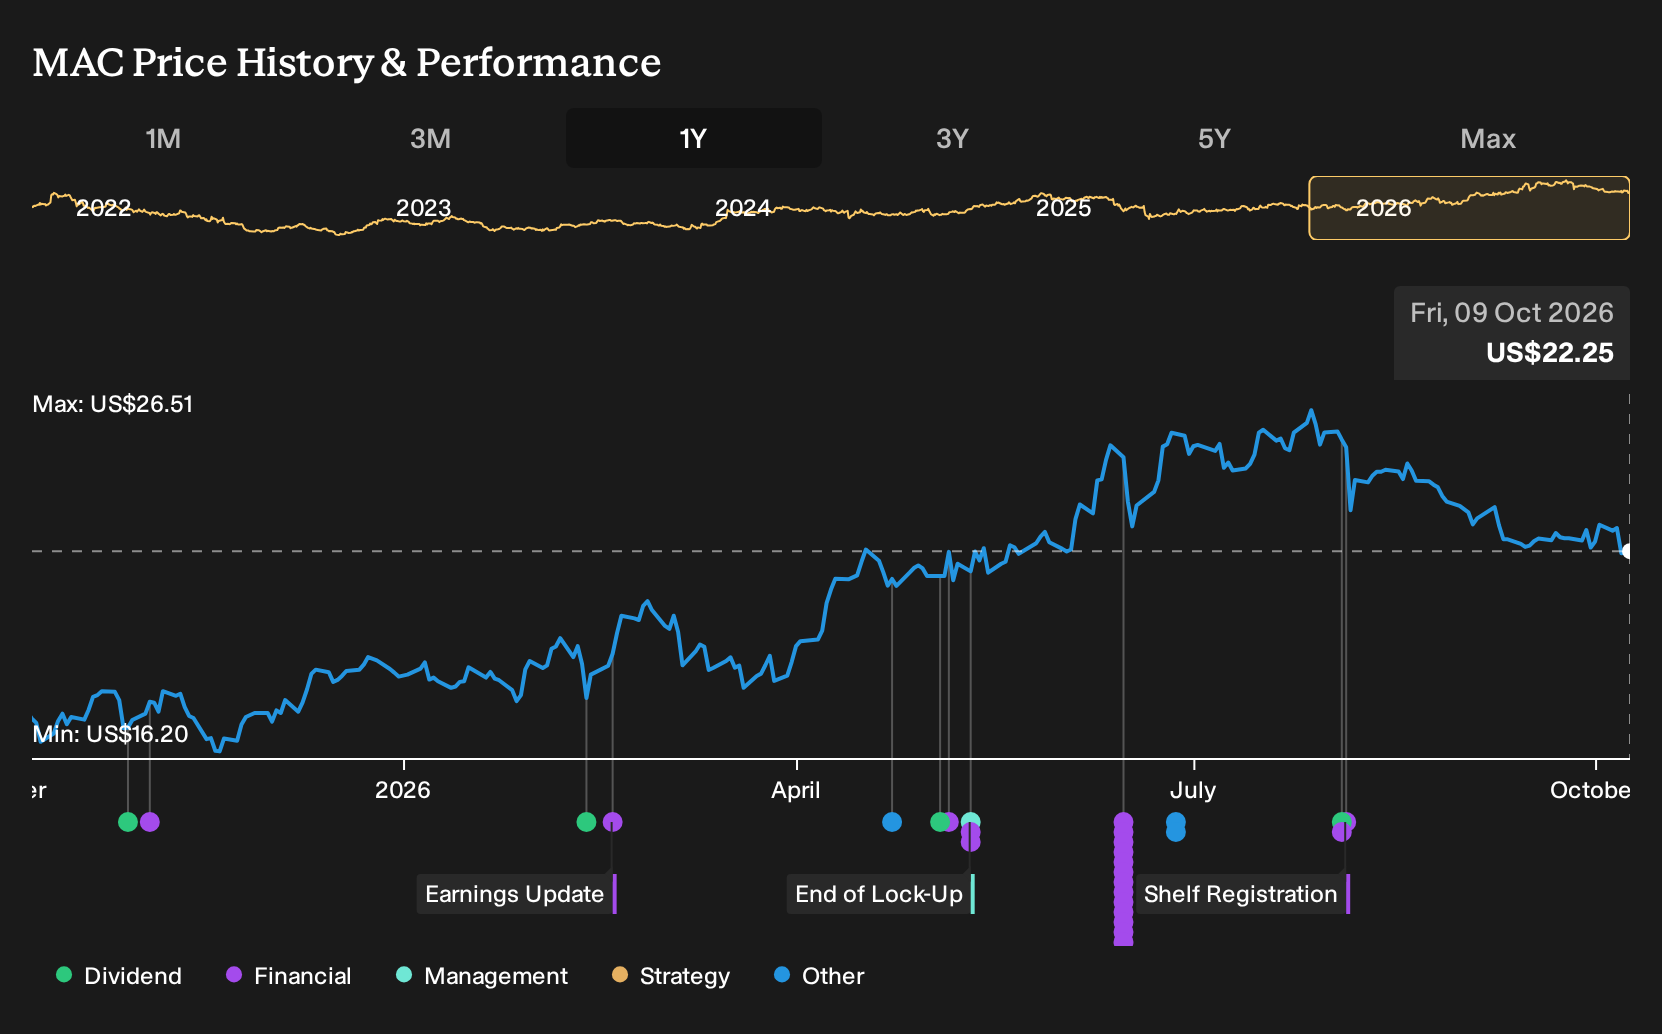
What The Evidence Around Macerich Actually Tested
Macerich’s Q2 2026 update showed revenue at US$252.4 million and a net loss of US$27.3 million, with net margin improving to -10.8%. That supported the bullish story on leasing progress and operational traction. Ongoing losses still left the profitability part of that case unproven, so the evidence cut both ways.
The lesson to copy elsewhere is simple. When a turnaround hinges on margins moving from negative to positive, track net income and net margin together rather than just headline revenue.
What Macerich’s One Year Run Now Asks You To Believe
With Macerich at US$22.25 today after a 39.4% gain over the past year, the selected Narrative still places its Fair Value above the current price rather than at it. That view leans on experiential retail concepts, higher quality urban malls and active leasing as drivers for future cash generation.
Against that backdrop, the Narrative argues today’s price does not fully credit sustained tenant demand and rent spreads from experiential, omni channel focused redevelopments across the portfolio.
"The focus on experiential and destination-oriented retail (such as DICK'S House of Sport, Cheesecake Factory and entertainment concepts) is revitalizing consumer engagement and increasing traffic, positioning the portfolio to benefit from experience-driven spending and capturing higher net margins over time."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 34% below our estimate - converts a growing backlog of modular industrial projects into installation revenue.
- Company 2 - 46% below our estimate - scales a regulated online wagering platform as customers migrate from retail options.
- Company 3 - 27% below our estimate - supplies dense GPU server racks that users pair with integrated AI software.
Those are three of them. See every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com