


ManpowerGroup (MAN) Tests Its Turnaround Narrative After A Sharp Rebound
ManpowerGroup (MAN) has drawn fresh attention after recent share price swings, with the stock down about 7% over the past month and up roughly 36% in the past 3 months.
Despite the recent pullback, ManpowerGroup’s share price has a strong year-to-date return of 75.58%. The 1-year total shareholder return of 45.70% comes after longer term total shareholder returns over 3 and 5 years that declined 15.91% and 43.02%, respectively.
Scan beyond ManpowerGroup’s sharp rebound to see how it compares with other handpicked turnaround stories in our 20 high quality undiscovered gems.
The rebound in ManpowerGroup after a tough few years has reopened a basic question for investors. Do recent gains still leave a wide enough gap between today’s price and fair value estimates to justify fresh interest?
Most Popular Narrative: 8% Undervalued
On the widely followed narrative, ManpowerGroup’s fair value sits at $57.33, modestly above the last close at $52.78. This puts the recent rebound in a tighter pricing range than the raw share swing might suggest.
ManpowerGroup is executing a multi year transformation program that is expected to reach US$200 million of permanent annual cost savings by 2028. Early savings of about US$20 million have already been identified, and management estimates the full program could add roughly 110 basis points to EBITA margin in isolation. This directly targets structurally higher operating margins and earnings power compared with recent 2% margin levels.
See why 9 investors see ManpowerGroup as 8% undervalued.
Result: Fair Value of $57.33 (UNDERVALUED)
Still, the ManpowerGroup story can break if gross profit pressure persists or if earnings and free cash flow fail to improve in line with expectations.
Find out about the key risks to this ManpowerGroup narrative.
Another View: Market Ratios Paint A Different Picture
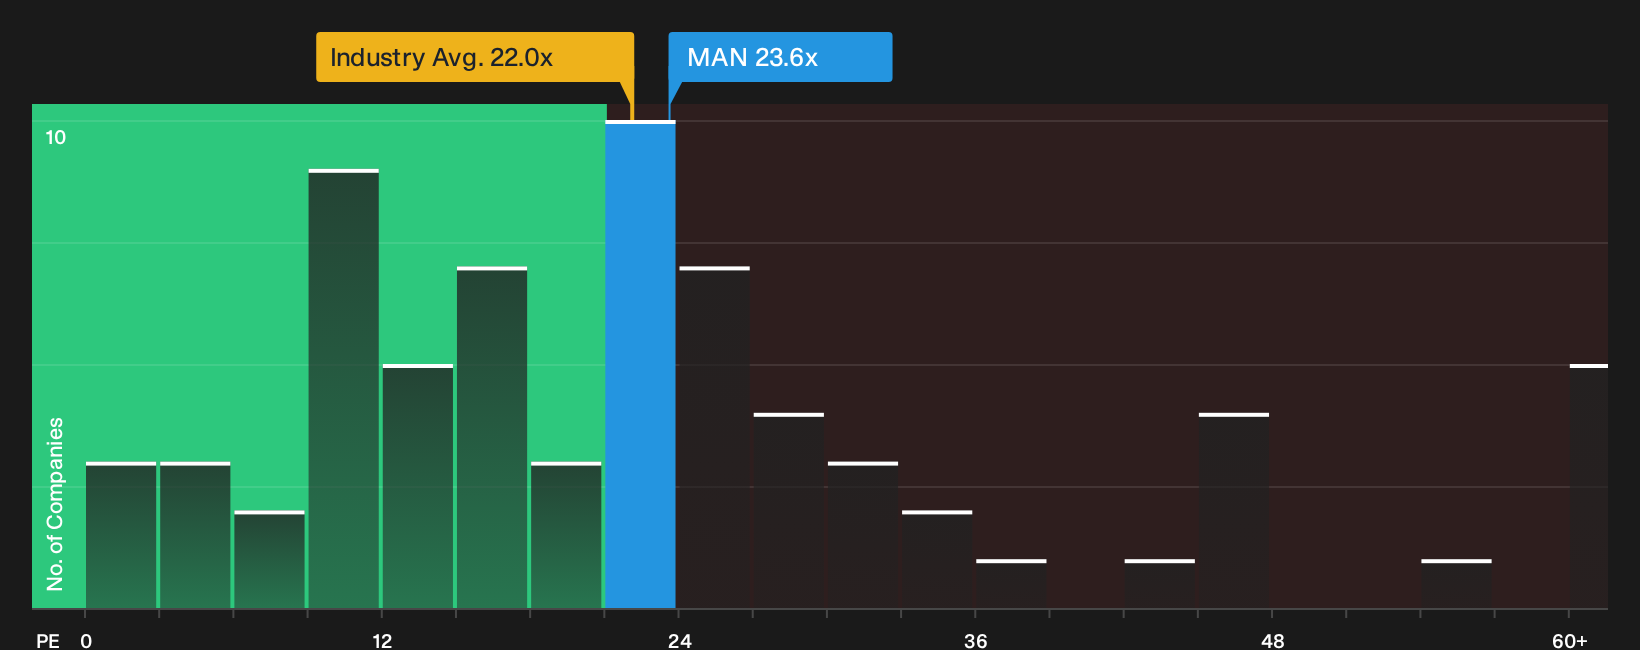
The story around ManpowerGroup shifts once price is compared with earnings. The stock trades on a P/E of 23.6x, slightly above the US Professional Services average of 22.2x, while the fair ratio points to 32.6x. That gap suggests more room on the upside, but it also raises the question of how much valuation risk you are willing to carry if sentiment turns.
To see how this pricing stacks up against sector peers and where the fair ratio might matter most for your process, take a closer look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on ManpowerGroup is clearly mixed, so if you care about the full picture, move quickly to weigh the upside against the downside using 3 key rewards and 4 important warning signs.
Looking For More Ideas Beyond ManpowerGroup?
If you want a wider view than ManpowerGroup alone, use the Simply Wall St screener to spot other opportunities that match your risk and return preferences.
- Target resilient potential by scanning a 31 resilient stocks with low risk scores that may help you keep drawdowns in check when markets turn choppy.
- Boost your income focus and review a curated 8 dividend fortresses that could suit investors who care about consistent cash payouts.
- Hunt for quality at a sensible price through a 28 high quality undervalued stocks that filters for fundamentals, not hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com