


Should Earnings Beat Require Action From ABM Industries (ABM) Investors?
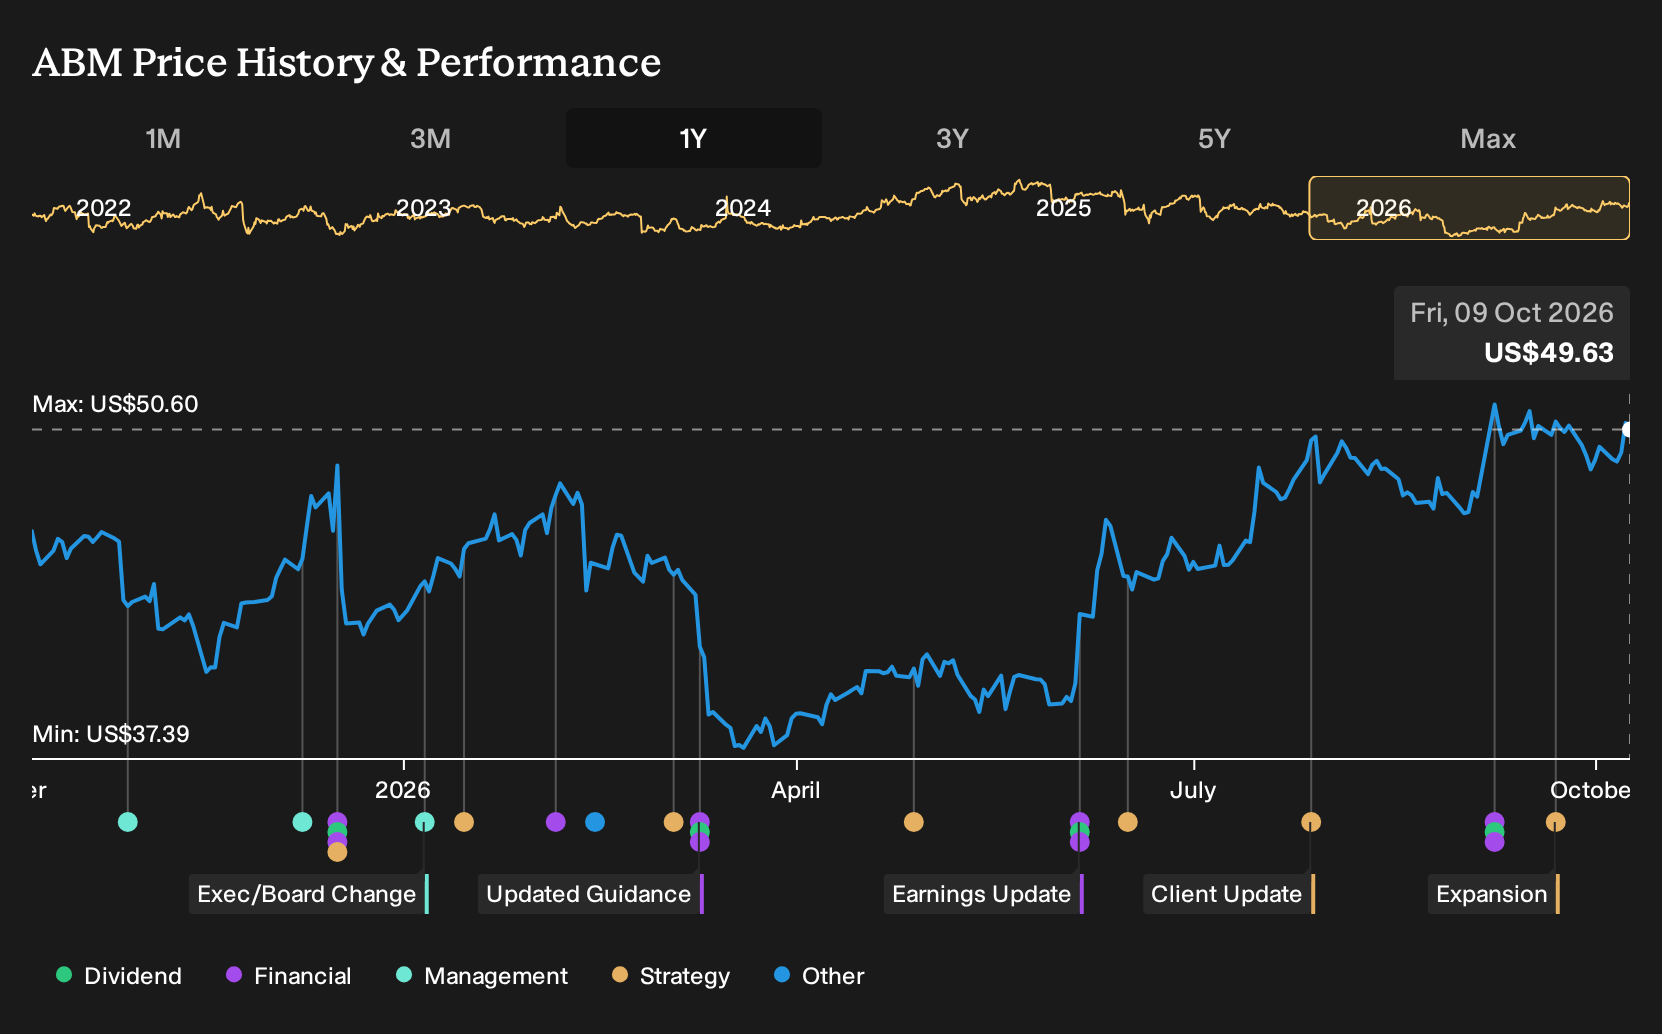
- ABM Industries recently reported third quarter fiscal 2026 results with adjusted earnings of US$1.04 per share, 27% higher year over year, supported by strong contributions from Manufacturing & Distribution and Aviation, increased operating efficiency, and improved segment level profitability.
- The company also raised its fiscal 2026 adjusted earnings and operating cash flow outlook after stronger than expected free cash generation and rising exposure to higher margin technical infrastructure work in semiconductors, microgrids, and data centers.
- We will now look at how ABM Industries' earnings beat and upgraded outlook reshape the investment narrative built around technical infrastructure.
ABM Industries Investment Narrative Recap
To own ABM Industries, you need to be comfortable with a facility services business that is steadily leaning into higher margin technical infrastructure such as semiconductors, microgrids, and data centers. The latest earnings beat and guidance raise support that mix shift as a working thesis, rather than resetting it. The near term swing factor still looks like execution in those technical projects and Aviation and Manufacturing & Distribution contracts.
The biggest risk remains pipeline conversion and renewal quality on the record sales backlog, plus how durable the recent cash flow uplift proves once ERP related benefits normalise. The upgraded free cash flow outlook is helpful, yet it does not fundamentally change that dependency on new wins and clean execution.
The most relevant piece of news here is ABM Industries lifting its fiscal 2026 adjusted earnings and operating cash flow outlook after third quarter results. That guidance move links directly to the core catalyst investors watch, which is a growing contribution from higher margin technical infrastructure work and disciplined contract selection across the portfolio.
For you as a shareholder, the question is whether management can keep converting the semiconductor, microgrid, and data center pipeline, while turning the US$1.9b of FY25 bookings and US$1.2b from the first half of FY26 into solid, cash generative contracts. Any stumble in those areas, especially as ERP tailwinds fade, would pressure the narrative around margin and cash flow improvement.
ABM Industries' current earnings of US$166.4 million are projected by analysts to reach US$272.9 million by 2029, which implies an earnings increase of about US$106.5 million alongside forecast revenue of US$10.1b in that same year, based on an assumed 3.3% yearly revenue growth rate.
Discover why ABM Industries' fair value points to a potential 13% upside from its current price, an opportunity that could diminish quickly.
Exploring Other Perspectives
One alternate view puts far more weight on airport and aviation infrastructure as the real swing factor for ABM Industries. Before this latest earnings surprise, the most optimistic analysts were already pencilling in revenue of about US$10.0b and earnings near US$284.8 million by 2029. That is a more upbeat story than consensus, and the fresh results may yet push those scenarios in a different direction. Investor opinions can vary widely, so consider this a prompt to compare several outlooks rather than rely on a single script.
Explore another ABM Industries fair value estimate, including one that suggests as much as 88% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ABM Industries research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ABM Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABM Industries' overall financial health at a glance.
Looking for more investment ideas beyond ABM Industries?
Once you have a view on ABM Industries, it often helps to widen the lens and compare it with other businesses that match your goals on value, income, or resilience. The Simply Wall St Screener lets you do that quickly using preset filters built from fundamental data.
- For investors who want quality at a reasonable price, start with a curated group of fundamentally strong companies that look cheap on the numbers through our 28 high quality undervalued stocks.
- If income is your priority, you can focus on businesses built around consistent shareholder payouts by scanning our 8 dividend fortresses.
- Those who care most about durability and financial strength can zero in on companies with robust balance sheets and solid fundamentals using this targeted 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com