


Whirlpool (WHR) Cost Savings Story Keeps Fair Value In Focus After Sharp Share Slide
Whirlpool (WHR) has drawn fresh attention after its share price closed at US$28.83 on 9 October 2026, leaving the appliance maker with a market value of about US$1.9b.
The recent 1-day share price return slipped 1.13%, extending a 7-day share price decline of 4.88% and a 30-day fall of 21.72%. Meanwhile, the 1-year total shareholder return is down 58.63%, signalling that momentum in Whirlpool is still fading rather than turning.
Contrast Whirlpool's slide with a curated group of companies screened for 28 high quality undervalued stocks, which may offer stronger fundamentals at more restrained valuations.
Whirlpool now trades near multi-year lows after a steep slide in the share price. Does that reset leave more downside risk, or a valuation gap that still favours new buyers?
Most Popular Narrative: 43% Undervalued
On the most followed view of Whirlpool, a fair value of $50.67 sits well above the latest $28.83 close, which puts the recent slide in a very different light for anyone weighing risk against potential upside.
Ongoing factory consolidation, automation investments and logistics footprint changes in North and Latin America, including site modernizations and distribution center reductions, are expected to deliver at least $150 million of 2026 cost savings and roughly $180 million of annualized EBIT benefits from 2027 onward, which could support higher Whirlpool net margins and earnings as these programs ramp.
See why 30 investors see Whirlpool as 43% undervalued.
Result: Fair Value of $50.67 (UNDERVALUED)
Still, Whirlpool’s heavy reliance on mature North American and European appliance markets, combined with very weak recent industry volumes, could stall that recovery story.
Find out about the key risks to this Whirlpool narrative.
Another View On Whirlpool’s Valuation
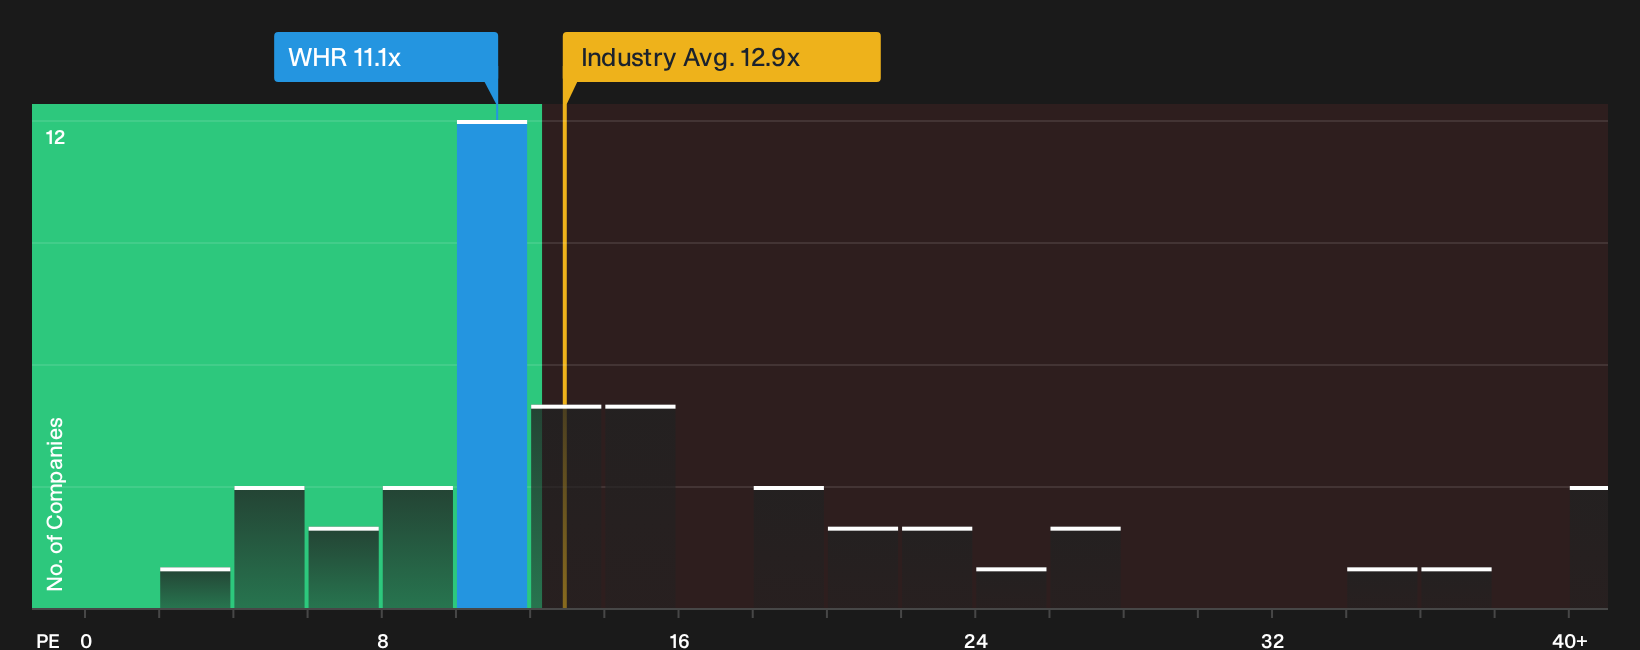
On earnings multiples, Whirlpool looks mixed. The shares trade on an 11.1x P/E, slightly richer than close peers at 10.2x but cheaper than the wider US Consumer Durables group at 12.9x and below a fair ratio of 24.4x. Is that a cushion or a value trap if sentiment worsens?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Whirlpool is clearly split, which is exactly when it pays to move fast and test the numbers against your own expectations. To weigh both the upside case and the pressure points in one place, start with the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Whirlpool?
If Whirlpool has your attention, do not stop your research here. Cast the net wider and pressure test your thesis against other potential opportunities.
- Hunt for underappreciated quality by scanning our curated 28 high quality undervalued stocks. These appear to combine solid fundamentals with more restrained pricing.
- Target resilience by checking the list of solid balance sheet and fundamentals (25 results), which highlights companies with stronger financial footing and cleaner balance sheets.
- Spot potential early-stage opportunities through the 14 elite penny stocks with strong financials, where smaller businesses may offer different risk and reward profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com